
Stock Yards Bancorp (SYBT) Posted Stronger Earnings, Is The Stock Fully Priced?
Stock Yards Bancorp (SYBT) just posted third quarter results that combined higher net interest income and net income with a sharp rise in net charge offs, giving investors a mixed but data rich update.
Recent trading has leaned positive for Stock Yards Bancorp, with a 1-day share price return of 1.80% and a 7-day share price return of 6.14% lifting the stock to $81.53, even though the 90-day share price return declined 2.86%.
That short term momentum sits against a broader backdrop, where the year to date share price return is 25.05% and the 3-year total shareholder return is about 2x. This suggests investors have been willing to reprice the bank as earnings data and the spike in net charge offs reshape perceptions of both growth potential and credit risk.
Scan how Stock Yards Bancorp stacks up against other profitable regional lenders by reviewing a curated list of solid balance sheet and fundamentals (24 results) that highlights different approaches to managing credit risk and earnings power.
After a rapid move to $81.53 on strong earnings but heavier credit losses, the choice is stark: pay up for Stock Yards Bancorp now, or wait and hope valuation gives you another clean entry.
Preferred P/E of 16.2x for Stock Yards Bancorp: Is it justified?
Valuation for Stock Yards Bancorp currently leans rich on traditional metrics, with a P/E of 16.2x sitting above several key reference points even as the SWS DCF model flags the shares as trading 34.1% below an estimated future cash flow value of $123.80 versus the last close of $81.53.
The P/E multiple compares what investors are paying for each dollar of earnings. For a regional bank with $437.98m in revenue and $156.77m in net income, it is a quick way of gauging how the market weighs earnings power against perceived credit and rate risk.
For Stock Yards Bancorp, that 16.2x P/E is described as expensive both against the peer group average of 16.1x and against the wider US Banks industry at 11.3x. It also runs well ahead of the estimated fair P/E of 12.2x. The market could eventually lean toward that level if expectations around earnings growth, which are forecast at 9.44% per year, do not support a premium.
Explore the SWS fair ratio for Stock Yards Bancorp.
Result: Price-to-Earnings of 16.2x (OVERVALUED).
Still, heavier net charge offs and a richer 16.2x P/E mean any setback in credit quality or earnings expectations could quickly pressure the Stock Yards Bancorp story.
Find out about the key risks to this Stock Yards Bancorp narrative.
Another View: Stock Yards Bancorp Through A Cash Flow Lens
The first look at Stock Yards Bancorp focused on its 16.2x P/E, which screens as expensive. A different picture appears when using the SWS DCF model, which suggests the shares trade about 34.1% below an estimated future cash flow value of $123.80.
That gap frames a simple question for you: Is the current price of $81.53 a rich multiple of today’s earnings or a discount to tomorrow’s cash flows, and which yardstick feels more reliable for a regional bank with $437.98m in revenue and $156.77m in net income?
Look into how the SWS DCF model arrives at its fair value.
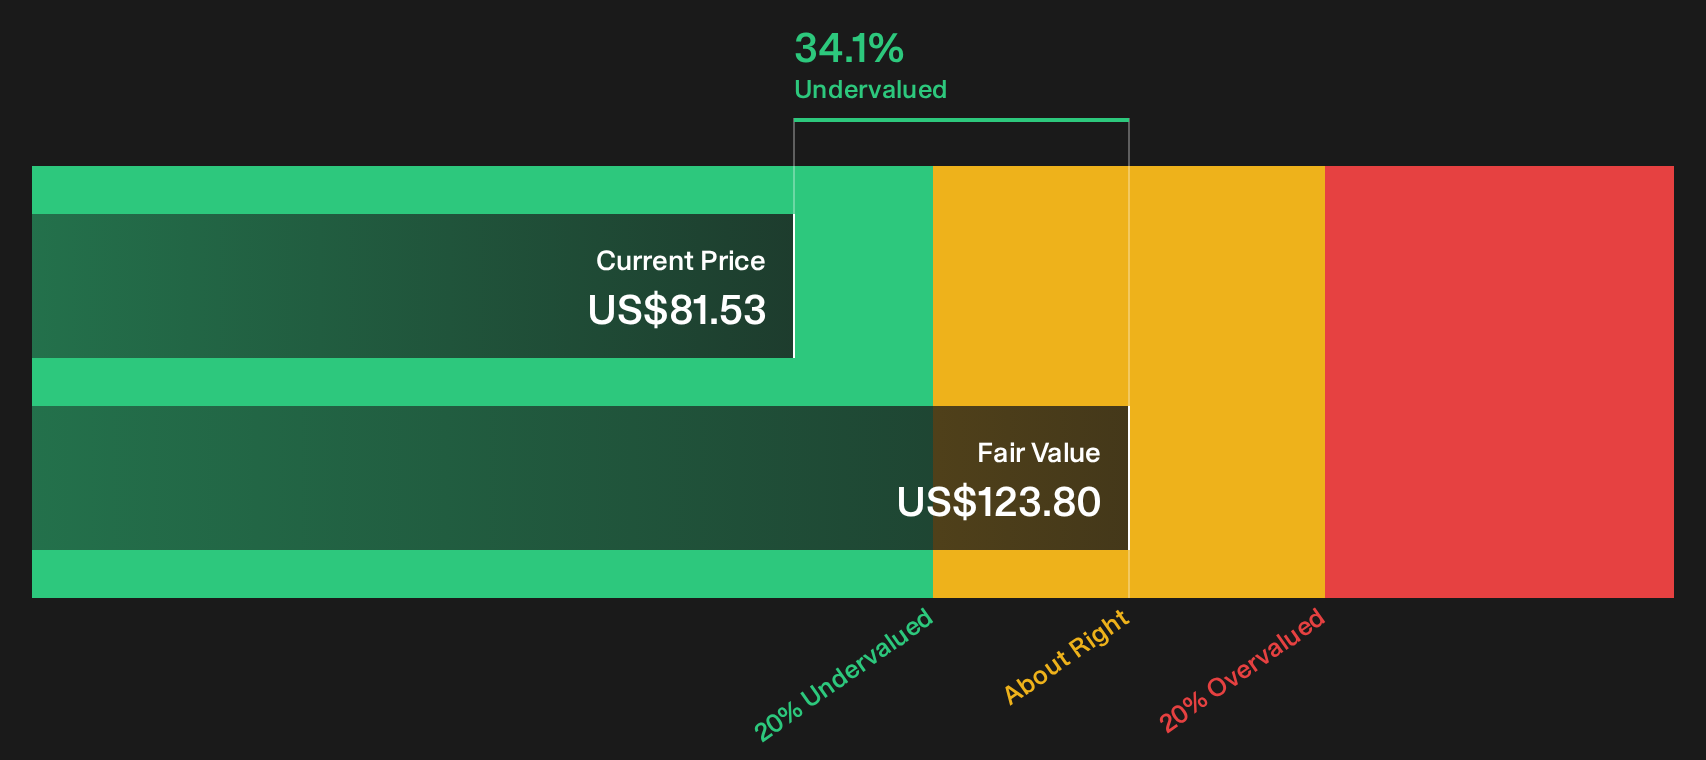
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Stock Yards Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or quiet opportunity? If the combined picture of richer valuation metrics and flagged rewards has you curious, take a closer look at the 4 key rewards.
Looking for more Stock Yards Bancorp sized ideas?
If Stock Yards Bancorp has sharpened your focus on quality and risk, do not stop here. Broaden your watchlist with targeted ideas that match your style.
- Target potential value setups by scanning a curated pool of underpriced quality businesses through the 35 high quality undervalued stocks.
- Lock in income focused opportunities by reviewing a hand picked 5 dividend fortresses that may suit a yield driven approach.
- Prioritise capital protection by filtering for resilient candidates with the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com