
Top Dividend Stocks For November 2026
Soaring energy prices have pushed inflation sharply higher in places like the euro zone and the Philippines, and central banks from the Bank of England to the Bank of Japan are lifting interest rates to contain it. That mix makes reliable cash payouts more valuable to you. This article looks at three high-yield dividend payers with yields above 3% that focus on steady, well covered and growing income streams.
The three stocks highlighted here offer a compelling starting point if you want exposure to reliable, well covered dividend income that clears the 3% yield mark. However, if you want the absolute best, these 5 dividend aristocrats stocks are the cream of the crop.
DICK'S Sporting Goods (DKS)
DICK'S Sporting Goods sits in this Dividend Powerhouses group because its nationwide stores and digital channels throw off recurring cash flow that supports a regular payout, even as management juggles growth projects and a complicated retail backdrop.
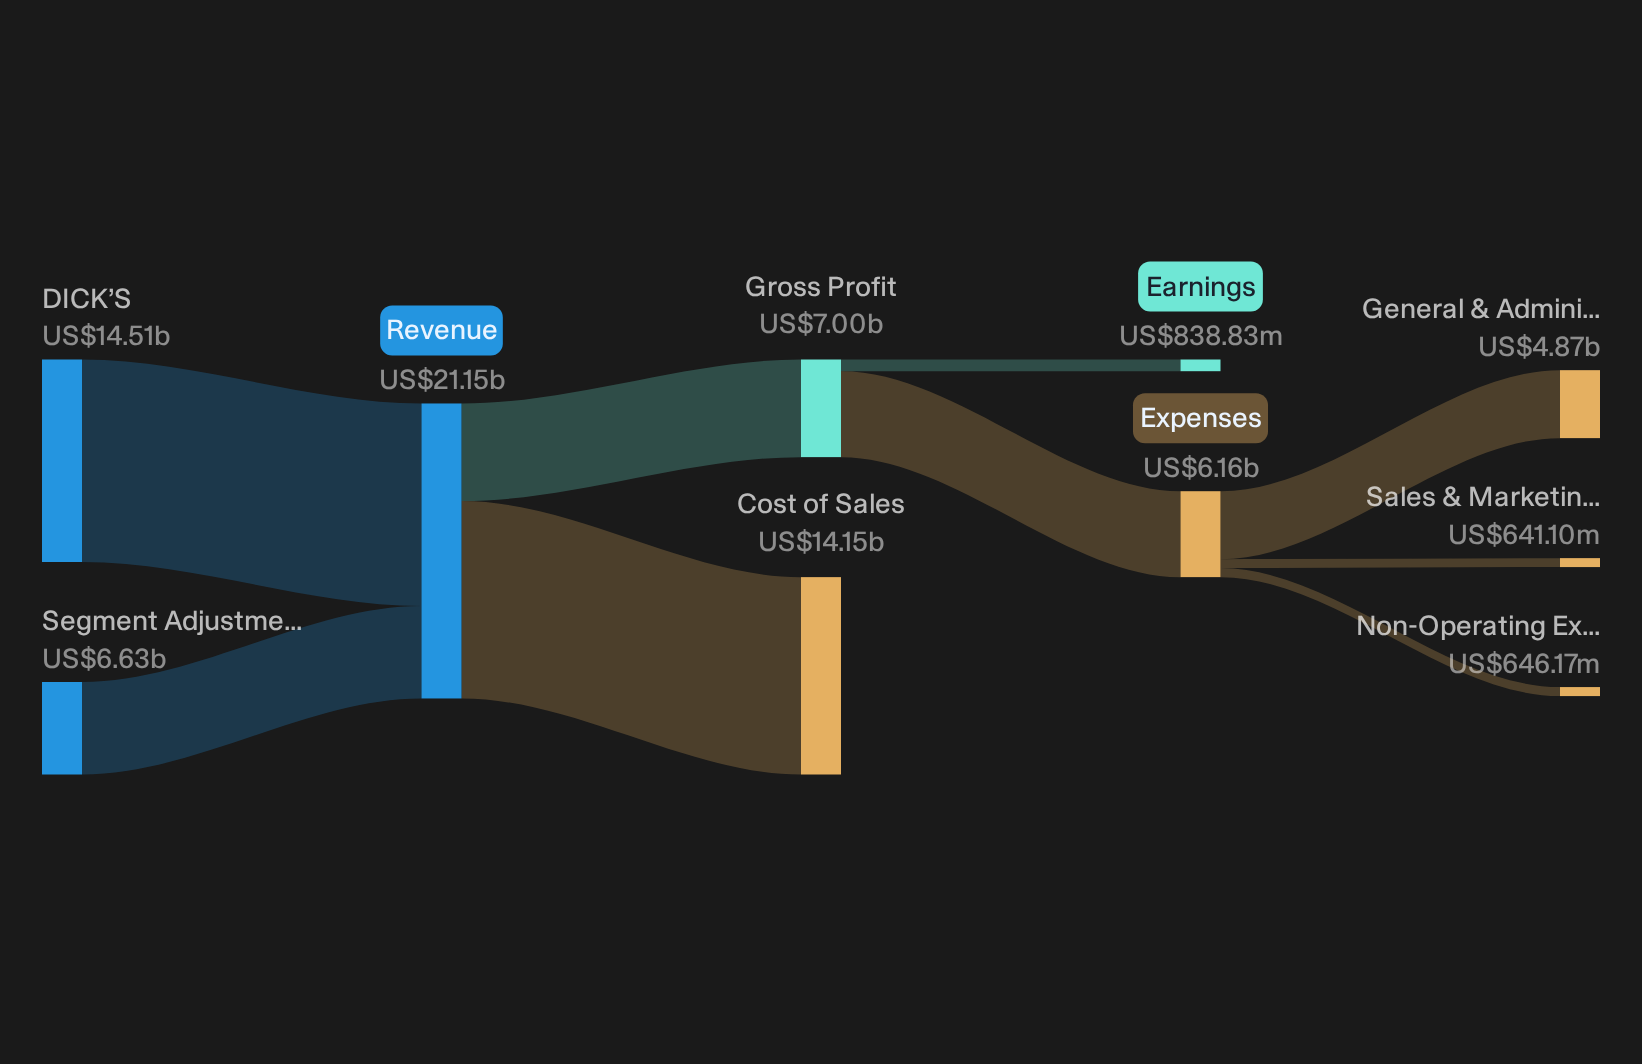
DICK'S Sporting Goods runs an omni-channel sports retail operation spanning equipment, apparel, footwear and specialty banners that produced about US$14.5b in revenue from its DICK'S segment, with adjustments taking total reported revenue higher, and the stock is valued around US$12.2b in market cap.
"The Foot Locker "inflection point" has been deferred. Full-year Foot Locker pro forma comp guidance moved from +1.5% to 3% growth to -2% to flat, and operating income expectations swung from a $110M to $150M profit to a $40M to $80M loss."
What matters next for dividend-focused investors is how one unresolved pressure on the wider retail margin structure finally breaks.
That unresolved pressure is exactly where income investors need clarity, and the full narrative for DICK'S Sporting Goods explains how DICK'S Sporting Goods could turn a squeezed margin picture into a strengthening dividend story.
LCI Industries (LCII)
LCI Industries supplies the nuts and bolts of the RV world, and for a Dividend Powerhouses screen that prizes well covered income, its steady aftermarket and OEM components business is where reliable cash generation starts.
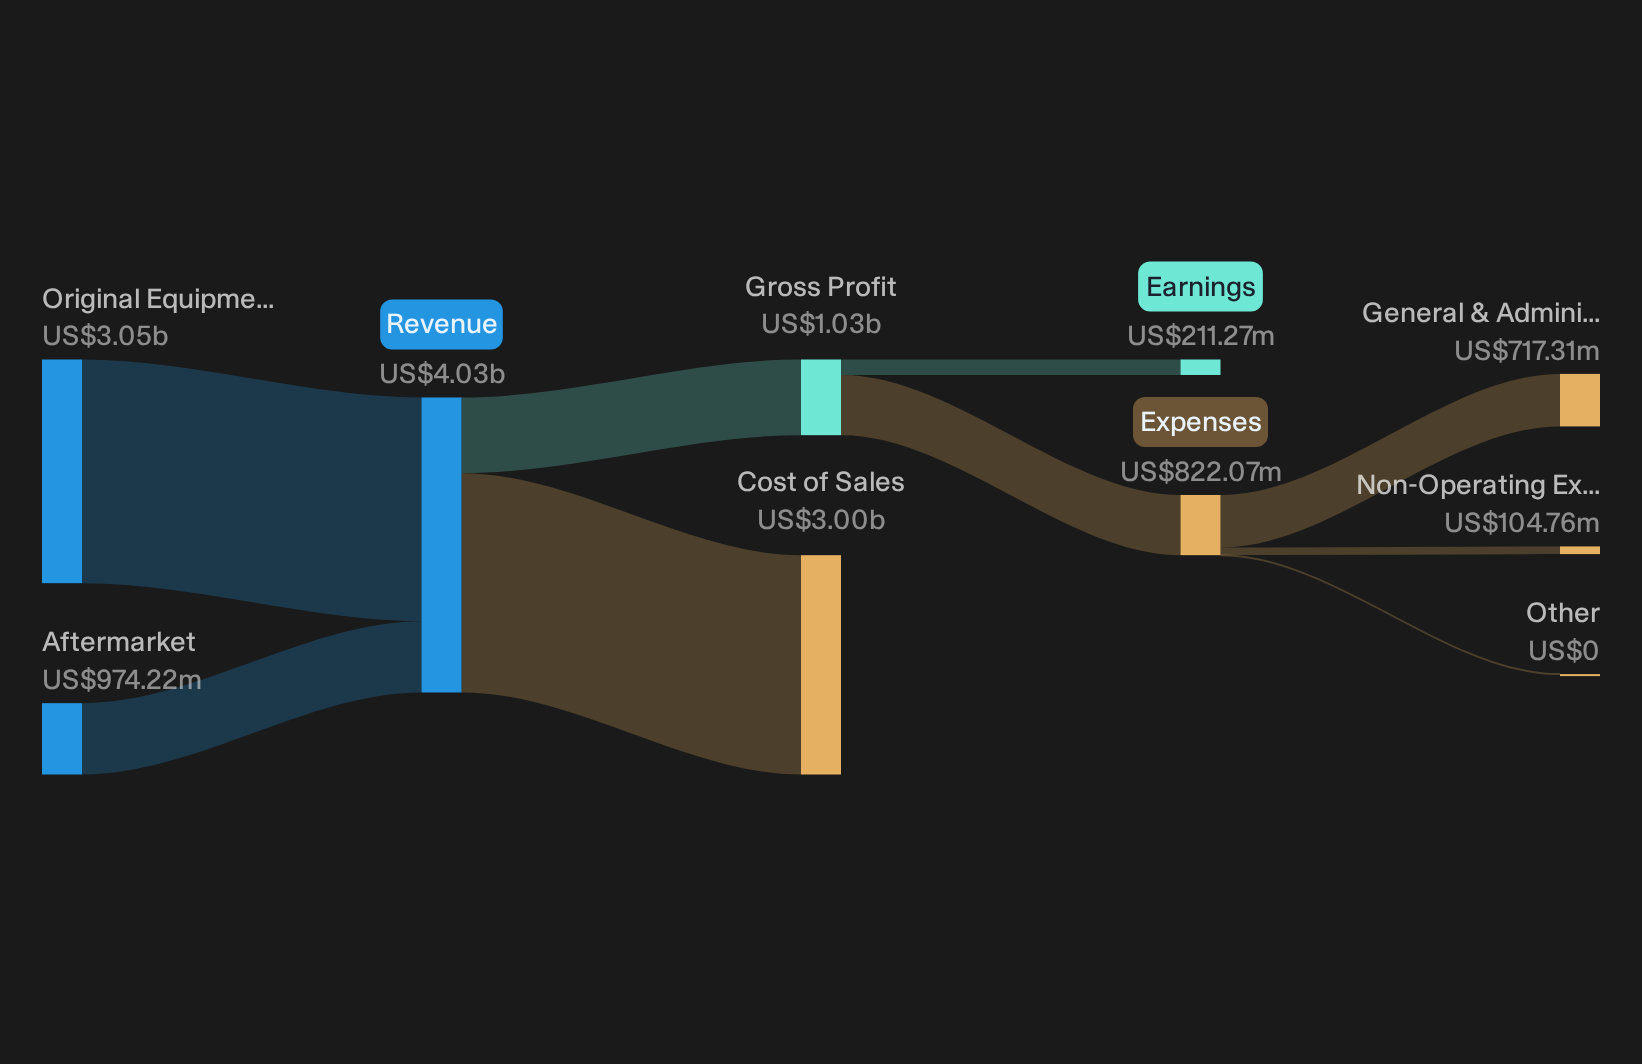
LCI Industries manufactures high margin RV components that feed recurring aftermarket and OEM demand, generating about US$3.1b from OEM customers and US$974 million from aftermarket channels, and is valued at roughly US$2.5b in market cap.
"Growth in the higher margin aftermarket segment, backed by an installed base with more than US$15b of replaceable content and around 1.5m units projected to enter repair cycles over the next several years, gives LCI Industries a path to increase revenue mix toward businesses that already carry around 14% operating margins."
What really shapes the dividend story from here is how one quietly evolving shift in the RV ecosystem filters through to those margins.
That margin filter is exactly where the story gets interesting, and the full narrative for LCI Industries unpacks how LCI Industries could turn mix shifts into accelerating income strength.
Bank OZK (OZK)
Bank OZK is a full service lender and deposit institution where interest income and fees from everyday banking fund a consistent dividend stream that fits the Dividend Powerhouses theme of well covered, stable cash payouts supported by core operations rather than one off gains.
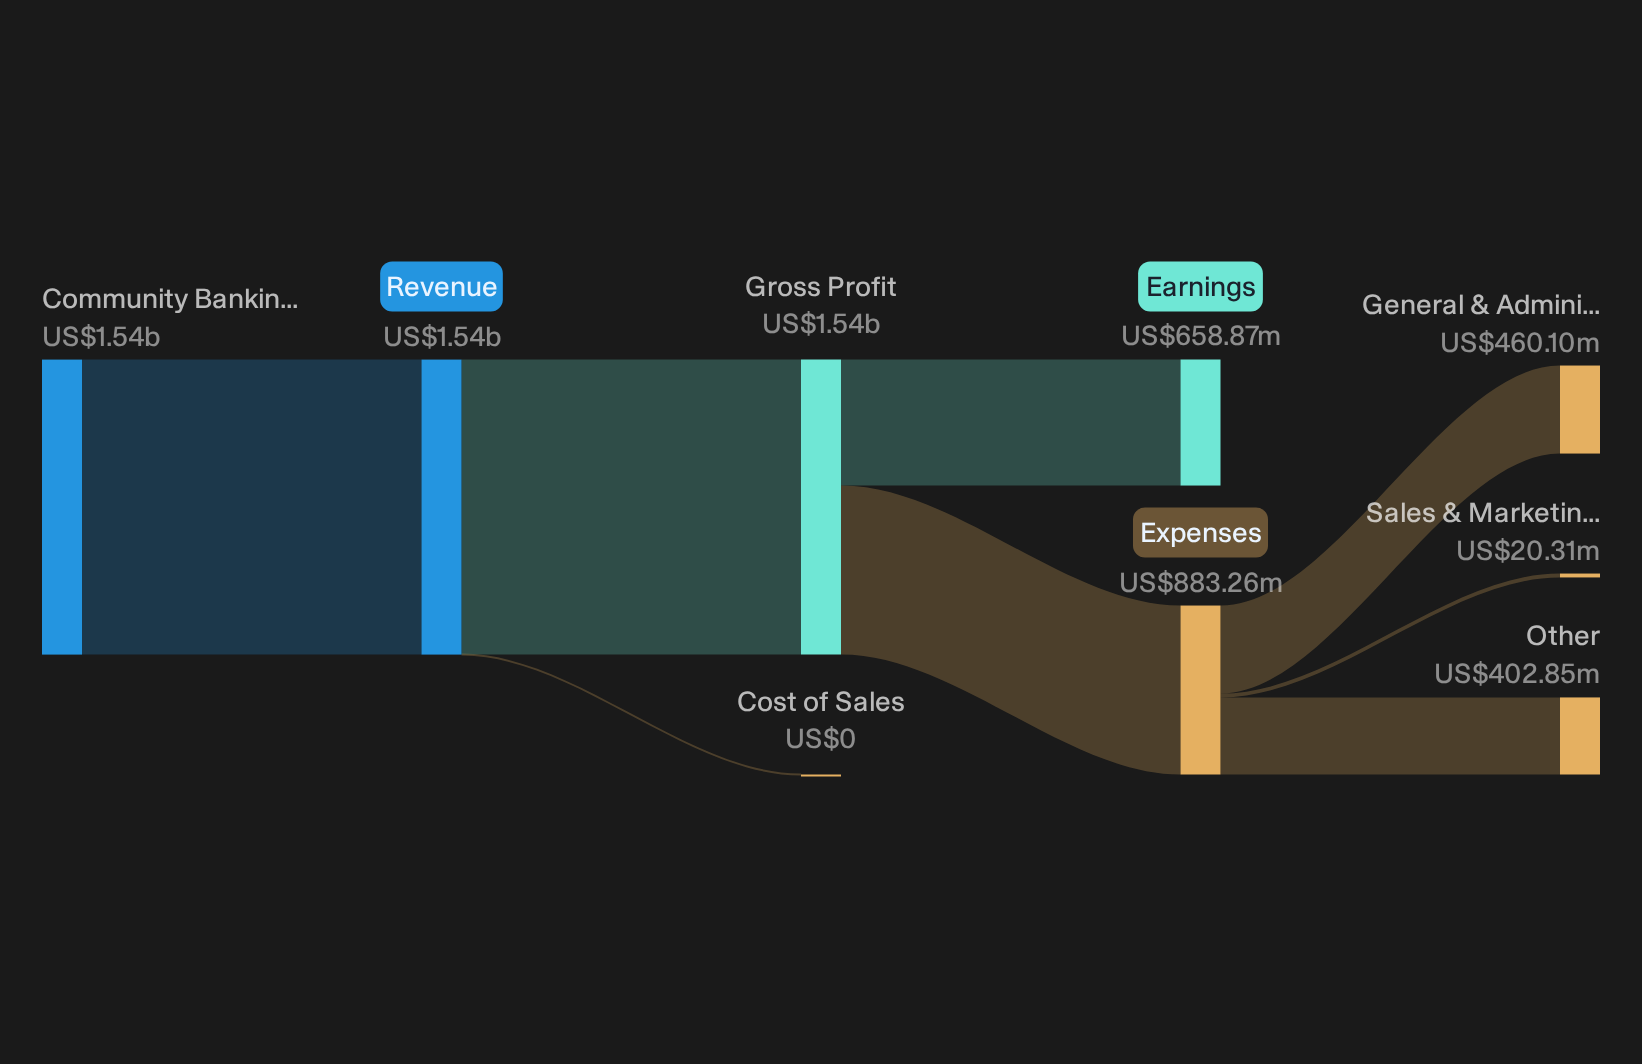
Bank OZK generates about US$1.5b in revenue from its Community Banking segment in the United States, combining loans, deposits and fee services, and the stock carries a market value of roughly US$5.5b.
For income focused investors, Bank OZK matters because its 3%+ yield is closely tied to the health of its lending and fee engine, and management is actively reshaping that engine to support steadier cash generation over time.
"The accelerated buildout of the Corporate and Institutional Banking platform, which now spans more than seven lending verticals and over 42 industry niches and is expected to reach a portfolio size similar to RESG by 2027, is set to increase floating rate lending spreads and fee income from roles as administrative agent or joint lead on single lender and small club deals. This supports net interest margin and noninterest revenue."
This raises the question of what could occur if one key source of earnings pressure eases at the same time that this new mix of interest and fee income, which is positioned as higher quality, becomes more established.
If that earnings pressure eases as the new lending and fee mix beds in, the full narrative for Bank OZK shows how Bank OZK's payout story could quietly accelerate.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities can move from quiet to crowded fast. Spot potential breakouts and building momentum while the data is still under the radar for now. Act now.
- Target resilient cash generators and stress test your portfolio against markets that drop suddenly with a curated set of 31 resilient stocks with low risk scores before the crowd piles in.
- Hunt for durable yield and diversify beyond these three dividend payers through a focused group of 5 dividend fortresses while payout visibility still matters most.
- Scout the next wave of infrastructure demand and ride potential momentum in grid upgrades using a hand picked universe of 41 power grid technology and infrastructure stocks while they remain quietly priced.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com