
COMPASS Pathways (CMPS) Nears COMP360 NDA Submission, Is It Still A Bargain?
COMPASS Pathways (NasdaqGS:CMPS) has moved into the spotlight after confirming it expects to complete its rolling FDA New Drug Application for psilocybin therapy COMP360 within weeks, alongside a sharply lower third quarter net loss.
The latest NDA update and sharply lower quarterly loss arrive after a volatile spell for COMPASS Pathways, with the share price down 25.6% over 30 days and 36.5% over 90 days. The stock is still showing a 31.3% year to date share price return and 53.9% one year total shareholder return, which points to longer term momentum but fading near term enthusiasm as investors weigh growth potential against regulatory and competitive risks.
Compare COMPASS Pathways with other high potential biotech stories by scanning our hand picked 19 high quality undiscovered gems that are also drawing attention around key clinical or regulatory milestones.
After a sharp pullback but with COMPASS Pathways still showing strong gains over the past year, the real debate is whether most of the upside has already played out or if valuation still leaves meaningful headroom.
Most Popular Narrative: 65% Undervalued
COMPASS Pathways last closed at $8.60 while the most followed narrative pegs fair value at $24.47. This frames the recent pullback as a valuation gap story rather than just a sentiment swing.
Completion of enrollment in the COMP006 Phase III trial and the plan to use 9 week data from Part A together with 26 week COMP005 data to support a rolling NDA process could shorten the path to potential approval, which would bring revenue forward and may support earlier earnings visibility.
See why 15 investors see COMPASS Pathways as 65% undervalued.
Result: Fair Value of $24.47 (UNDERVALUED)
Still, that story can change quickly if Phase III data disappoints regulators or if higher pre launch spending forces COMPASS Pathways to raise fresh capital on dilutive terms.
Find out about the key risks to this COMPASS Pathways narrative.
Another View: What The P/B Tells You About COMPASS Pathways
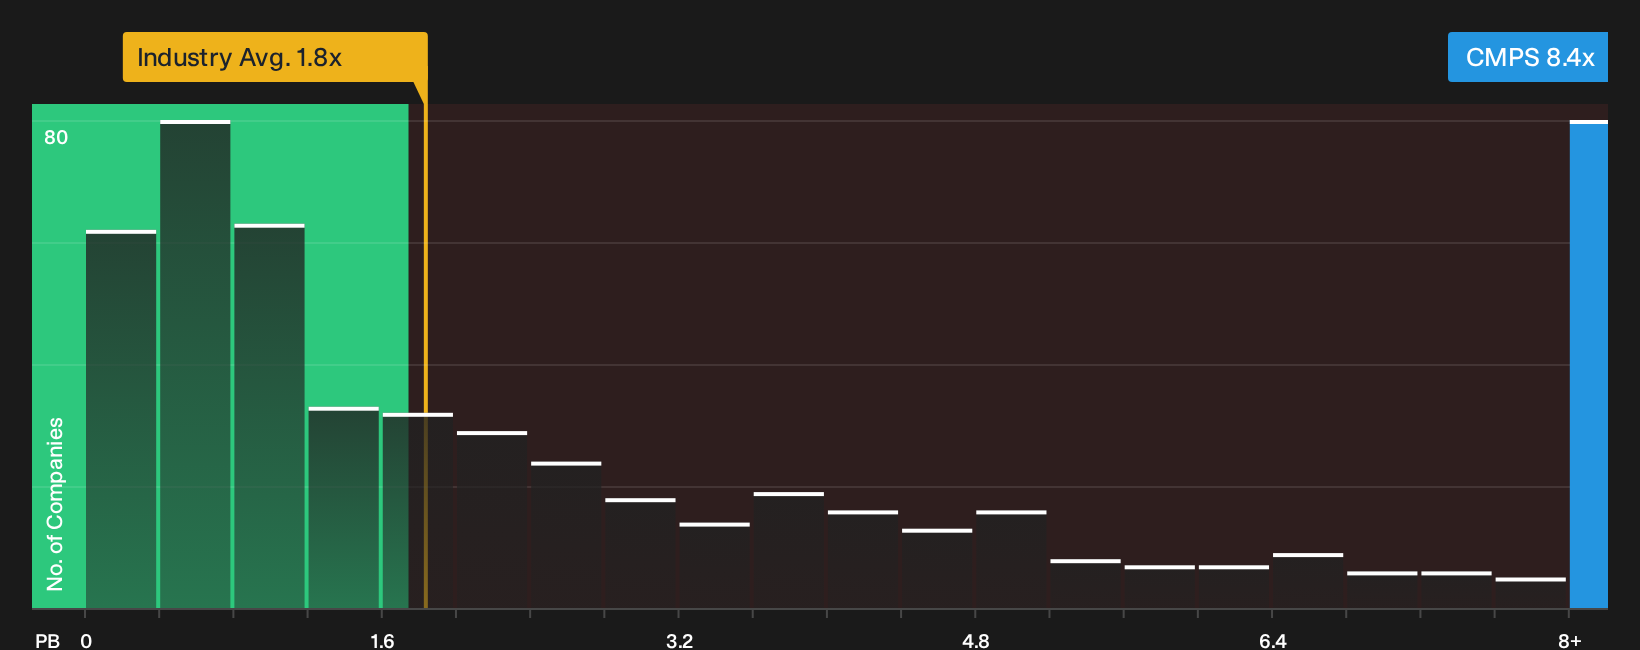
The story looks very different once you stop thinking in terms of fair value models and instead look at what investors are paying for COMPASS Pathways today. The stock trades on a P/B of 8.4x versus a US Biotechs industry average of 1.8x and a peer average of 4.3x. This indicates that the market is paying a much higher price for each dollar of net assets despite the business being loss making with no meaningful revenue yet.
That kind of premium can reflect confidence in COMP360 and future growth. However, it also raises valuation risk if the pipeline or regulatory path does not match expectations and the P/B ratio moves closer to the lower peer or industry levels. The fair ratio cannot yet be pinned down by Simply Wall St data, so the key question for you is whether this premium feels like justified optimism or a thin margin for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around COMPASS Pathways can feel confusing, so move quickly, review the data on both sides, and weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond COMPASS Pathways?
If COMPASS Pathways has your attention, do not stop there. Broaden your watchlist with a few focused stock ideas built from clear, data driven filters.
- Target potential mispricings by scanning a curated set of 35 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them yet.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (24 results) that can help you concentrate on businesses with stronger financial footing.
- Boost your income focus by checking a hand picked pool of 5 dividend fortresses offering higher yields that might suit a cash flow oriented approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com