
Is Jazz Pharmaceuticals (JAZZ) Undervalued On Raised 2026 Guidance And Ziihera Data?
Jazz Pharmaceuticals (JAZZ) is back in focus after record third quarter revenue, a higher 2026 sales outlook, and fresh oncology data around Ziihera coincided with an upward move in the share price.
The recent move takes Jazz Pharmaceuticals’ share price to US$234.66, with a 7 day share price return of 12.91% and a year to date share price gain of 35.52%. Total shareholder return over 1 year sits at 75.05% and 101.39% over 3 years, suggesting positive momentum as investors respond to raised 2026 revenue guidance, fresh Ziihera survival data, the Actio Biosciences acquisition and the new US$500m buyback program.
Scan how Jazz Pharmaceuticals compares to other oncology and rare disease opportunities by zeroing in on our hand picked 19 high quality undiscovered gems with similar cash flow and pipeline profiles.
After a sharp re rate on Ziihera data, higher guidance and the new US$500m buyback, the real puzzle now is whether Jazz Pharmaceuticals still offers enough upside to justify taking fresh risk at this level.
Most Popular Narrative: 20% Undervalued
At a last close of $234.66 versus a narrative fair value of $294.27, the most followed view sees Jazz Pharmaceuticals trading at a material discount while still hinging on a small number of very specific execution milestones.
Ongoing growth in the sleep and epilepsy franchise, with Xywav guided for double digit growth in 2026 and Epidiolex pursuing four new trials and a solid oral dose with expected exclusivity into the late 2030s, can extend the duration and scale of these cash flow streams and support more stable earnings.
See why 36 investors see Jazz Pharmaceuticals as 20% undervalued.
Result: Fair Value of $294.27 (UNDERVALUED)
Still, the whole Jazz Pharmaceuticals story can change quickly if Ziihera underperforms in new HER2 indications or if generic pressure bites harder into the oxybate sleep franchise.
Find out about the key risks to this Jazz Pharmaceuticals narrative.
Another View: What Multiples Say About Jazz Pharmaceuticals
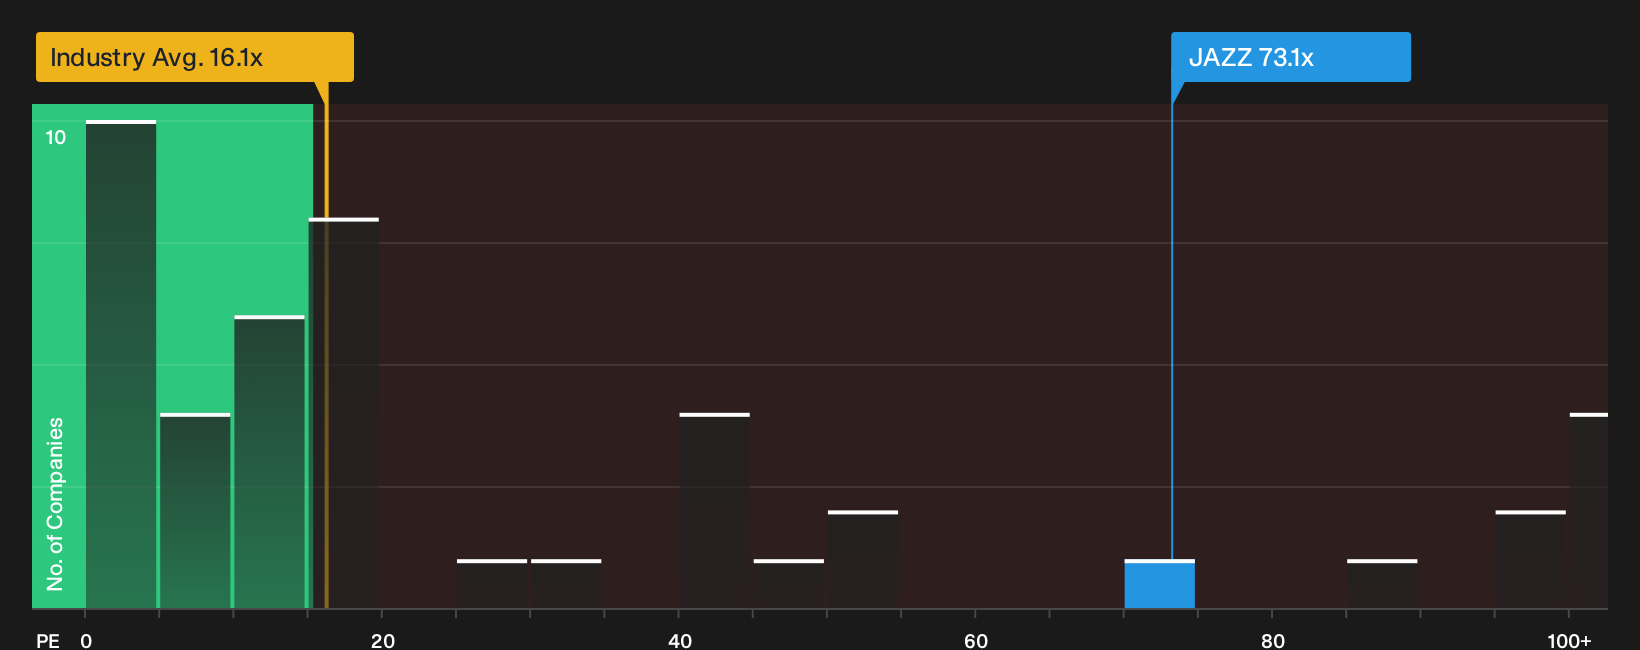
The story looks different once the focus shifts from fair value models to what the P/E ratio implies. Jazz Pharmaceuticals trades on a 73.1x P/E, compared with a fair ratio of 36.6x, the US pharmaceuticals industry at 16.2x, and peer average of 41.4x. That is a steep premium. Is the market overpaying for the growth narrative, or simply pulling future optimism forward?
For a closer look at how this pricing gap lines up with the underlying numbers and risk profile, tap into our valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big moves and bold narratives around Jazz Pharmaceuticals only matter if the numbers make sense to you, not just to the crowd. Act quickly, pressure test the upside against the weak spots, and weigh both the potential and the hazards by running through the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Jazz Pharmaceuticals?
If you stop with Jazz Pharmaceuticals, you only see one angle. Broaden your watchlist and compare fresh ideas that could fit your risk, income, and quality preferences.
- Target potential mispricing by scanning a 35 high quality undervalued stocks that pairs robust balance sheets with cash flows the market may be underrating.
- Strengthen income potential by reviewing a 5 dividend fortresses built around higher yielding payouts with an eye on durability.
- Dial down portfolio stress by checking a 31 resilient stocks with low risk scores focused on resilient financial profiles and calmer price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com