
Is PROG Holdings (PRG) Undervalued On Its Earnings Beat And Lower Guidance?
PROG Holdings (PRG) has become a focal point for investors after a packed October 28 update that combined revised guidance, fresh quarterly earnings and an expanded share repurchase plan.
PROG Holdings has attracted traders in the short term, with the share price jumping 9.2% in the last session and delivering a 29.1% 1 month share price return as the earnings beat, guidance revision and buyback expansion reset expectations. That near term strength comes after the 90 day share price return declined 8.2%, while the 1 year total shareholder return of 42.4% and 3 year total shareholder return of 46.4% suggest longer term holders have still seen meaningful gains even though the 5 year total shareholder return is down 12.7%. As a result, the recent surge appears more like momentum rebuilding than a fresh start.
Scan other stocks where management is buying back shares and guidance is under pressure, starting with our handpicked 35 high quality undervalued stocks that combines balance sheet strength with discounted prices.
After a 29.1% one month surge and fresh guidance that now points lower, PROG Holdings trades about 18% below analyst targets and roughly 22% under some intrinsic value estimates. Is the recent repricing already generous or still conservative?
Most Popular Narrative: 19% Undervalued
Against the last close at $39.89, the most followed narrative pegs PROG Holdings' fair value at $49. This implies a clear valuation gap that depends on how its ecosystem story develops.
Ongoing traction in diversifying revenue through additional platforms in the ecosystem, including Purchasing Power’s rising GMV and expanding adjusted EBITDA contribution and MoneyApp within the broader suite, supports a larger consolidated profit base that is not solely tied to Progressive Leasing earnings.
See why 5 investors see PROG Holdings as 19% undervalued.
Result: Fair Value of $49 (UNDERVALUED)
Still, credit write off pressure and any slowdown in Four or Purchasing Power scaling could quickly challenge the PROG Holdings undervaluation story that investors are leaning on.
Find out about the key risks to this PROG Holdings narrative.
Another View: What PROG Holdings' P/E Is Saying
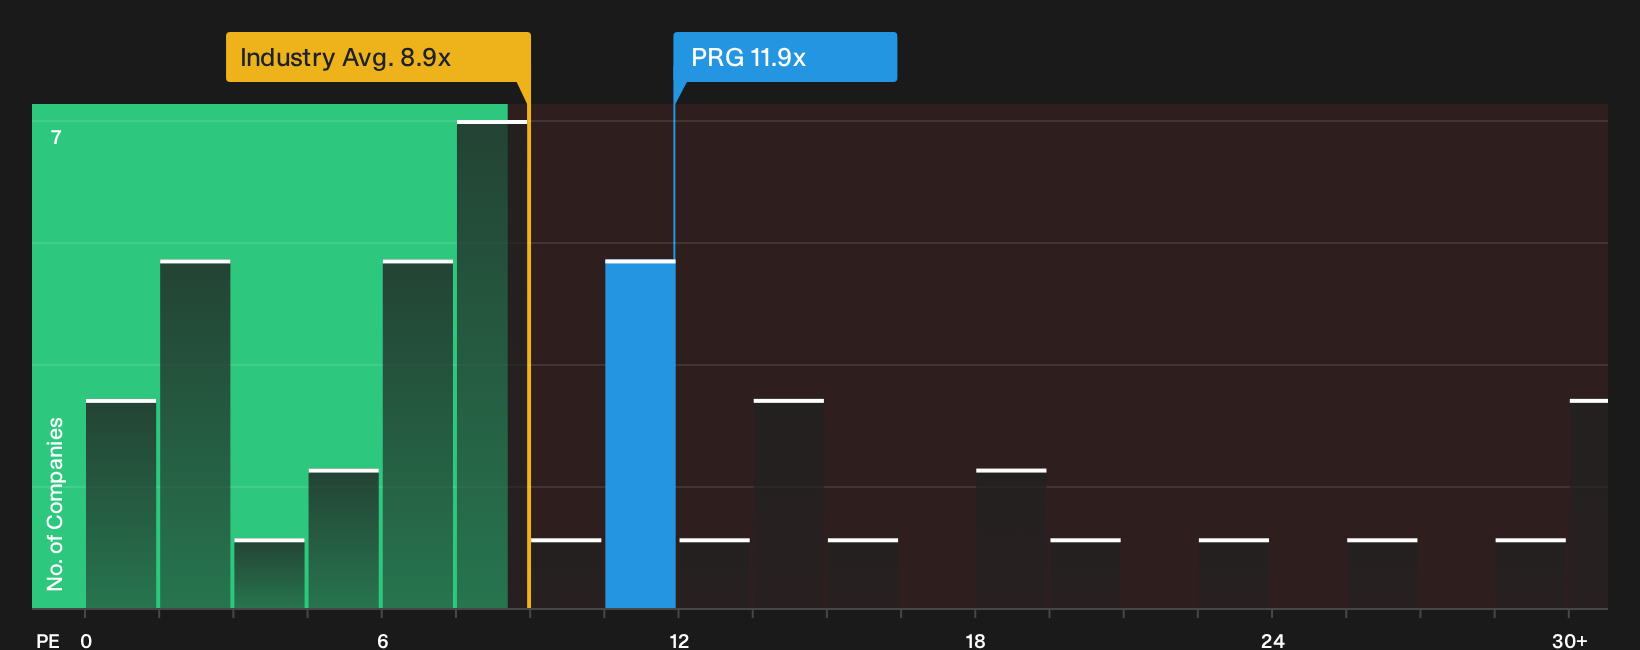
That 19% discount to fair value looks appealing on paper, but the P/E story is more cautious. PROG Holdings trades at 11.9x earnings, above the US Consumer Finance industry at 8.5x and also above the peer average of 11.1x, while only slightly below its fair ratio of 12.3x. For investors, that mix suggests some upside may already be reflected in the price and less room for error if sentiment turns.
This leads to a straightforward question. Does the earnings outlook justify paying a premium to the sector when growth forecasts are not especially high, or is this where valuation risk starts to become more important while the ecosystem story develops?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on PROG Holdings can pull investors in opposite directions, so consider acting promptly, review the full picture, and weigh both the upside and downside using the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond PROG Holdings?
If you limit your search to PROG Holdings, you may overlook other opportunities that align with your style, your risk tolerance, and the type of portfolio you want to build.
- Explore higher yield potential and focus on income streams that fit your objectives with our hand picked 5 dividend fortresses.
- Look for stronger balance sheets and steadier financial footing by filtering through the list of solid balance sheet and fundamentals (24 results).
- Identify under the radar opportunities ahead of the crowd by scanning the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com