
Performance Food Group (PFGC) Could Be 11% Undervalued After Its Earnings Beat
Performance Food Group (PFGC) drew fresh attention after reporting first quarter results on 4 November, with sales of US$18.0b and net income of US$129.5m, both higher than a year earlier.
Performance Food Group’s stronger quarter has arrived alongside a sharp shift in sentiment, with the stock jumping 13.5% on the day and posting a 7 day share price return of 13.9%. The 1 year total shareholder return of 14.7% and 3 year total shareholder return of 82.7% point to momentum that has cooled in recent months but not reversed.
Scan how Performance Food Group compares with other potential breakout ideas in food distribution and consumer staples by reviewing our curated list of 35 high quality undervalued stocks.
Bulls point to Performance Food Group’s earnings beat and market share gains, while bears flag rich past returns and cautious revenue guidance. Which side does the current valuation support next?
Most Popular Narrative: 11% Undervalued
Against a last close of $109.57, the most followed narrative pegs Performance Food Group's fair value at $123.23, implying an 11.1% gap that hinges on execution in case growth, procurement, and efficiency projects.
Procurement initiatives that are expected to reach or exceed the high end of the US$120m to US$125m synergy target by fiscal 2028, together with the reported US$0.34 per case gross profit uplift in Q4 2026, set up a structural tailwind for net margins and EBITDA.
See why 3 investors see Performance Food Group as 11% undervalued.
That fair value estimate relies on a 7.76% discount rate and a long list of moving parts, from independent restaurant case growth to private brand penetration and AI supported routing and warehouse projects. It anchors on the view that these levers can support earnings progress even though Performance Food Group's current net margin is just 0.6% and interest coverage is described as weak in the financial health checks.
The same narrative framework expects PFGC's earnings to expand about 18% per year and revenue to rise 6.8% annually over the next few years, with profit margins modeled to reach around 1.1%. Those forecasts imply a future P/E of 28.6x on projected 2029 earnings, compared with a current P/E of 43.7x and a Consumer Retailing sector average of 18.2x, which suggests the market is already assigning a premium multiple while the narrative still sees room relative to its own fair value.
Analysts following this storyline are also building in share count creep of roughly 0.46% a year and a fair value that is slightly below the Simply Wall St DCF based future cash flow estimate of $307.42. That DCF result, which sits far above both the $123.23 narrative fair value and the latest share price, points to a wide spread between cash flow based modeling, earnings based targets, and where the stock actually trades.
Result: Fair Value of $123.23 (UNDERVALUED)
Still, the whole Performance Food Group narrative leans heavily on Convenience trends stabilising and Cheney Brothers integration costs not lingering beyond the expected synergy timeline.
Find out about the key risks to this Performance Food Group narrative.
Another View: Performance Food Group Looks Expensive On Earnings
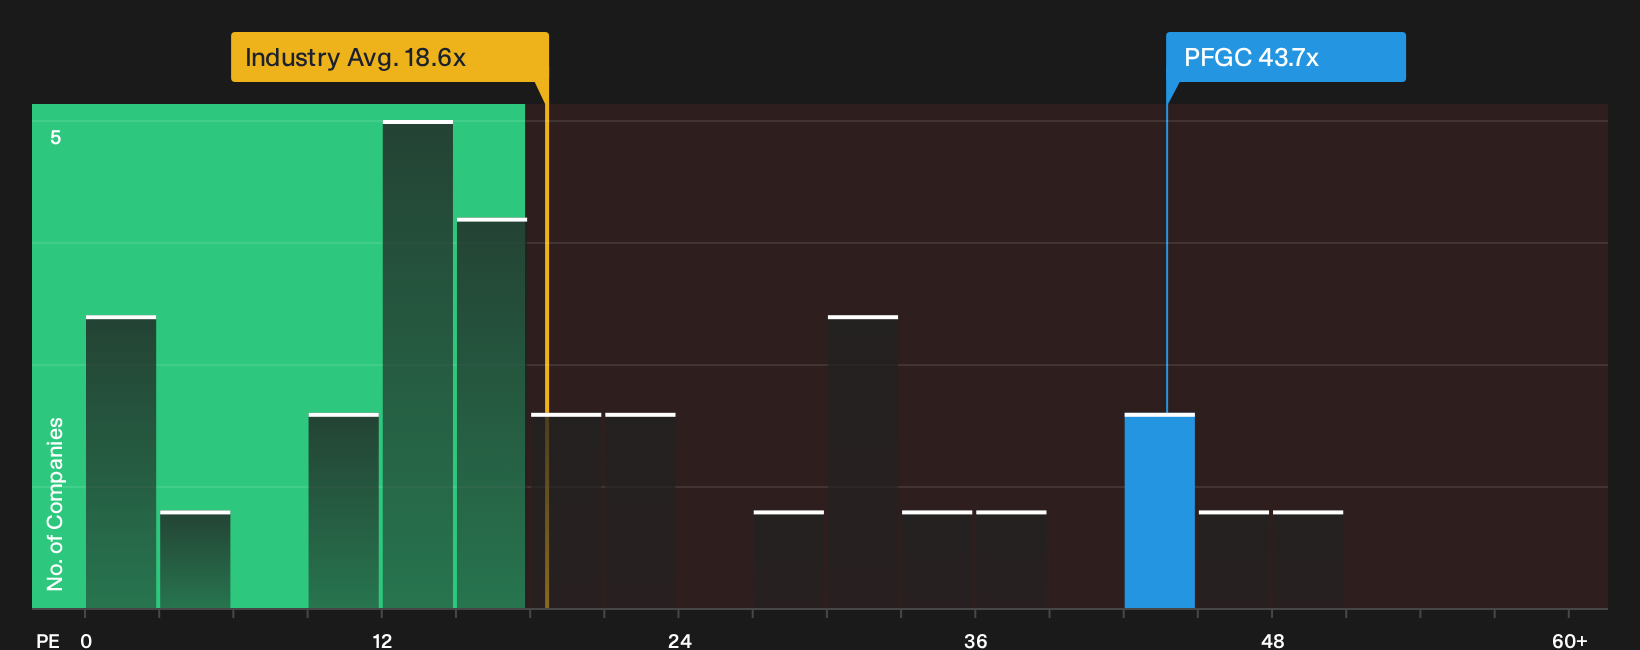
Look past the fair value narrative and the SWS DCF output, and the P/E story for Performance Food Group sends a different signal. The shares trade on 43.7x earnings, compared with a fair ratio of 29x, the US Consumer Retailing sector at 17.7x, and peers at 33.4x.
That gap suggests valuation risk if sentiment cools or if earnings progress simply tracks the current 18% annual forecast rather than beating it decisively. For investors comparing potential entry points, the question becomes whether PFGC grows into this premium or whether the multiple drifts back toward the fair ratio over time.
See what the numbers say about this price in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
For a clearer sense of how PFGC’s earnings multiple stacks up against sector and peer benchmarks on today’s price, review the latest visual comparison in
Next Steps
Mixed messages on Performance Food Group’s valuation and risk can pull you in opposite directions, so weigh the upside and downside yourself using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Performance Food Group?
If Performance Food Group has sharpened your focus on valuation and quality, do not stop here. The next opportunity you rate highly could be sitting just outside your current watchlist.
- Spot potential bargains early by scanning companies that combine quality and pricing support through the 35 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Hunt for less crowded opportunities by reviewing the 19 high quality undiscovered gems before the market pays closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com