
Howard Hughes Holdings (HHH) Faces A Third Quarter Test As Vantage Fuels Undervalued View
Howard Hughes Holdings (HHH) is heading into its third quarter 2026 report with investor attention fixed on housing driven momentum in its master planned communities and the early impact of the Vantage acquisition.
Recent trading has been strong for Howard Hughes Holdings, with the share price delivering a 7 day gain of 7.32% and a 30 day share price return of 10.33% on the way to US$79.06. The 90 day share price return of 16.18% points to building momentum. However, the 1 year total shareholder return of 0.92% and 5 year total shareholder return, which declined 10.98%, show a much flatter long run picture as investors weigh the Vantage expansion and upcoming third quarter numbers.
Scan how Howard Hughes Holdings compares with other real estate driven opportunities by reviewing our hand picked list of solid balance sheet and fundamentals (24 results) that are also drawing investor attention around earnings season.
Howard Hughes Holdings now has a larger real estate operation and a new insurance platform, and the share price has started to move. The key question is whether that combination is already fully reflected in the US$79.06 share price.
Most Popular Narrative: 5.9% Undervalued
Against a last close of $79.06, the most followed valuation story for Howard Hughes Holdings points to a fair value of $84, which implies only a modest gap and emphasizes the long term shift toward insurance backed by real estate cash flows.
The pending acquisition and integration of a cash-generative insurance operation will diversify the earnings base, deploy excess capital into higher-yielding investments, and leverage Pershing Square's proven investment management expertise. Together, these factors are likely to significantly enhance long-term earnings power, return on equity, and share value compounding.
See why 22 investors see Howard Hughes Holdings as 6% undervalued.
Result: Fair Value of $84 (UNDERVALUED)
Still, Howard Hughes Holdings carries clear pressure points, including heavy debt refinancing needs and the execution risk tied to shifting capital toward insurance away from core real estate.
Find out about the key risks to this Howard Hughes Holdings narrative.
Another View On Howard Hughes Holdings
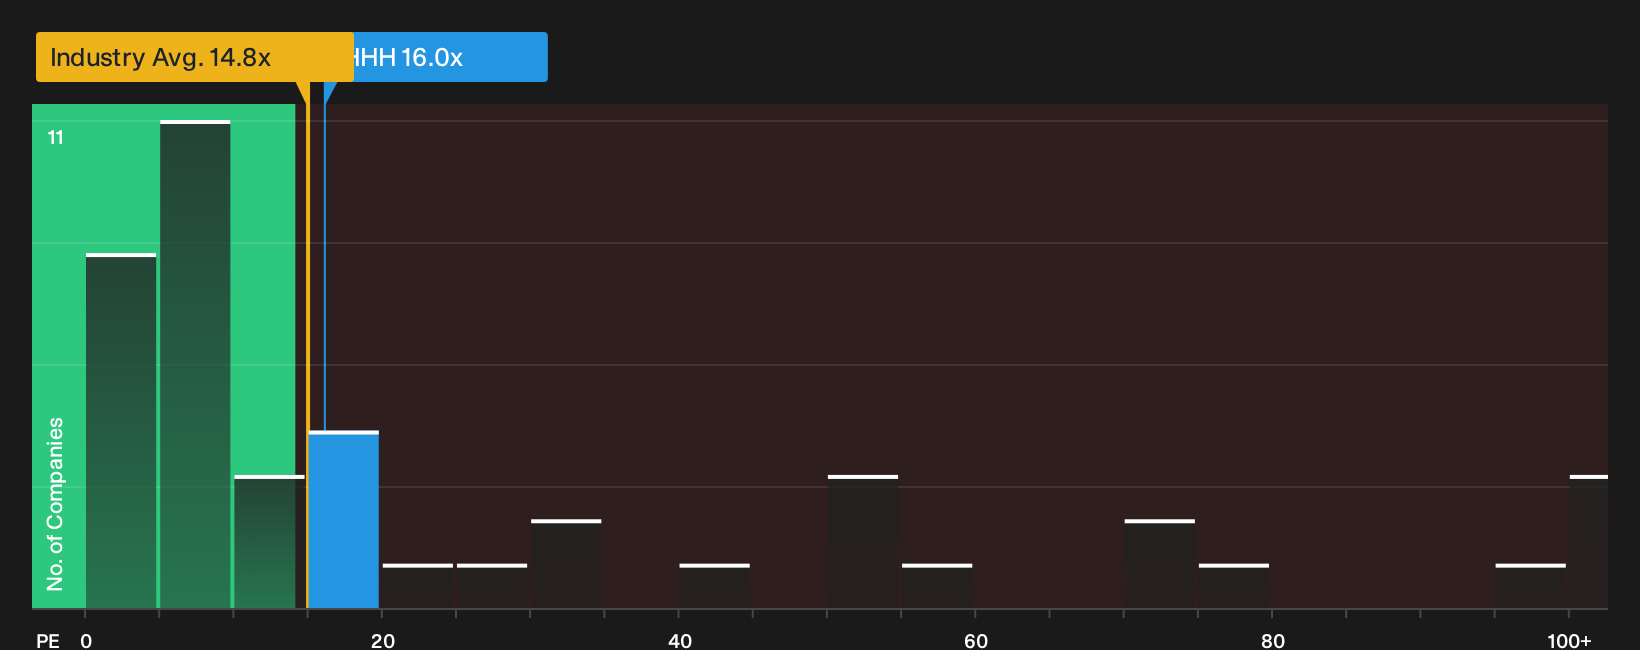
That 5.9% gap to the US$84 fair value is built off future earnings assumptions, yet on a simple P/E lens Howard Hughes Holdings looks less forgiving. The shares trade on roughly 16x earnings, above the US real estate average of 14.7x, while the fair ratio sits much higher at 26.8x. This mix of slight industry premium and a big gap to the fair ratio raises a simple question: Is the market underpricing the long term shift to insurance, or already asking you to pay up for it?
For a closer look at how this earnings multiple stacks up against both sector peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Howard Hughes Holdings so far. If you want to move quickly and form your own view from the underlying data, start with the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Howard Hughes Holdings?
If Howard Hughes Holdings has sharpened your focus, do not stop there. Broader ideas can help you stress test your thinking and spot opportunities sooner.
- Target potential mispricing by scanning a curated set of quality companies trading below assessed value with the 35 high quality undervalued stocks.
- Build a steadier income stream by reviewing a focused group of higher yielding payers through the 5 dividend fortresses.
- Protect your downside by filtering for robust balance sheets and solid fundamentals using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com