
Have J Sainsbury Insiders Been Selling Stock?
Some J Sainsbury plc (LON:SBRY) shareholders may be a little concerned to see that the CEO, Chairman of Operating Board & Director, Simon Roberts, recently sold a substantial UK£2.0m worth of stock at a price of UK£3.50 per share. That's a big disposal, and it decreased their holding size by 19%, which is notable but not too bad.
The Last 12 Months Of Insider Transactions At J Sainsbury
Notably, that recent sale by Simon Roberts is the biggest insider sale of J Sainsbury shares that we've seen in the last year. That means that an insider was selling shares at below the current price (UK£3.56). When an insider sells below the current price, it suggests that they considered that lower price to be fair. That makes us wonder what they think of the (higher) recent valuation. While insider selling is not a positive sign, we can't be sure if it does mean insiders think the shares are fully valued, so it's only a weak sign. It is worth noting that this sale was only 19% of Simon Roberts's holding.
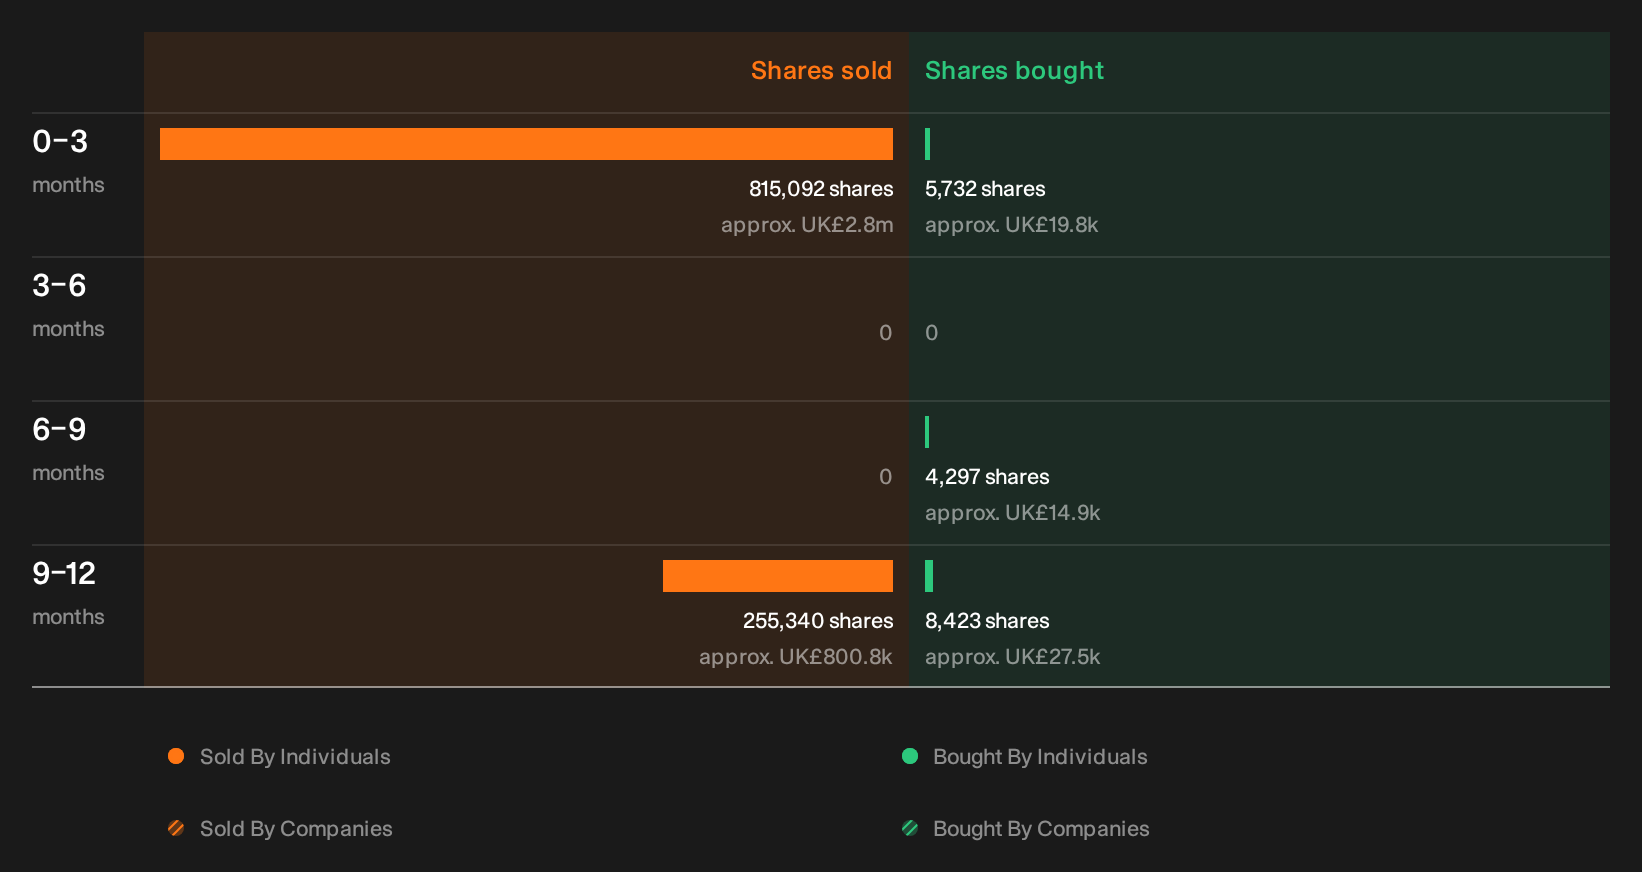
Over the last year we saw more insider selling of J Sainsbury shares, than buying. You can see the insider transactions (by companies and individuals) over the last year depicted in the chart below. If you click on the chart, you can see all the individual transactions, including the share price, individual, and the date!
See our latest analysis for J Sainsbury
I will like J Sainsbury better if I see some big insider buys. While we wait, check out this free list of undervalued and small cap stocks with considerable, recent, insider buying.
Insider Ownership Of J Sainsbury
Another way to test the alignment between the leaders of a company and other shareholders is to look at how many shares they own. Usually, the higher the insider ownership, the more likely it is that insiders will be incentivised to build the company for the long term. J Sainsbury insiders own about UK£13m worth of shares. That equates to 0.2% of the company. This level of insider ownership is good but just short of being particularly stand-out. It certainly does suggest a reasonable degree of alignment.
So What Does This Data Suggest About J Sainsbury Insiders?
The insider sales have outweighed the insider buying, at J Sainsbury, in the last three months. Zooming out, the longer term picture doesn't give us much comfort. On the plus side, J Sainsbury makes money, and is growing profits. Insiders own shares, but we're still pretty cautious, given the history of sales. So we'd only buy after careful consideration. While it's good to be aware of what's going on with the insider's ownership and transactions, we make sure to also consider what risks are facing a stock before making any investment decision. While conducting our analysis, we found that J Sainsbury has 2 warning signs and it would be unwise to ignore them.
If you would prefer to check out another company -- one with potentially superior financials -- then do not miss this free list of interesting companies, that have HIGH return on equity and low debt.
For the purposes of this article, insiders are those individuals who report their transactions to the relevant regulatory body. We currently account for open market transactions and private dispositions of direct interests only, but not derivative transactions or indirect interests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.