
Is Houlihan Lokey (HLI) Undervalued After Its Q3 Earnings Beat?
Houlihan Lokey (HLI) just cleared Wall Street’s bar for Q3 2026 revenue and profit, powered by richer fees on mid market deals and an improving restructuring pipeline, particularly among software clients.
Houlihan Lokey’s recent beat on expectations has arrived alongside a sharp swing in sentiment, with a 1 month share price return of 21.40% and a 3 month share price return of 20.76%, off a year to date share price decline of 12.63%. The 3 year total shareholder return of 57.16% contrasts with a 1 year total shareholder return that is down 12.62%.
Capitalize on Houlihan Lokey’s earnings momentum and rebuilding deal pipeline by scanning a hand picked set of advisers with similar profiles through the 19 high quality undiscovered gems.The question now is simple. After Houlihan Lokey’s sharp rebound and modest discount to analyst targets, does the current valuation still leave enough upside to justify new risk?
Most Popular Narrative: 3.7% Undervalued
On the most followed view of Houlihan Lokey, a fair value of $160.00 sits modestly above the last close at $154.06, which puts the recent rally against a still slightly discounted narrative.
The current numbers and valuation imply the market is not fully pricing in Houlihan Lokey’s record FY26 revenue of US$2.6b, 20% adjusted EPS growth to US$7.56, sustained 61.5% compensation ratio, leading M&A and restructuring deal counts, and expanding private capital and secondaries advisory franchise, so the stock appears undervalued.
See why 8 investors see Houlihan Lokey as 4% undervalued.
Result: Fair Value of $160.00 (UNDERVALUED)
Still, Houlihan Lokey’s story can wobble if muted sponsor activity persists, or if rising non compensation costs outpace advisory fee growth and squeeze profitability.
Find out about the key risks to this Houlihan Lokey narrative.
Another View: Houlihan Lokey Through the Earnings Multiple Lens
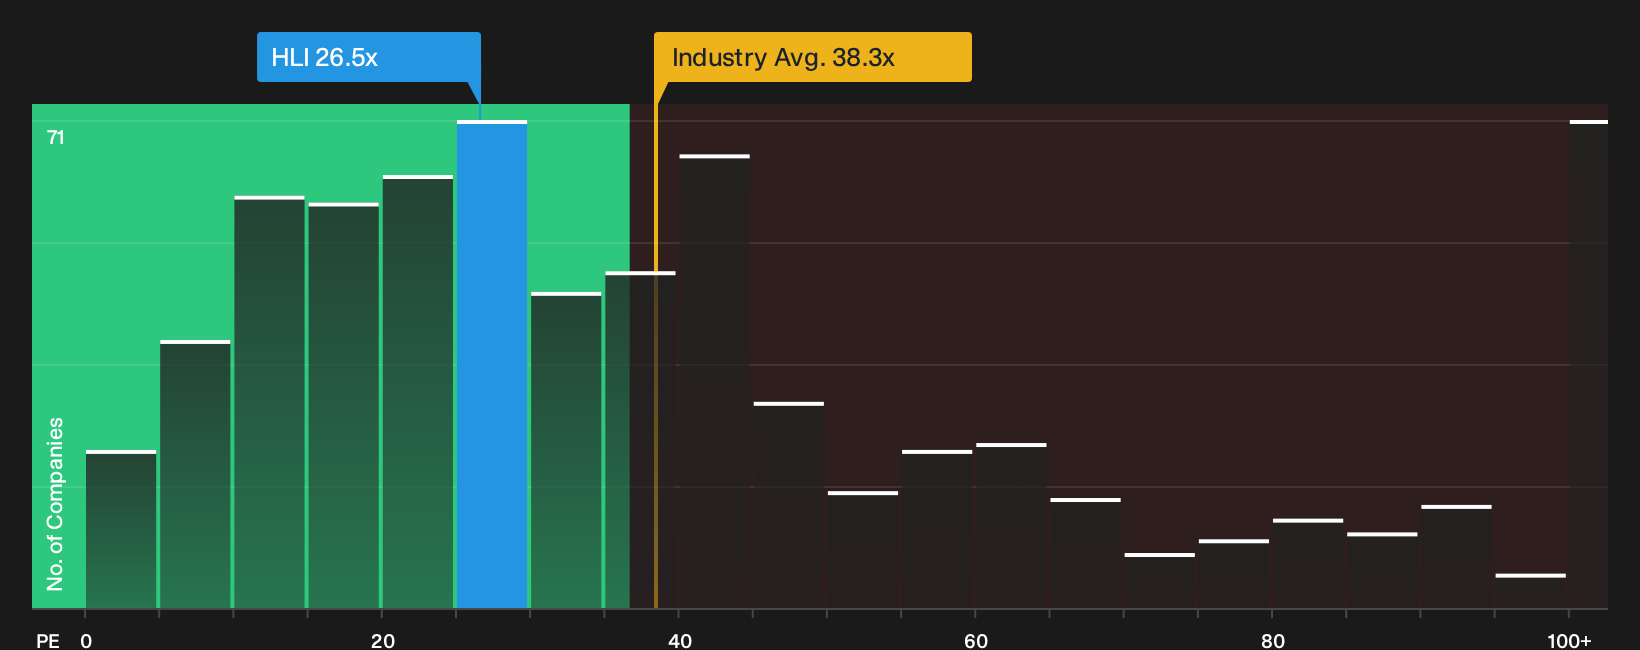
The earlier narrative focuses on fair value and cash flow, yet the earnings multiple paints a tougher picture. Houlihan Lokey trades on a P/E of 26.5x while the fair ratio is 14x. That is a wide gap for a stock that is forecast to grow earnings and revenue slower than the broader US market.
Against the US Capital Markets industry average P/E of 37.1x, Houlihan Lokey appears cheaper. Compared with a peer average of 10.6x, it screens as expensive. For anyone weighing this, the key question is simple: Does the quality of the franchise justify paying well above both the peer group and the fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Houlihan Lokey is clearly split, so treat this as your cue to move early, review the numbers and stress test the narrative yourself. To understand what the market is optimistic about right now, start with the 3 key rewards.
Looking for more Houlihan Lokey style ideas?
If you stop at Houlihan Lokey, you risk missing other setups that fit your approach just as well or even line up more cleanly.
- Target resilient upside by scanning a 31 resilient stocks with low risk scores that filters for durability when markets get choppy.
- Zero in on value by using the 34 high quality undervalued stocks to surface stocks where price and fundamentals look out of sync.
- Prioritise quality foundations with the list of solid balance sheet and fundamentals (24 results) to find businesses built to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com