
Did Nine Month Earnings Growth Just Shift Prosegur's (BME:PSG) Investment Narrative?
- Prosegur Compañía de Seguridad reported results for the nine months to 30 September 2026, with sales of €3,946.2 million and net income of €86.6 million, compared with €3,672.2 million and €82 million a year earlier, and basic EPS from continuing operations stable at €0.20.
- The combination of higher sales and a larger profit pool, alongside unchanged EPS, points to the importance of share count, mix, and capital allocation choices for Prosegur Compañía de Seguridad.
- We will now look at how Prosegur Compañía de Seguridad's investment narrative is affected by this higher nine month sales performance.
Scan beyond Prosegur Compañía de Seguridad and explore other cash generative operators with resilient fundamentals in our curated list of solid balance sheet and fundamentals (198 results) to see how they compare.
Prosegur Compañía de Seguridad Investment Narrative Recap
To own Prosegur Compañía de Seguridad, you need to buy into a story where higher quality contracts, more technology heavy services and disciplined cash generation matter more than headline sales. The latest nine month figures show higher revenue and modestly higher net income, while EPS is unchanged. As a result, the near term focus still sits on cash conversion and debt service rather than headline growth.
The short term catalyst is execution on cost savings and mix improvement in Security, Cash and Alarms without eroding service quality. The biggest near term risk remains leverage and debt coverage. Based on these earnings, that risk profile looks broadly intact rather than fundamentally changed by this update.
The most relevant recent development is the same earnings release for the nine months to 30 September 2026, because it gives you fresh evidence on whether Prosegur Compañía de Seguridad is making progress where it matters. Sales reached €3,946.2 million, net income came in at €86.6 million and basic EPS from continuing operations stayed at €0.20.
For catalysts that lean on higher operating cash flow, margin repair and eventual deleveraging, this report sits somewhere in the middle. The business shows it can support a larger revenue base and maintain earnings. However, the flat per share result and the existing concern that debt is not well covered by operating cash flow keep balance sheet execution squarely in focus.
Prosegur Compañía de Seguridad's current analyst narrative points to forecast revenue of €5.6 billion and earnings of €172.7 million by 2029, which is built on annual revenue growth of 3.5% and an earnings increase of about €50 million from €122.3 million today.
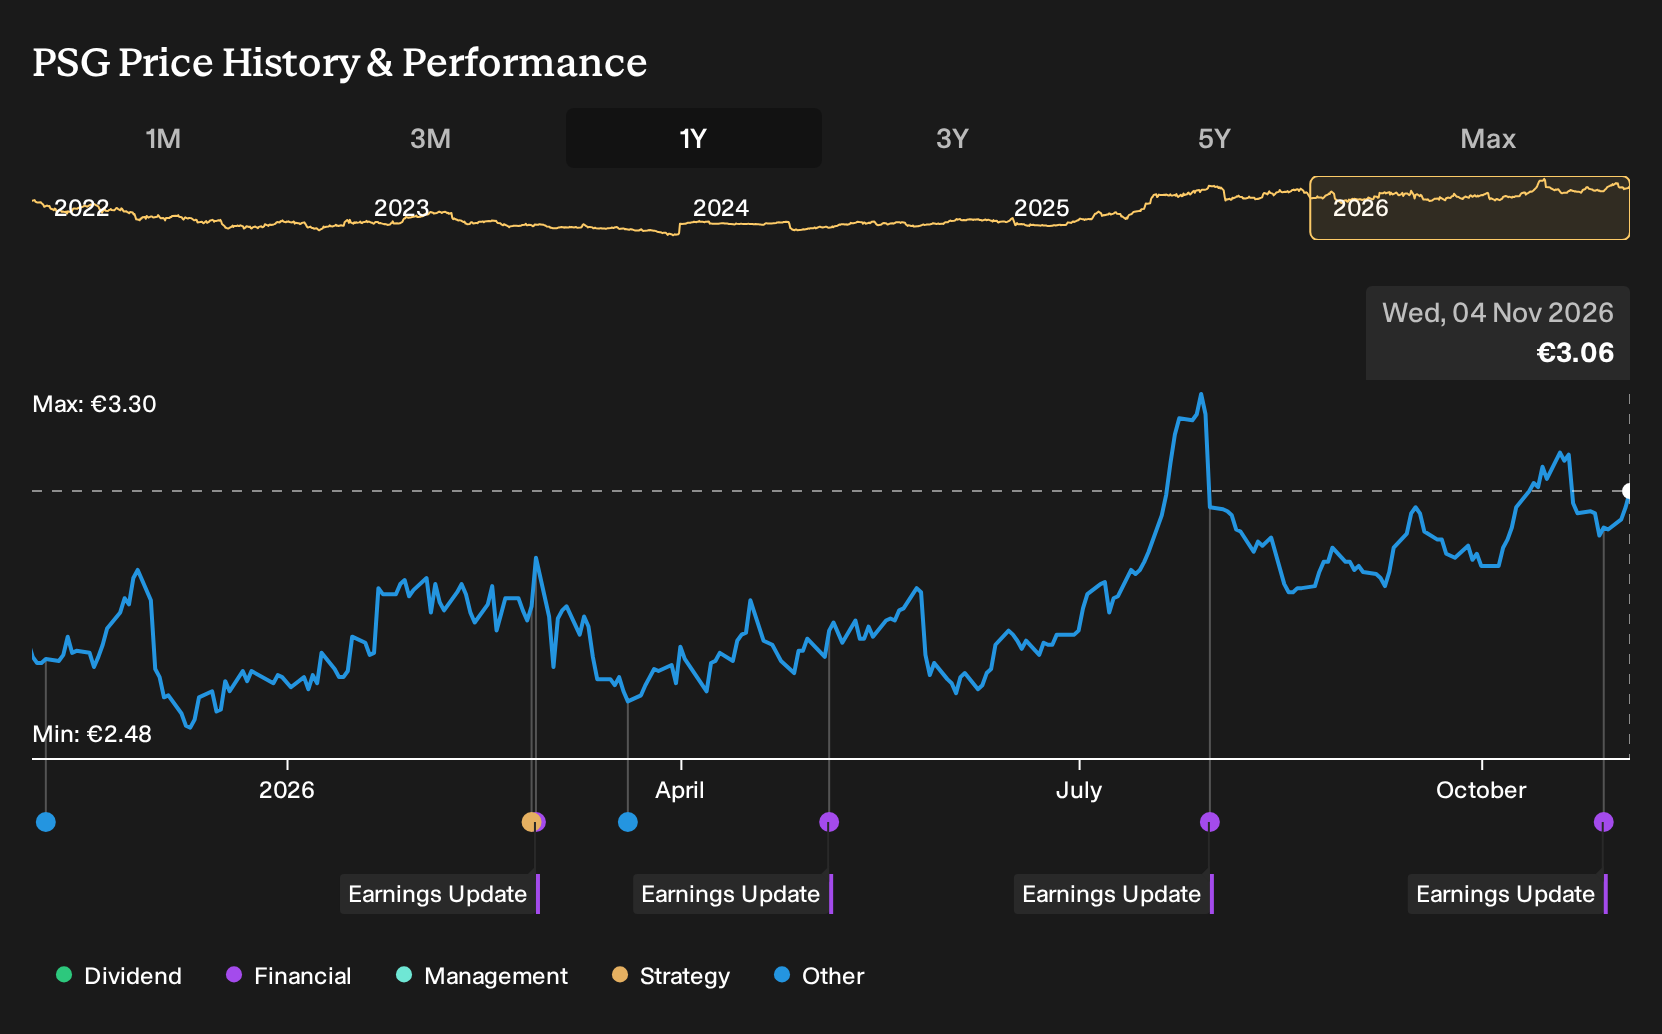
Uncover why Prosegur Compañía de Seguridad's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For Prosegur Compañía de Seguridad, the most bearish analysts focus on margin pressure. They were only pencilling in revenue of about €5.4b and earnings near €170.4 million by 2029 before this nine month update. That is more cautious than consensus, and this latest report could push those expectations in either direction once models adjust.
Explore 2 other Prosegur Compañía de Seguridad fair value estimates, including one that suggests it could be worth just €3.40.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Prosegur Compañía de Seguridad research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Prosegur Compañía de Seguridad. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prosegur Compañía de Seguridad's overall financial health at a glance.
Looking for more investment ideas beyond Prosegur Compañía de Seguridad?
If the Prosegur Compañía de Seguridad story has sharpened your focus on balance sheets, cash flow and risk, it can help to benchmark those priorities against a broader watchlist. The Simply Wall St Screener lets you filter for the traits that matter most to you, so you can line up Prosegur Compañía de Seguridad beside other businesses with similar characteristics and see what really earns a spot in your portfolio.
- For investors who want financial strength front and center, compare Prosegur Compañía de Seguridad with companies on our list of solid balance sheet and fundamentals (198 results) and see which ones best match your comfort with debt and liquidity.
- If your focus is on value and quality together, check out companies in the 194 high quality undervalued stocks so you can weigh Prosegur Compañía de Seguridad against other stocks that combine strong fundamentals with pricing that may look appealing.
- Income seekers can balance Prosegur Compañía de Seguridad's profile with potential payout candidates by scanning the 215 dividend fortresses and lining up yields, payout ratios and stability side by side.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com