
Capital Southwest (CSWC) Moved Higher, What Is The Market Seeing?
Capital Southwest (CSWC) just delivered its September quarter report, pairing higher revenue and record new investment commitments with lower net income per share and an expanded balance sheet funded by unsecured notes and fresh equity.
Capital Southwest’s latest earnings drop into a mixed price picture, with the share price advancing 6.73% year to date but easing over the past quarter as the 90 day share price return declined 3.88%, while the 1 year total shareholder return of 29.22% remains far stronger.
Scan how Capital Southwest stacks up against other income-focused lenders by comparing it with a curated 5 dividend fortresses that combines payout strength with balance sheet resilience.
Capital Southwest is rewarding patient holders, yet the latest quarter paired record commitments with diluted per share earnings. Do you focus on the current yield and entry point, or wait for a different price against the same fundamentals?
Most Popular Narrative: 6% Undervalued
On the most followed view, Capital Southwest screens as modestly undervalued, with a narrative fair value of $25.30 against the last close of $23.79. This indicates a small gap between the trading price and what the model suggests.
Expansion of low cost and flexible funding capacity, including an increased US$250 million SBA leverage commitment for SBIC II and a larger US$595 million corporate credit facility with a lower margin and longer maturity to 2031, gives Capital Southwest additional room to scale earning assets relative to its equity base and support net investment income.
See why 37 investors see Capital Southwest as 6% undervalued.
Result: Fair Value of $25.30 (UNDERVALUED)
Still, the Capital Southwest story can break if spread compression persists, or if heavier at-the-market issuance leaves per share earnings lagging headline growth.
Find out about the key risks to this Capital Southwest narrative.
Another View: Capital Southwest Through The P/E Lens
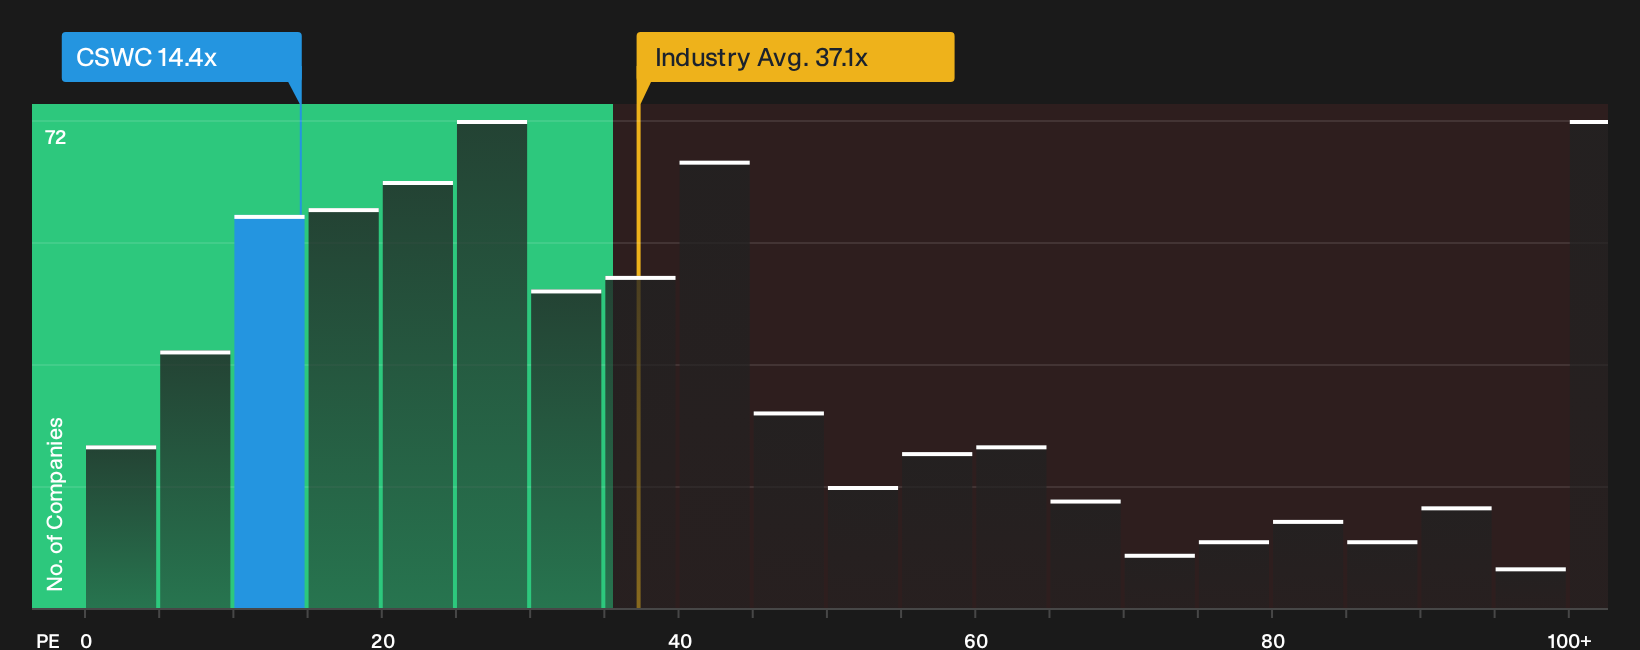
The narrative fair value presents Capital Southwest as modestly undervalued, yet the P/E check sends a different signal. The shares trade at 14.4x earnings, above a fair ratio of 13.8x and above a 13.2x peer average. This points to some valuation risk if sentiment cools.
That premium might reflect comfort with the internally managed model and earnings track record, or it could simply leave less room for error if credit costs or spreads move against the business. Which story do you think the market is really paying for today: the dividend and DCF upside, or the richer earnings multiple?
For a closer look at how the earnings multiple, peer comparison and fair ratio link back to valuation risk, See what the numbers say about this price — find out in our valuation breakdown..
Here is how the current valuation of Capital Southwest compares visually with the broader industry on this metric, which can help frame where the market might shift if expectations change,
Next Steps
Mixed signals on Capital Southwest’s valuation and risk profile only matter if you use them to sharpen your own judgement, so take a moment to weigh the upside and downside case together, then drill into the 3 key rewards and 3 important warning signs.
Looking for more Capital Southwest sized ideas?
Do not stop at Capital Southwest. Broaden your opportunity set with focused screeners that surface different types of stocks so you are not relying on one story.
- Target high quality value by reviewing a 34 high quality undervalued stocks that filters for strong fundamentals at prices that may offer a margin of safety.
- Prioritise resilience by scanning a list of solid balance sheet and fundamentals (25 results) that highlights companies with healthier leverage and liquidity profiles.
- Hunt for underfollowed potential through a 19 high quality undiscovered gems that surfaces lesser known businesses with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com