
Appian (APPN) After Defense Cloud Wins Is The Stock Already Fully Valued
Appian (APPN) is back in focus after Appian Defense Cloud secured Impact Level 5 Provisional Authorization to Operate, and the US Army rolled out a new munitions management platform on the same infrastructure.
These defense wins arrive after a sharp run in the Appian share price, with a 30-day share price return of 30.38% and a 90-day move of 63.83%. The 1-year total shareholder return of 69.86% suggests momentum has been strong over a longer stretch.
Scan how other AI and automation players are priced against their recent contract wins by running through the hand picked 41 profitable AI stocks that aren't just burning cash alongside Appian's latest defense moves.
The jump in Appian after these defense wins leaves a blunt question on the table: Is most of the upside already in the rearview mirror, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 43% Overvalued
Appian last closed at $49.82, while the most followed narrative pegs fair value at $34.80 using an 8.8% discount rate. That gap puts the recent defense-driven rally in the context of a framework that already sees expectations as stretched.
The current valuation implies that Appian is priced for stronger growth and quality of earnings than its mixed record on sales efficiency, cash generation, and bearish analyst ratings would suggest. This underpins this narrative’s view that the stock is overvalued and vulnerable.
See why 19 investors see Appian as 43% overvalued.
Result: Fair Value of $34.80 (OVERVALUED)
Still, two pressure points could flip the Appian story fast: if AI toolchains start to feel like substitutes for low code and if large regulated customers begin trimming workloads instead of expanding them.
Find out about the key risks to this Appian narrative.
Another View: Appian Through The SWS DCF Lens
Analyst targets point to Appian trading well ahead of a $34.80 fair value, yet the SWS DCF model lands in a very different place. On future cash flows, Appian at $49.82 screens about 9.9% below an estimated value of $55.29, which frames today’s price as a potential discount rather than excess. Which story do you trust more: the cash flow math or the cautious analyst crowd?
For a closer look at how those projected cash flows translate into a $55.29 estimate, run through the Look into how the SWS DCF model arrives at its fair value.
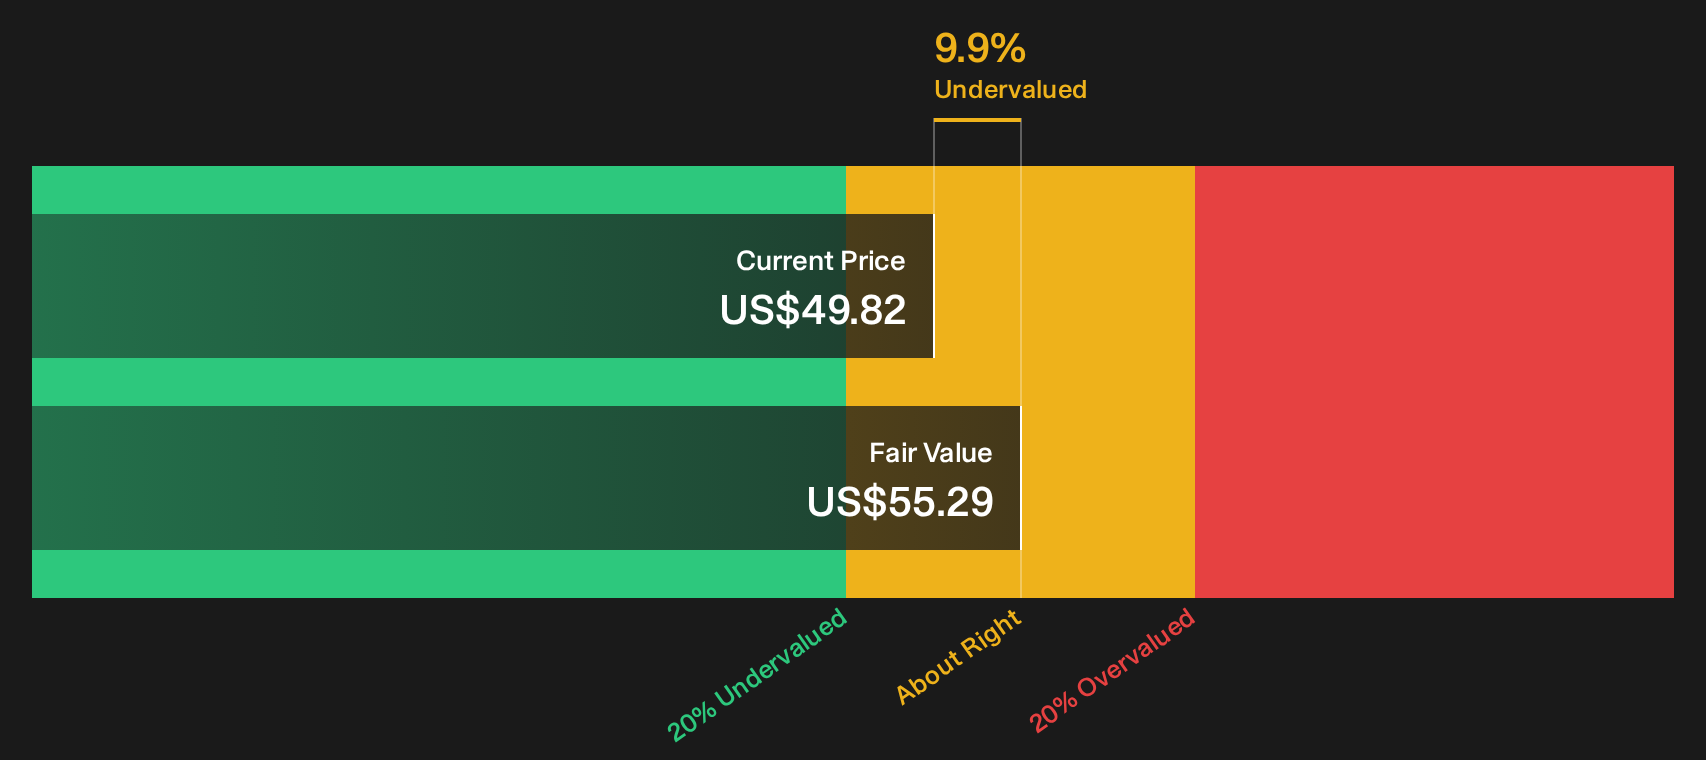
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Appian for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 34 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Appian is clearly split, with sharp recent gains now rubbing shoulders with both red flags and bright spots in the data. Move quickly, review the underlying metrics yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Appian?
If Appian's split valuation story has you thinking bigger, use this momentum to widen your watchlist with other opportunities that align with your approach.
- Target resilient growth potential by scanning a 19 high quality undiscovered gems that combines quality fundamentals with businesses the market may not be fully focused on yet.
- Prioritise downside protection and capital preservation by reviewing a 31 resilient stocks with low risk scores that highlights companies with sturdier profiles when conditions get choppy.
- Anchor your research around financial strength by checking a list of solid balance sheet and fundamentals (25 results) that filters for durable balance sheets and consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com