
Coty (COTY) Extends Marc Jacobs License, Is The Upside Already Priced In?
Coty (COTY) extended its long-term Marc Jacobs license with WHP Global and G-III Apparel Group, securing a key Prestige brand relationship that will shape future plans for Marc Jacobs Beauty across regions and product lines.
Coty’s recent moves around Marc Jacobs come after a sharp 30-day share price return of 27.57% and a 90-day share price return matching that at 27.57%, even as 1-year total shareholder return declined 8.2% and the 5-year total shareholder return fell 66.86%. This suggests that short-term momentum is building while longer-term holders still face a heavy drawdown.
Scan Coty’s momentum against a curated 19 high quality undiscovered gems in beauty and consumer brands that may not yet be on most investors’ radars.
Coty shares have sprinted ahead in the last quarter, yet long-term holders are still sitting on deep losses. Is most of the rerating already in the rear-view mirror, or does valuation still leave meaningful upside on the table?
Most Popular Narrative: 31% Overvalued
Coty closed at $3.47, while the most followed narrative pegs fair value at about $2.65, using a 10.05% discount rate and detailed earnings forecasts to get there.
The main thing that has to go right is that Coty turns its prestige and consumer beauty underperformance in sell out into at least category level growth, while cost savings programs, SKU reductions, and Gucci related restructuring protect margins and cash generation.
The current valuation and this narrative’s fairly valued, bullish stance together suggest that the share price already reflects both the delivery of ongoing cost and deleveraging targets, as well as the risk that sales and margin pressure, legal actions, and the Gucci license exit could affect future results.
See why 9 investors see Coty as 31% overvalued.
Result: Fair Value of $2.65 (OVERVALUED)
Still, Coty faces pressure from recent like for like sales declines and the Gucci Beauty license exit, which could unsettle the current fair value story.
Find out about the key risks to this Coty narrative.
Another View: What Coty’s Sales Multiple Is Saying
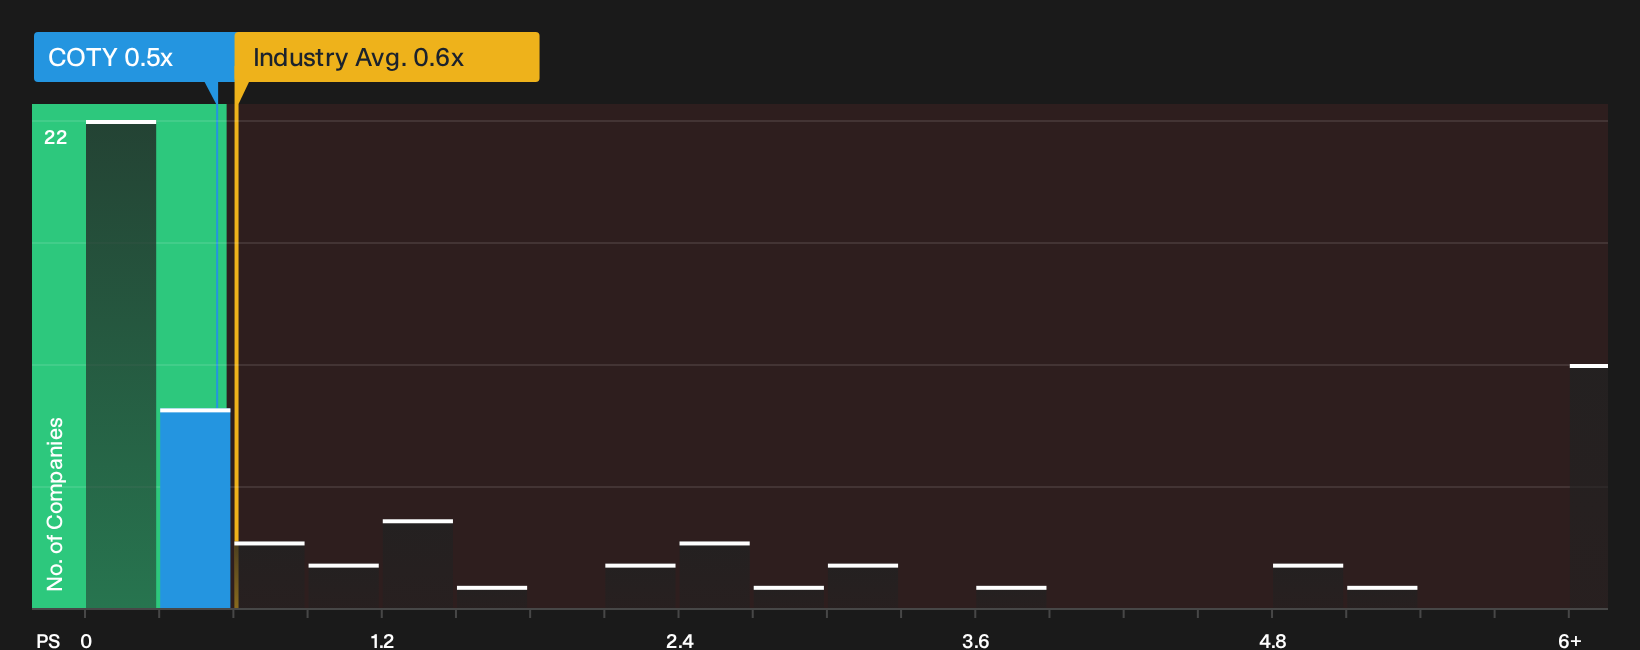
The narrative pegs Coty as about 31% overvalued on a fair value of $2.65, yet the P/S ratio tells a softer story. At 0.5x P/S, the stock trades below the US Personal Products industry at 0.6x, peers at 1x, and an estimated fair ratio of 0.9x.
That gap suggests the market already prices in execution risk, especially around weak profitability and the Gucci exit, rather than giving Coty the kind of premium its peers enjoy. The question is whether you see that discount as justified caution or a mispriced turnaround.
For a closer look at how the numbers line up against this valuation gap, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
All this debate around Coty’s valuation only matters if you pressure test the numbers yourself and decide where you land. To see how the potential upside case compares to the risks that have investors optimistic, review the 2 key rewards.
Looking for more Coty-sized investment ideas?
If Coty has you rethinking where the real opportunities might sit, use this moment to widen your search before the next move passes you by.
- Target potential value gaps across the market by scanning a 34 high quality undervalued stocks that filters for quality first, not hype.
- Prioritize resilience and capital preservation by reviewing a 31 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier business profiles.
- Spot companies with cleaner finances by working through a list of solid balance sheet and fundamentals (25 results) that highlights stronger fundamentals when conditions get tougher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com