
Will Cybersecurity Leadership Hire Change Insight Enterprises Stock Narrative
- Insight Enterprises recently appointed Valerie Abend as senior vice president of its global cybersecurity practice, tasking her with unifying security capabilities across the business and advising clients on complex risk challenges.
- Abend’s mix of FS-ISAC leadership, Accenture practice building, and U.S. financial-system cybersecurity policy experience points to a push for deeper, higher-value security services rather than just reselling tools.
- The next area of focus is how Insight Enterprises’ investment narrative around AI, cloud, and security services could be reshaped by Abend’s cybersecurity mandate.
Insight Enterprises Investment Narrative Recap
For a shareholder in Insight Enterprises, the core belief is that the business can keep shifting from lower margin reselling into higher value cloud, AI and security services while holding on to its recent efficiency gains. The key near term swing factor remains client appetite for IT and services spending, because sales have been relatively flat even as earnings improved.
Valerie Abend’s arrival looks additive to that story rather than a wholesale change. Her remit aligns directly with the push into managed security and AI driven services. However, the biggest current risk still sits with vendor program changes and client spending delays. If those pressures persist, higher margin security work may simply offset, rather than lift, overall performance.
The most relevant prior move for this appointment is Insight Managed Exposure Defense, which is built around AI driven managed security services. Abend’s background at FS ISAC and in financial system policy lines up with the kind of complex, regulated clients that offering targets. In those environments, ongoing monitoring, reporting and advisory work can turn into repeat revenue.
For you as an investor, the link between that product and this hire sits in execution. The opportunity is to deepen recurring cybersecurity income and support the One Insight operating model, which already leans on AI productivity. The risk is that integration across regions and vendor ecosystems proves slow, which would leave Insight Enterprises carrying higher leadership cost without the intended scale benefits.
What The Current Analyst Setup Implies For Insight Enterprises
Insight Enterprises' narrative projects US$9.9b revenue and US$392.5m earnings by 2029. That outlook assumes revenue expands at about 4.9% per year and earnings rise by roughly US$182m from US$210.5m today.
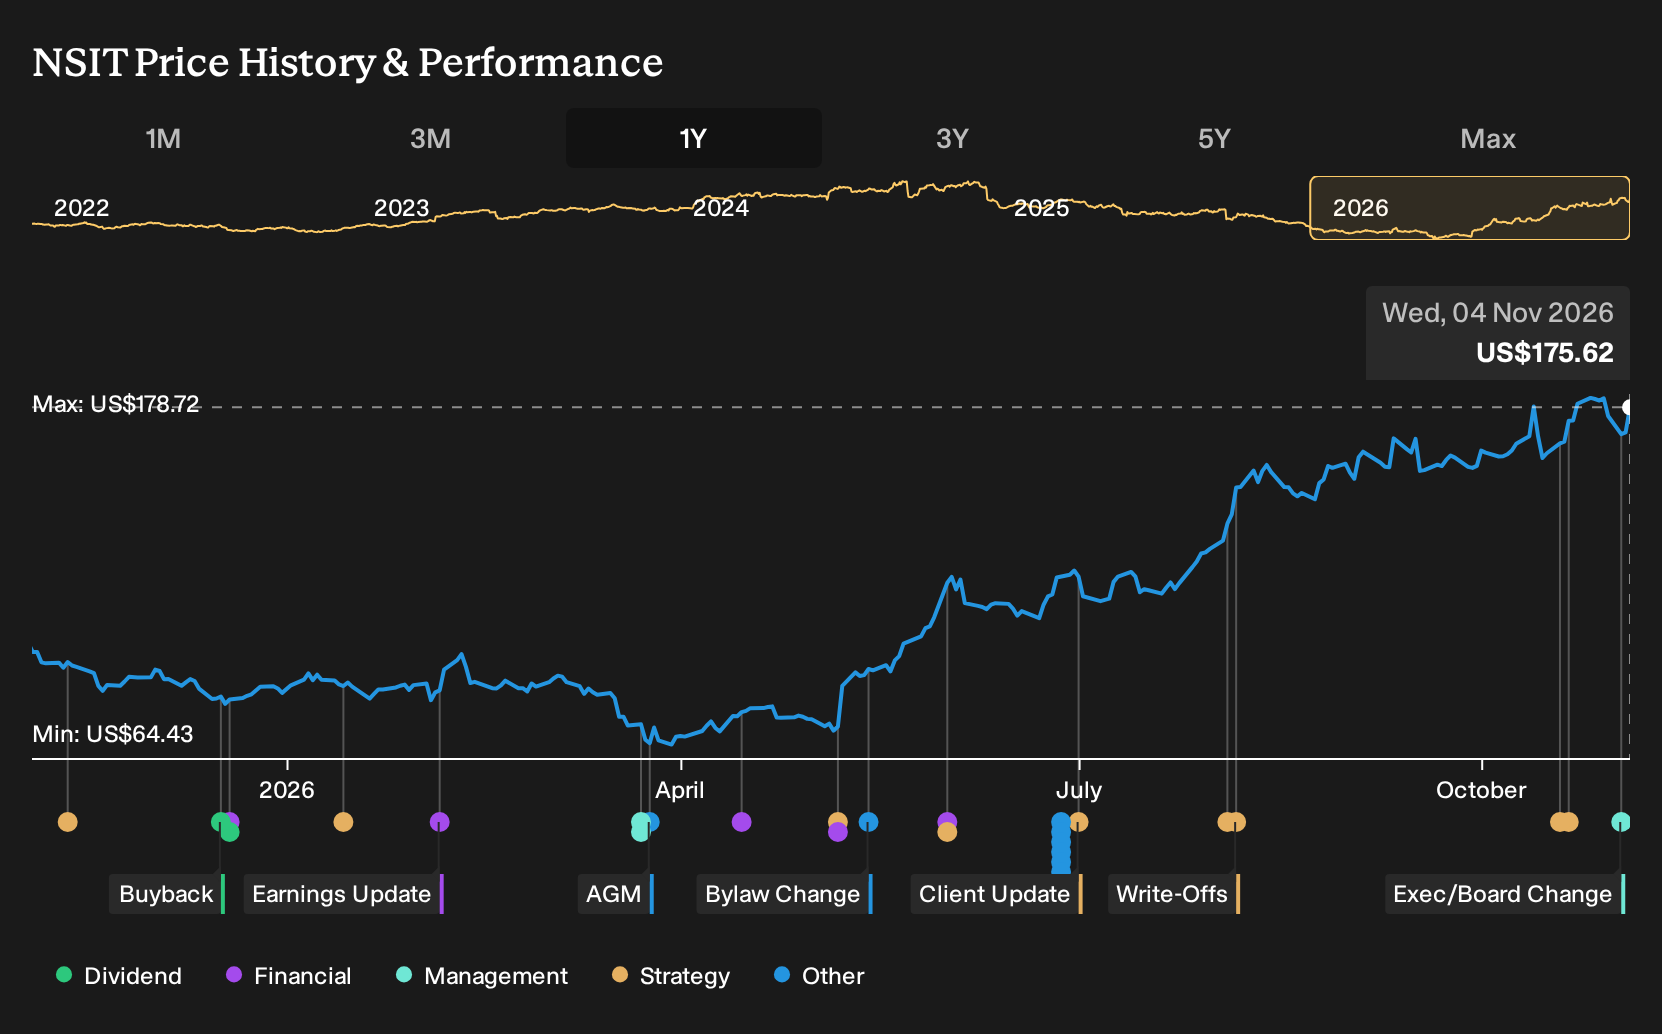
Uncover how Insight Enterprises' fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
One bullish twist you may want to explore is how the most optimistic analysts, who were pencilling in US$10.1b of revenue and US$422.0m of earnings by 2029, already saw Insight Enterprises as underappreciated. That view leans heavily on faster cybersecurity and AI services traction. Abend’s appointment could either reinforce or reshape that view in analysts’ next round of models.
Explore 4 other Insight Enterprises fair value estimates, including one that suggests it could be worth as much as $180.00.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Insight Enterprises research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Insight Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insight Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond Insight Enterprises?
Once you have a view on Insight Enterprises, it can help to widen the lens and compare it with other stocks that fit clear risk, quality, or income profiles. The Simply Wall St Screener provides quick ways to surface focused shortlists so you can spend more time judging business quality and less time trawling tickers.
- For investors who care most about durable balance sheets and staying power, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching their finances.
- If the priority is finding opportunities that trade below what their fundamentals might justify, scan a 34 high quality undervalued stocks that combines healthier cash flows with sturdier financial positions.
- Income focused portfolios can benefit from a stream of higher yields, so consider a 5 dividend fortresses that emphasises stability alongside payout strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com