
Old Dominion Freight Line (ODFL) Beat Expectations, Is The Upside Already Priced In?
Old Dominion Freight Line (ODFL) just paired an earnings beat with fresh guidance that points to fourth quarter revenue of US$1.54b to US$1.58b, which management expects to run above normal seasonality.
Those guidance comments land after a choppy year for Old Dominion Freight Line’s stock, with the share price gaining 3.5% over the past week but still down about 15% over the last three months, even as the 1 year total shareholder return sits at 28.22%. This suggests that investors are reassessing both growth potential and risk after a strong run.
Compare Old Dominion Freight Line’s guidance-driven momentum with other transport and logistics operators by scanning our hand picked list of solid balance sheet and fundamentals (25 results) for potential alternatives or complements in your portfolio.
Old Dominion Freight Line now trades about 16% below the average analyst price target, even though its own fair value estimate signals a 10% premium. Is the market’s caution mispricing recent momentum, or is it flagging real risks?
Most Popular Narrative: 16% Undervalued
Old Dominion Freight Line last closed at $179.39, while the most followed narrative pegs fair value near $214.76. This leaves a sizable valuation gap that rests on execution, pricing discipline and capital investment paying off over time.
Old Dominion Freight Line is focused on maximizing operating efficiencies and reducing discretionary spending to protect their operating ratio, and the company now reports a 450 basis point improvement to a 70.1% operating ratio in Q2 2026 with direct operating costs 200 to 250 basis points better than a prior record quarter. This could support further gains in net margins as more revenue flows through to earnings.
See why 31 investors see Old Dominion Freight Line as 16% undervalued.
Result: Fair Value of $214.76 (UNDERVALUED)
Still, the narrative around Old Dominion Freight Line can break if weaker freight demand keeps shipment volumes soft or if higher diesel and capital costs squeeze margins.
Find out about the key risks to this Old Dominion Freight Line narrative.
Another View: Old Dominion Freight Line On Earnings Multiples
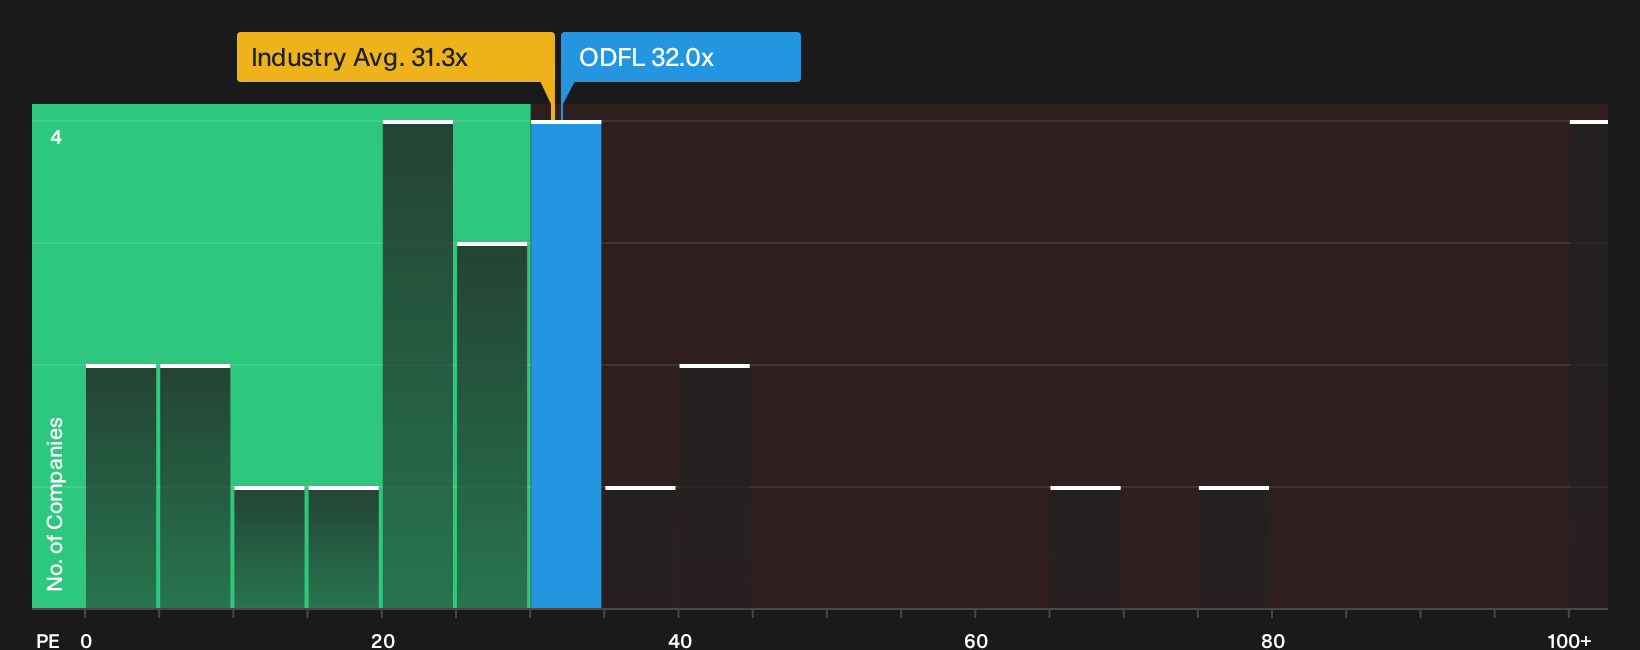
The narrative pegs Old Dominion Freight Line as about 16% undervalued relative to fair value. The earnings multiple tells a different story. ODFL trades on a P/E of 32x, compared with 31.3x for the US Transportation industry and peers, while the fair ratio sits closer to 19.4x.
That gap means investors are already paying a marked premium versus both the sector and the fair ratio that the market could move toward over time. For anyone weighing fresh capital, the question is simple: is the quality premium enough to justify that valuation risk if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Old Dominion Freight Line is clearly split, with both concerns and upside on the table, so move quickly and pressure test the data yourself. To weigh those cross currents directly, start with the balance between 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Old Dominion Freight Line?
If you only stop at Old Dominion Freight Line, you risk missing other opportunities that might suit your goals even better right now.
- Target potential bargains early by scanning a curated 19 high quality undiscovered gems that focuses on quality businesses with strong underlying fundamentals.
- Prioritise stability first and use the 31 resilient stocks with low risk scores to see companies that score well on resilience and overall risk profiles.
- Stack your portfolio with robust cash generators by reviewing our 5 dividend fortresses that screens for higher yielding payouts backed by solid metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com