
Missed DHL's Run? What Holders Had To Believe
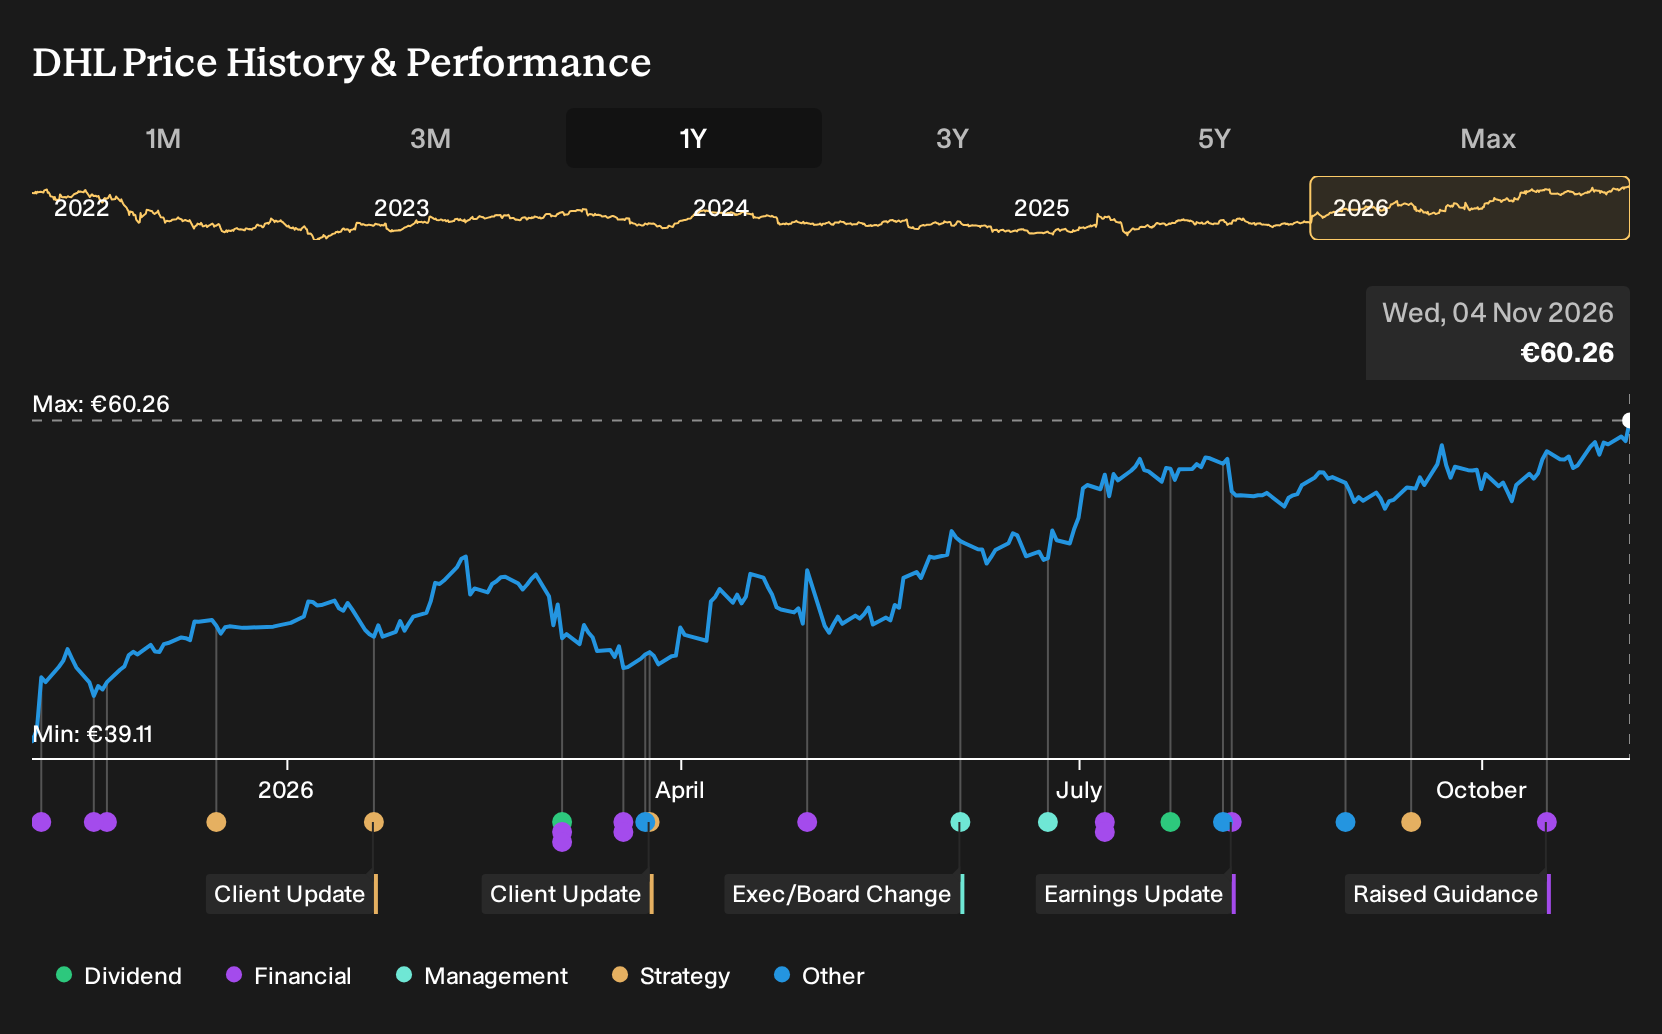
DHL eCommerce signing a multi year last mile delivery deal with USPS worth over €10b put a single contract at the center of the story. For DHL shareholders, the return over the past year was 57.6%, including dividends. If you had been weighing a purchase before November 2025, you had to decide whether investments in e commerce flows, automation, and express air capacity really justified betting on that kind of outcome.
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
DHL is not the only name tied to this theme. Zero in on 34 elite gold producer stocks and compare how each one is priced.
The Argument You Would Have Been Weighing On DHL
The shares cost €39.11 at the start of the period, and anyone looking at Deutsche Post DHL then had to choose between two very different stories about where value might sit.
On the optimistic side, the bullish Narrative put Fair Value at €42.82 and relied on e commerce, automation, and premium express services supporting assumed revenue growth of 2.7% and a 4.7% profit margin over three years.
The more cautious view framed Fair Value at €34 and focused on trade disputes and regulatory shifts, with risks tied to declining international shipment volumes and rising sustainability costs squeezing profitability.
What The Results Changed For The DHL Argument
The DHL eCommerce deal with USPS gave the optimistic case concrete support, and Q2 2026 did more of the talking. Revenue moved from €19,826m to €22,367m and net income rose from €815m to €1,010m, with net margin edging from 4.1% to 4.5%. That combination of higher sales and fatter profitability backed the bullish story more than the cautious one.
The lesson is simple. When a thesis leans on better margins, you track the reported net margin first and treat every upbeat contract headline as secondary until that figure actually shifts.
What DHL's Run Leaves You Paying For Now
DHL now trades at €60.26, after a 57.6% gain over the past year. The selected Narrative argues that its Fair Value sits below that price, largely because it treats today’s profit levels and cash returns as already baking in a lot of execution success.
The core bet at this level is that DHL keeps Express EBIT margins and cash generation near current guidance. The question the selected Narrative presses is how mix, automation progress and newer trade corridors affect the odds that this margin quality actually holds.
"The main thing that has to go right is that DHL successfully converts its smart industrial growth strategy, Heavyweight Express focus, cost reset programs and AI driven efficiency into durable profit without slipping back into low margin B2C volumes. The current numbers and guidance, including Express EBIT margins in the mid teens and an enlarged share buyback program, suggest that DHL’s share price already reflects successful execution of these profit and cash flow ambitions."
One Narrative disagrees with today's price. → See where this Narrative says DHL should trade
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 30% below our estimate - refocuses its lending mix toward secured mortgages and conservative gold collateral.
- Company 2 - 21% below our estimate - structures healthcare outsourcing contracts that bundle AI tools into managed services.
- Company 3 - 25% below our estimate - integrates AI assistants into productivity, coding and enterprise workflows on its platform.
Those are three of them. See every one of the 194 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com