
Earnings Beat Could Reshape The Case For Kosmos Energy Stock
- Kosmos Energy reported third quarter 2026 revenue of US$409.88 million and a net loss of US$43.01 million, with production averaging about 69,200 boepd and guidance for fourth quarter volumes of 60,000 to 64,000 boe per day.
- The business combined higher reported revenue with a reduced loss, continued cost and debt reduction efforts, and a major extension and resizing of its commercial debt facility. The changes to the facility push principal payments out to 2029 and add new liquidity requirements.
- We will examine how Kosmos Energy's reduced quarterly loss and operational progress relate to the existing investment narrative around LNG growth.
Scan beyond Kosmos Energy and compare this earnings story with other hand-picked oil and gas operators using the list of solid balance sheet and fundamentals (25 results) to evaluate potential balance sheet resilience and operational discipline.
Kosmos Energy Investment Narrative Recap
Kosmos Energy still hinges on one big idea. You need to believe the portfolio shift toward LNG at GTA and higher margin Ghana production can eventually outweigh current losses and heavy funding needs. The latest quarter showed higher revenue and a smaller net loss, so the recent results broadly support that operational story rather than change it.
The near term swing factor stays the same: execution at core projects and delivery against fourth quarter production guidance of 60,000 to 64,000 boe per day. The main risk remains leverage and the possibility that cash flow keeps getting absorbed by interest and repayments instead of reinvestment or shareholder friendly uses.
The amended and restated commercial debt facility is the most important announcement alongside the earnings release. Maturity is pushed out to April 1, 2033, principal repayments start in late 2029, and the facility is resized to US$1.2b with scope to increase commitments to US$1.75b subject to conditions.
For you, this reframes timing rather than existence of the leverage issue. Kosmos Energy gains more runway to fund GTA, Ghana and Gulf of Mexico projects, but accepts a 4.5% margin that steps up later plus a US$200 million minimum liquidity covenant. Execution now needs to justify that extended debt structure and keep derivative, project and cost risks contained.
What The Analyst Consensus Implies For Kosmos Energy
Kosmos Energy's narrative projects US$1.5b revenue and US$46.0 million earnings by 2029. That setup assumes revenue declines at about 1.8% per year and earnings rise by roughly US$588 million from current earnings of a US$542.2 million loss.
Uncover why Kosmos Energy's fair value indicates a 33% potential upside to its current price, a valuation gap that could narrow quickly if sentiment shifts.
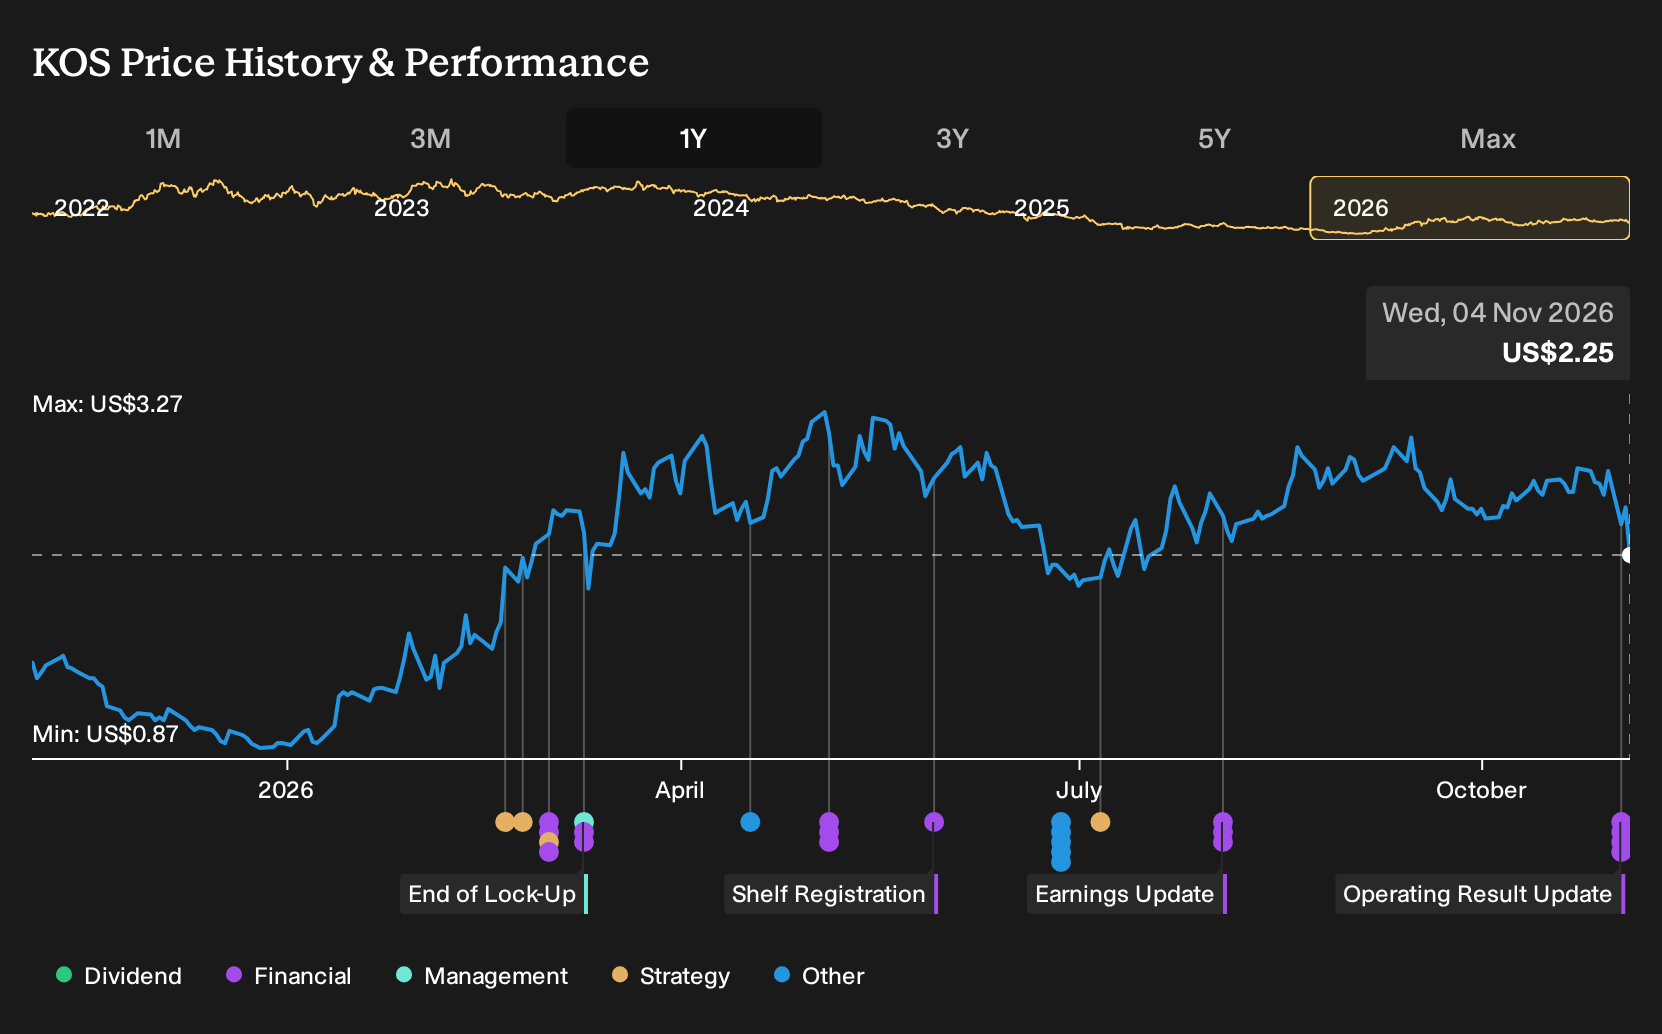
Exploring Other Perspectives
Some of the most optimistic analysts focus on Kosmos Energy’s LNG and Jubilee production as a potential upside swing factor. Before this earnings release, they were modeling revenue of about US$1.7b and earnings near US$481.3 million by 2029. You can treat this quarter’s higher revenue and smaller loss as a fresh data point that might influence those upbeat forecasts, then compare that with more cautious views to see where you sit.
Explore 4 other Kosmos Energy fair value estimates, including one that suggests as much as 685% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kosmos Energy research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kosmos Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kosmos Energy's overall financial health at a glance.
Looking For More Ideas Beyond Kosmos Energy?
If Kosmos Energy has sharpened your focus on balance sheets, cash generation and future earnings potential, it can help to put those themes in context by reviewing a wider watchlist. Use the Simply Wall St Screener to compare similar stories and uncover a mix of quality, income and resilience that fits your own approach.
- If you want potential value coupled with quality fundamentals, scan through a curated 34 high quality undervalued stocks that already clear strict financial and balance sheet checks.
- If income is a priority for you, focus on companies in the 5 dividend fortresses and see which high yield payouts look more sustainable on closer inspection.
- If capital preservation and steady profiles matter most, concentrate on businesses in the 31 resilient stocks with low risk scores that combine resilient balance sheets with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com