
High Utilization Keeps Archrock Stock In Focus After Strong Quarter
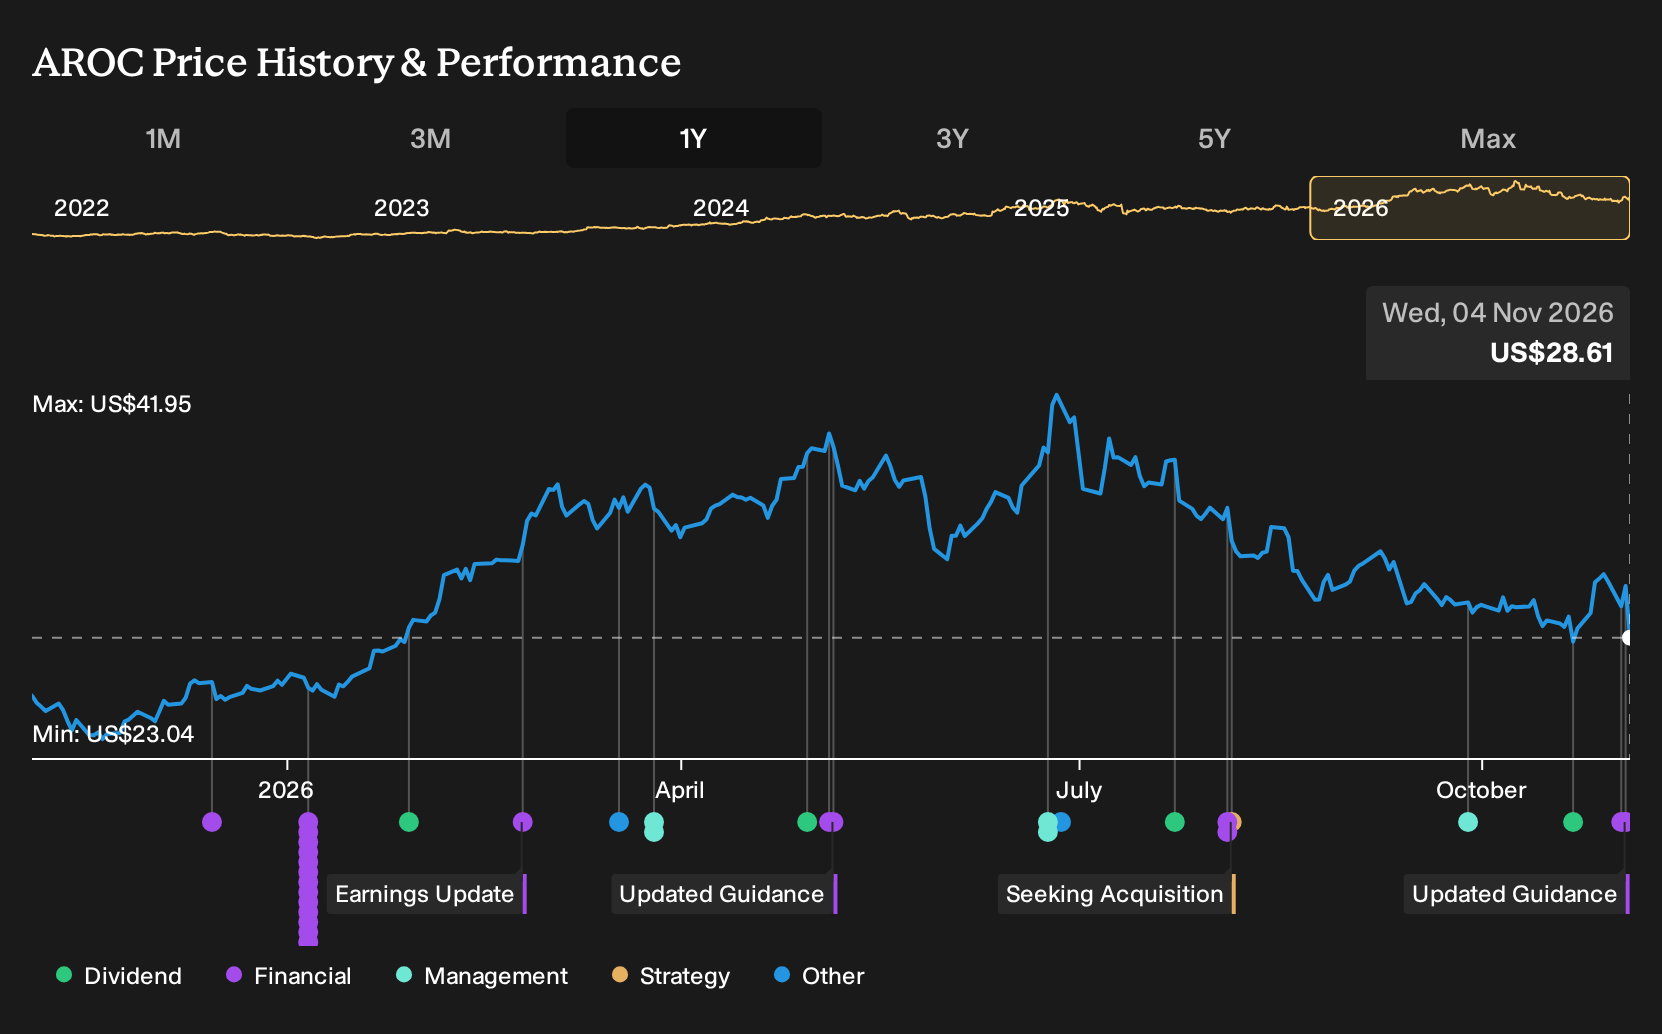
- Archrock reported third quarter 2026 results with US$370.81 million in revenue, US$84.47 million in net income and US$0.48 in diluted EPS from continuing operations, and issued full year 2026 net income guidance of US$290.75 million to US$310.75 million.
- The business kept contract operations utilization above 94% while planning US$1.4 billion to US$1.6 billion of growth investments through 2030, indicating that current fleet demand is influencing how Archrock allocates capital and manages future compression capacity.
- This article will examine how Archrock's investment narrative is affected by utilization above 94% alongside reaffirmed 2026 earnings guidance.
Compare Archrock’s utilization and earnings guidance with other contract-heavy energy plays by scanning our curated list of 41 power grid technology and infrastructure stocks that are also investing heavily in future capacity.
Archrock Investment Narrative Recap
To own Archrock, you need to be on board with a compression business that is heavily tied to contracted natural gas demand and long term fleet deployment. The big near term swing factor is whether utilization above 94% converts into sustained pricing and margins as more horsepower is added. The reaffirmed 2026 net income range suggests the latest quarter does not materially change that near term earnings catalyst.
The main operational headache remains cost pressure and the weakness in Aftermarket Services as customers defer maintenance. If higher lube oil, make ready work and softer services revenue persist, they could offset some benefit from tight compression supply. That is the key risk to watch around Archrock right now.
The fresh full year 2026 net income guidance of US$290.75 million to US$310.75 million is the announcement that really matters here. It ties directly to how investors think about Archrock’s ability to turn high utilization and a tight large engine market into actual earnings, not just contracted horsepower and long dated capex plans.
With that range now on the table, alongside plans for US$1.4b to US$1.6b of growth investments through 2030, you can better judge execution risk. The guidance frames how much room there is for cost creep or further softness in Aftermarket Services before it starts to affect the story built around LNG driven demand and long duration compression contracts.
Archrock's current analyst narrative focuses on revenue rising to US$1.8b and earnings reaching US$430.0 million by 2029, based on a 6.4% yearly revenue growth rate and an improvement in profit margins that takes earnings up from US$324.9 million today to that US$430.0 million consensus level over the same period.
Uncover why Archrock's fair value indicates a 49% potential upside to its current price, a discount that could close sooner than expected.
Exploring Other Perspectives
Fair value estimates for Archrock from four members of the Simply Wall St Community range from about US$26.31 to US$44.88, which leaves plenty of room for disagreement on upside. When this is set against guidance for 2026 net income and ongoing cost pressure, it serves as a reminder that opinions can diverge sharply. Consider exploring several viewpoints before deciding how Archrock fits your portfolio.
Explore 3 other Archrock fair value estimates, including one that suggests as much as 8% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own analysis and judgment.
- A great starting point for your Archrock research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Archrock. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Archrock's overall financial health at a glance.
Looking For More Ideas Beyond Archrock?
If Archrock is only one piece of how you want to build exposure, it can help to line it up against other opportunities with different risk, income and balance sheet profiles. The Simply Wall St Screener lets you do exactly that in a structured way rather than relying on a handful of familiar tickers.
- If capital preservation ranks high for you, focus on companies with steadier profiles by reviewing a curated group of 31 resilient stocks with low risk scores that score well on resilience.
- If income is your priority, broaden your watchlist with 5 dividend fortresses that combine higher yields with an emphasis on sustaining payouts.
- If you want to surface less crowded opportunities, scan a focused pool of 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com