
i-80 Gold Stock Sales Rise As Quarterly Loss Widens
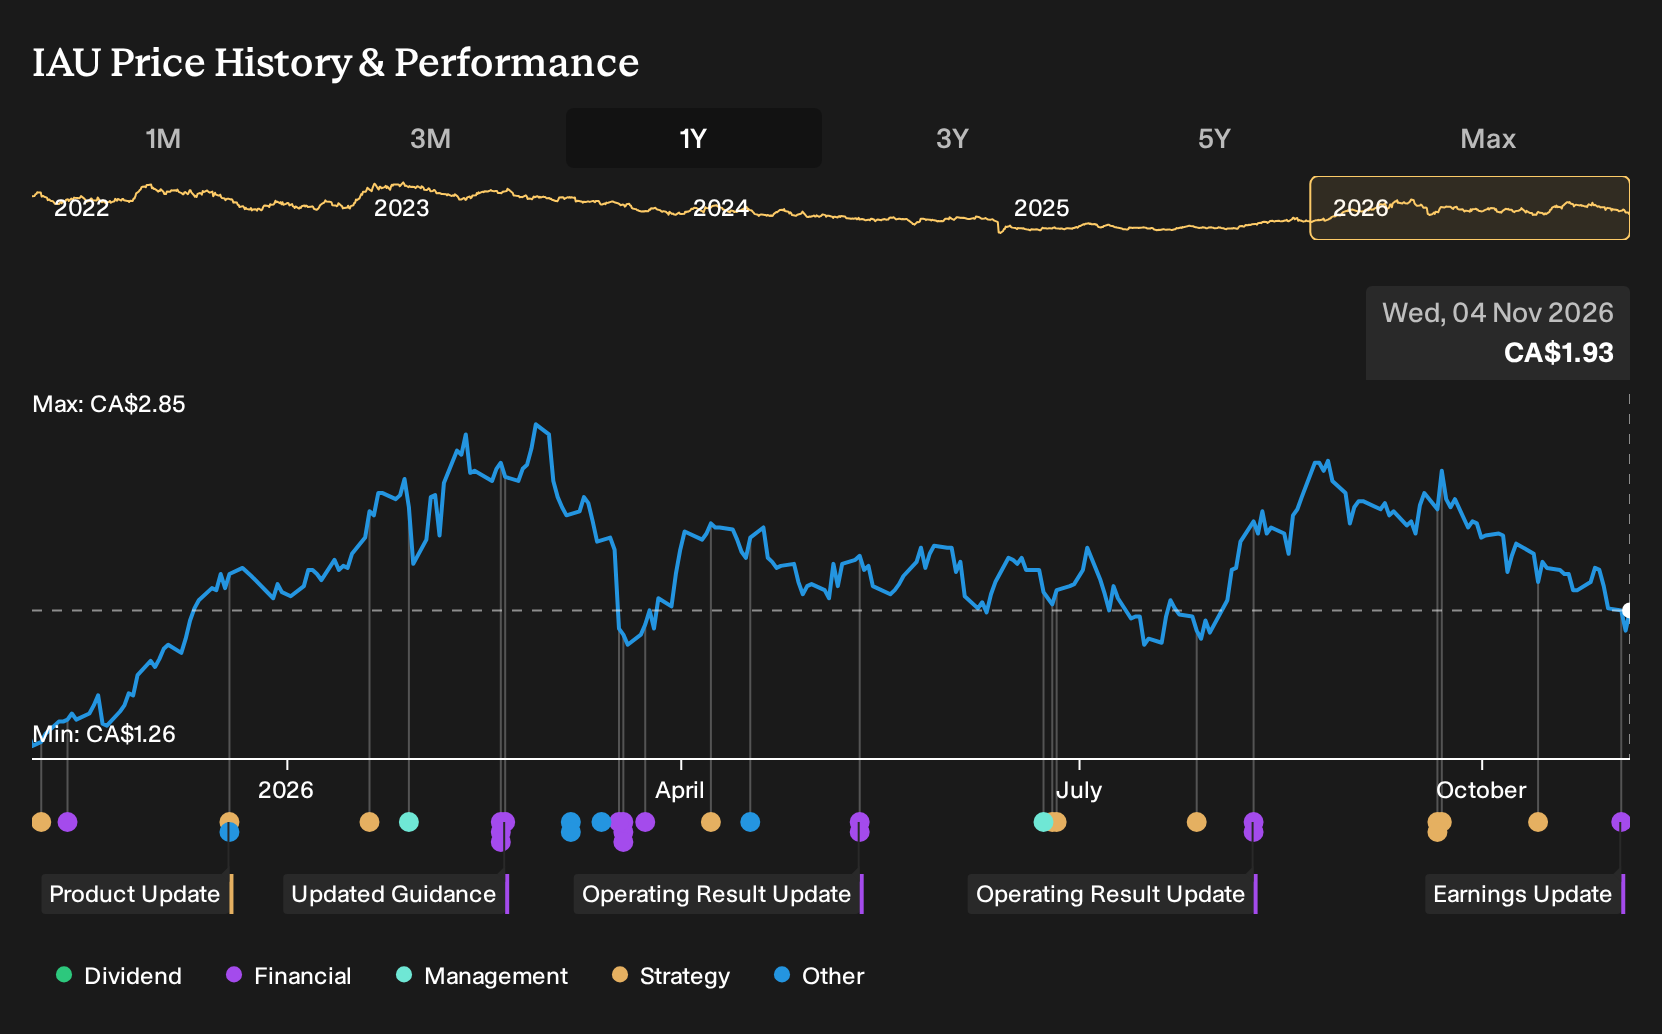
- i-80 Gold reported third quarter 2026 sales of US$32.73 million and a net loss of US$48.35 million, with nine month sales of US$109.47 million and a net loss of US$179.48 million.
- The wider loss per share alongside higher reported sales highlights cost intensity and development spending pressure that investors will be weighing against the Nevada build out plan.
- We will look at how i-80 Gold's investment narrative absorbs higher nine month sales alongside a larger reported net loss.
Screen potential peers to this i-80 Gold update by focusing on production scale, balance sheet strength and development risk across a curated set of 34 elite gold producer stocks in one place.
i-80 Gold Investment Narrative Recap
To own i-80 Gold, investors effectively have to support the Nevada build out that aims to turn current losses into future cash flow. The latest quarter keeps that trade off intact. Sales for both the quarter and nine month period remain meaningful for a developer, but the larger net loss underlines how much the plan still relies on heavy spending before Lone Tree and the broader hub reach full usefulness.
In the near term, the main catalyst is progress on getting more ore consistently through processing, whether at third party facilities or via preparation for Lone Tree. The biggest risk is that ongoing losses and any processing or development hiccups could stretch timelines or require more capital than expected. This earnings update adds cost pressure but does not fundamentally change that equation.
The most relevant datapoint for this update is the nine month 2026 performance. i-80 Gold reported US$109.47 million of sales and a net loss of US$179.48 million. That gap shows how much of the current business model is still geared toward pre production work, feasibility studies and mine development in Nevada rather than steady state operations.
For catalysts, those figures matter because they frame how much runway the business is consuming before Lone Tree and the next wave of Nevada assets are ready to support higher processing throughput. The risk side is clear. If sizeable losses continue for several reporting periods without visible steps toward easing third party processing constraints or firming up project timelines, the investment case could become more about funding endurance than growth potential.
i-80 Gold's narrative projects US$712.3 million in revenue and US$197.6 million in earnings by 2029. This scenario is based on an assumed revenue growth rate of 76.3% per year and an estimated earnings change of about US$456.2 million from the current earnings of a US$258.6 million loss.
Uncover why i-80 Gold's fair value indicates a 140% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For a very different angle, focus on the bullish catalyst around Archimedes Underground. The most optimistic analysts were modelling revenue of about US$1.4b and earnings of roughly US$342.4 million by 2029 for i-80 Gold before this earnings report. Those projections could shift, so treat today’s results as a prompt to compare several narratives side by side.
Explore 3 other i-80 Gold fair value estimates, including one that suggests up to 187% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your i-80 Gold research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for i-80 Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate i-80 Gold's overall financial health at a glance.
Looking for more investment ideas beyond i-80 Gold?
If the i-80 Gold update has sharpened your process, use that same lens on a wider field. Filter for balance sheets, cash flow quality and dividend profiles so you are comparing like for like instead of chasing headlines.
- If capital preservation sits high on your list, start with companies that screen for resilience and predictable profiles through the 9 resilient stocks with low risk scores.
- For readers who care most about quality supported by strong financial footing, focus on businesses with robust funding and liquidity using the list of solid balance sheet and fundamentals (6 results).
- Those hunting for mispriced opportunities can narrow the field to stronger fundamentals at what may be appealing entry points by scanning the 8 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com