
Earnings Beat Might Change The Case For Investing In Transcat Stock
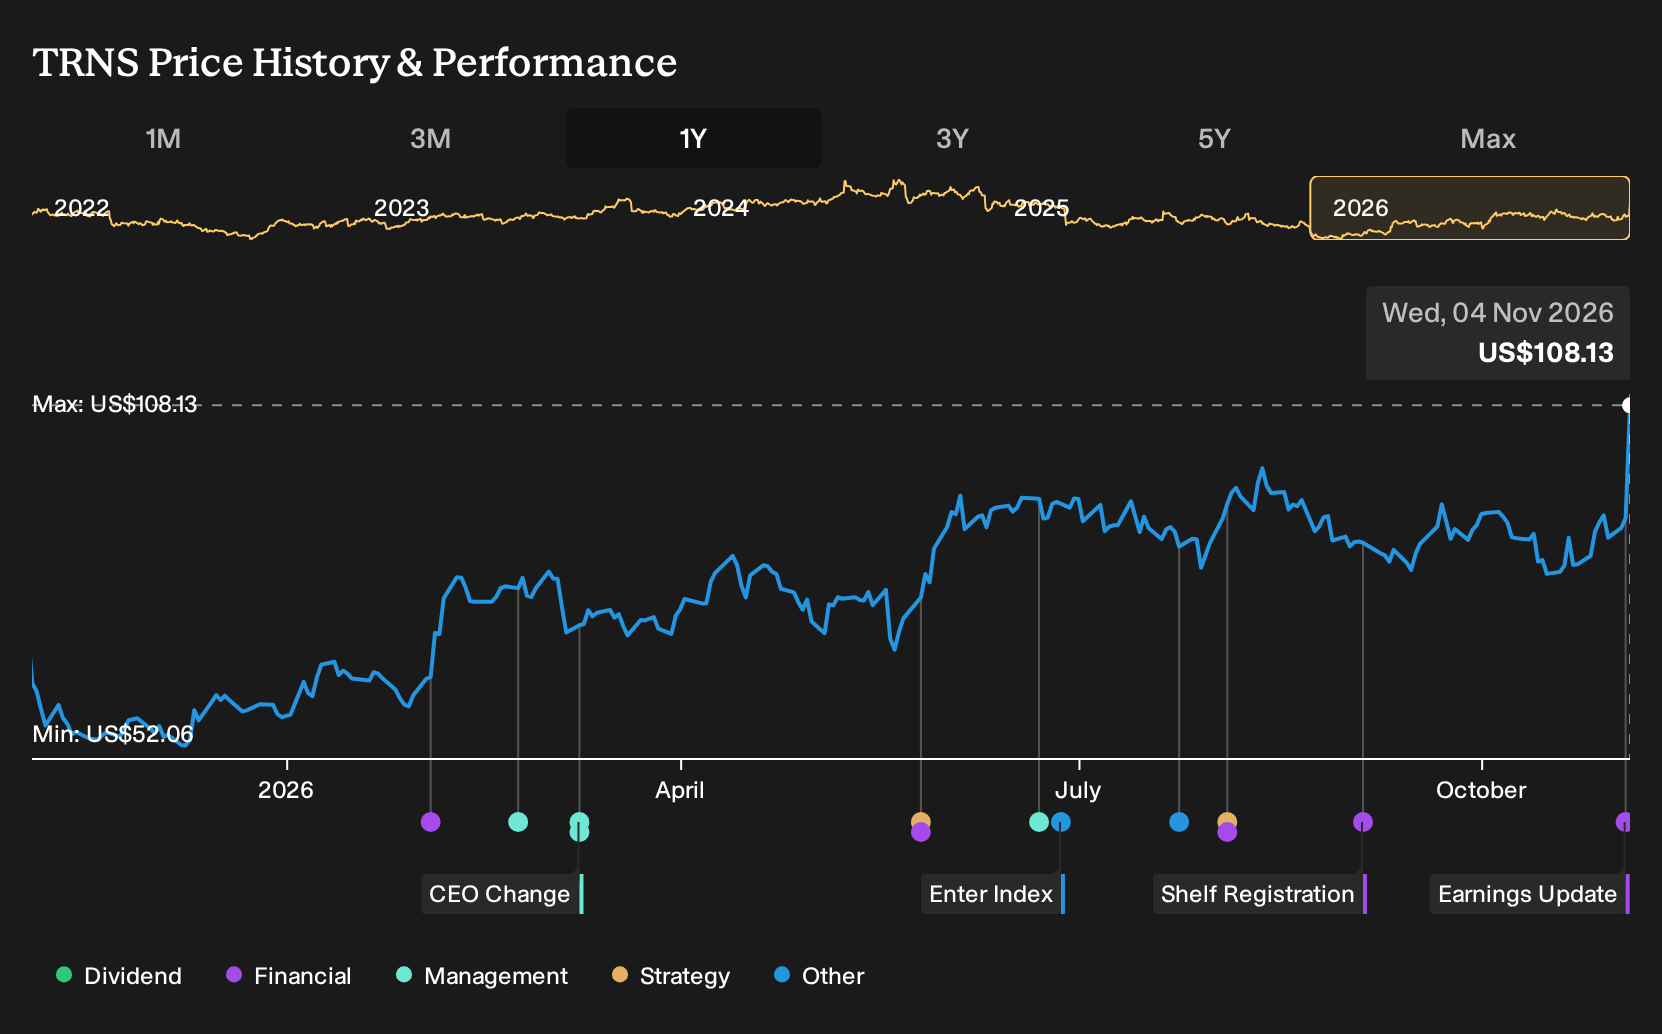
- Transcat reported second quarter 2026 results with revenue of US$97.09 million and net income of US$2.41 million, with basic earnings per share from continuing operations at US$0.26.
- The six month figures showed revenue of US$190.04 million alongside net income of US$3.74 million, which indicates stronger profitability in the latest quarter compared with the first half overall.
- We will now assess how Transcat's investment narrative around recurring calibration demand could be affected by this stronger quarterly earnings performance.
Scan how Transcat's recurring calibration theme compares with other measurement and industrial service plays by reviewing our curated list of solid balance sheet and fundamentals (25 results) for potential peers following similar demand patterns.
Transcat Investment Narrative Recap
To own Transcat, you need to believe that recurring calibration work in regulated industries can convert into healthier margins over time, not just higher sales. The latest quarter shows higher revenue and quarterly earnings than the first half as a whole, which helps the near term story that operational initiatives and scale could support profitability. The immediate upside catalyst still sits in clearer margin progression, not just volume.
The biggest watchpoint remains how efficiently Transcat absorbs acquisitions and manages costs in both Service and Distribution. Six month earnings lag last year even with higher revenue, so integration friction, one off items and gross margin pressure remain live issues. This quarter helps sentiment but does not remove that risk.
With no fresh corporate announcements around M&A or major contracts tied directly to this release, the earnings print itself effectively acts as the main update for your thesis. The reported step up in quarterly net income and earnings per share against last year gives you a cleaner read on how the calibration and rental model is currently converting revenue into profit.
Those numbers sit in a context where analysts describe earnings growth as outpacing revenue growth over the next few years and margin pressure as a key risk. How Transcat moves from six month earnings that trail last year to the profit expansion analysts project will likely depend on execution in Service productivity, rental mix and any future acquisitions, so each quarterly report becomes the practical checkpoint in that process.
Transcat's narrative projects US$427.5 million revenue and US$16.9 million earnings by 2029. This implies 7.1% yearly revenue growth and an earnings increase of about 5x from US$3.4 million today.
Uncover why Transcat's fair value points to a 4% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate perspective on Transcat focuses less on recurring calibration and more on the risk that prior vendor rebates in Distribution may not repeat. The most cautious analysts were still modeling about US$433.6 million of revenue and US$17.9 million of earnings by 2029. That is a surprisingly optimistic path, and this latest earnings release may prompt those views to adjust. Readers can use that variation in expectations as a reminder that reasonable opinions can differ widely, so it can help to test several narratives before forming a view.
Explore 2 other Transcat fair value estimates, including one that suggests as much as 33% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Transcat research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Transcat. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Transcat's overall financial health at a glance.
Looking For More Investment Ideas Beyond Transcat?
Once you have a view on Transcat, it can help to compare that thesis with other businesses screened on clear fundamentals, so you can see where the risk and reward profile looks more attractive for your own goals.
- If capital preservation is front of mind, start with companies that pair balance sheet strength with solid fundamentals through our 31 resilient stocks with low risk scores.
- For investors who want quality first and are willing to be patient, filter for resilient businesses that look mispriced on core metrics with the 19 high quality undiscovered gems.
- If reliable finances matter more to you than a hot story, scan financially sound stocks that pass tough balance sheet checks using this curated list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com