
Silvercorp Metals (TSX:SVM) Restores A Dividend, Is The Stock Overvalued?
Silvercorp Metals (TSX:SVM) has put income back on the table with its board declaring a semi-annual dividend of US$0.0125 per share for investors on record as of November 27, 2026.
The semi-annual dividend lands as Silvercorp Metals trades at CA$12.11, with the share price up 8.71% over the last day but down 19.37% over 30 days and 20.12% over 90 days. Total shareholder return over one year and three years has been strong, which suggests recent momentum has cooled even as longer term holders have still seen very large gains overall.
Scan beyond Silvercorp Metals and explore other income and precious metal ideas using the hand picked 10 top silver producer stocks that are responding to the same combination of dividends, project updates, and price movements.
Bulls see Silvercorp Metals as a rerated income and growth play after years of strong total returns. Bears point to project delays, safety upgrades, and revenue pressure. Which story does the valuation actually support next?
Price-to-Earnings of 61.3x: Is it justified?
Valuation for Silvercorp Metals now hinges on a simple question: Is a P/E of 61.3x at a last close of CA$12.11 paying too much for the earnings profile on offer compared with peers?
The P/E ratio compares what investors pay per share to the profit per share that the business generates. For a miner like Silvercorp Metals, a high P/E often signals that the market is willing to look through recent profit pressure and focus on the forecasts for revenue and earnings growth instead of the latest margin hit.
Here, the multiple is rich compared with almost every benchmark given. The P/E of 61.3x is much higher than the Canadian Metals and Mining industry average of 13.4x and well above the peer average of 21.3x. This implies investors are already paying a premium for expected growth. It is also far ahead of the estimated fair P/E of 24.8x, a level the ratio could move toward if enthusiasm for those forecasts cools or if earnings do not track expectations.
Explore the SWS fair ratio for Silvercorp Metals.
Result: Price-to-Earnings of 61.3x (OVERVALUED)
Still, the story can flip quickly if project delays drag on cash generation, or if safety and regulatory upgrades in China lift costs faster than Silvercorp Metals can offset.
Find out about the key risks to this Silvercorp Metals narrative.
Another View: What the SWS DCF Model Says About Silvercorp Metals
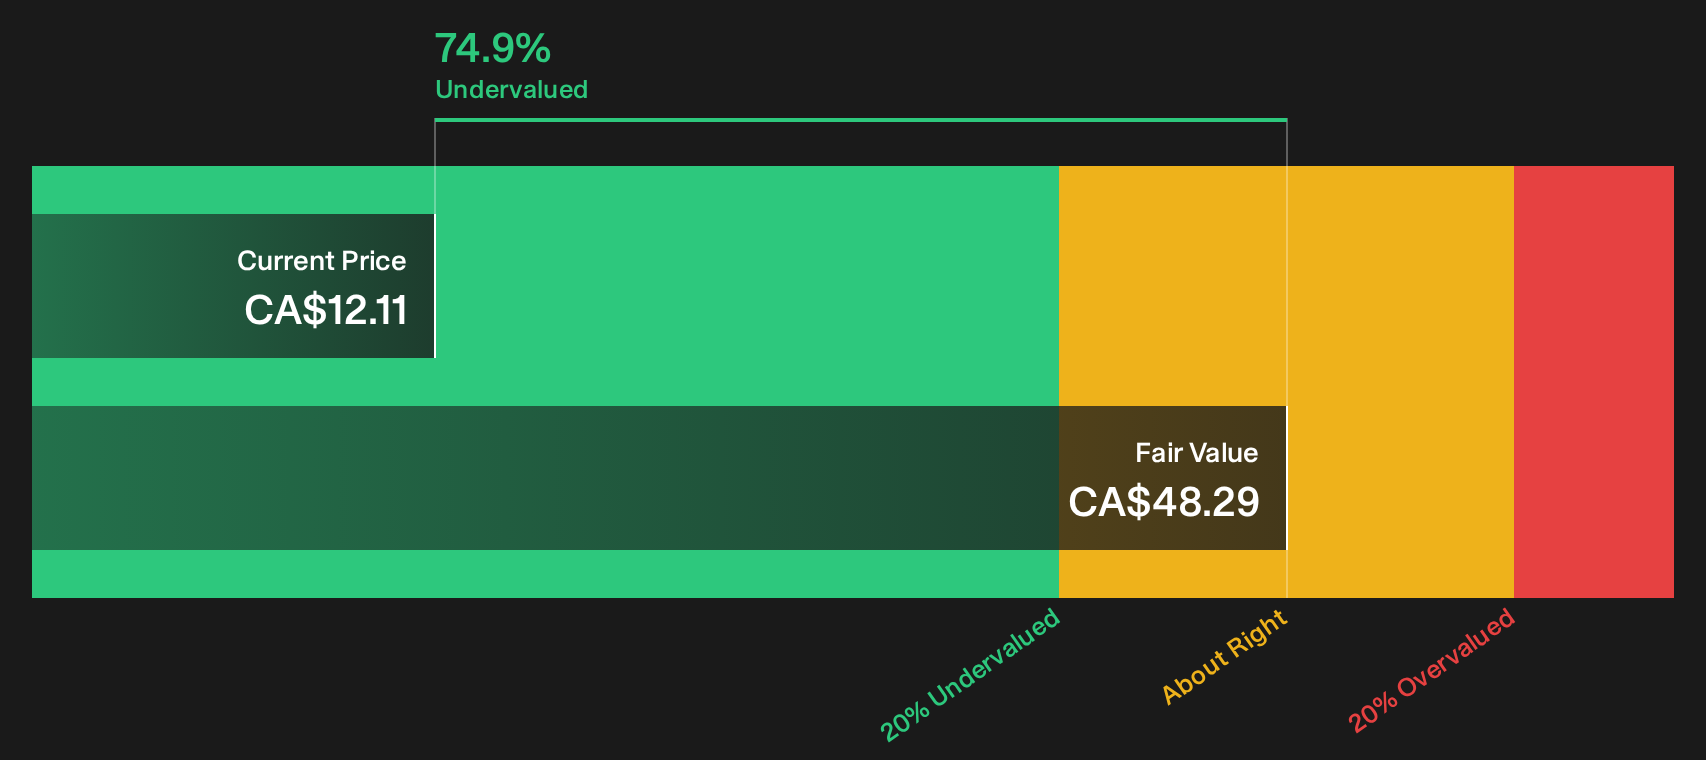
The rich 61.3x P/E paints Silvercorp Metals as expensive, yet our DCF model points in the opposite direction. On that cash flow view, the stock at CA$12.11 trades about 74.9% below an estimated fair value of CA$48.29. This frames the current price as discounted rather than stretched. Which signal do you trust more: the earnings multiple or the cash flows?
To unpack how that cash flow estimate is built and stress test the assumptions behind it, take a closer look at the SWS DCF approach for Silvercorp Metals using the Look into how the SWS DCF model arrives at its fair value..
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Silvercorp Metals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
There are mixed messages on Silvercorp Metals so far. If you want to act quickly and evaluate the trade-off for yourself, review the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Silvercorp Metals?
Do not stop your research at a single ticker. Broader context across sectors and styles can sharpen your instincts and highlight opportunities you might otherwise miss.
- Target dependable cash generators by scanning companies with robust payouts and balance sheets through the 3 dividend fortresses.
- Hunt for quality at a discount by reviewing the 5 high quality undervalued stocks that combine solid fundamentals with prices that lag their underlying strength.
- Unearth potential future leaders before they hit the spotlight using the 8 high quality undiscovered gems that filter for strong financial profiles hiding in plain sight.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com