
Illumina (ILMN) Lands Singapore Genomics Role As Undervalued Narrative Faces A Fresh Test
Illumina (ILMN) just picked up a major role in Singapore's National Precision Medicine Phase III programme, being chosen to sequence roughly 450,000 residents for the SG-INSIGHT population genomics study.
The SG INSIGHT award lands after a busy stretch for Illumina, with third quarter results on 29 October 2026 showing revenue of US$1,129 million and net income of US$220 million, followed by slightly higher full year revenue guidance. Despite that backdrop, the share price has retreated 21.56% over the past week and 22.86% over the past month, even though the 90 day share price return is 16.94% and the year to date share price gain is 68.62%. The 1 year total shareholder return of 85.02% and 3 year total shareholder return of 110.57% point to strong past rewards for investors, alongside a more mixed 5 year total shareholder return, which is down 39.56%. This suggests that momentum has recently cooled after a strong run.
Capitalize on Illumina's genomics spotlight by scanning a curated group of 38 healthcare AI stocks that could benefit as precision medicine and AI driven healthcare adoption broadens.The share price has sprinted ahead over the past year, then stumbled hard this week, while analyst and intrinsic estimates cluster above the current US$226.54. Where does fair value really sit in that spread?
Most Popular Narrative: 9% Undervalued
Illumina’s most followed narrative pins fair value at $248.90, a touch above the last close at $226.54. This sets a tight but constructive valuation gap that depends on the strength of its clinical and data franchises.
The rapid transition to NovaSeq X, with more than 80 instruments placed in Q1 2026 and more than 95 in Q2 2026 and over three quarters of clinical volume already on the platform, supports expectations that an expanded installed base will keep consumables revenue and gross profit growing from this higher level.
See why 53 investors see Illumina as 9% undervalued.
Result: Fair Value of $248.90 (UNDERVALUED)
Still, the bearish narrative could unravel if Illumina’s clinical consumables strength or AI driven data offerings outpace expectations and support more resilient earnings power.
Find out about the key risks to this Illumina narrative.
Another View: Illumina Through The P/E Lens
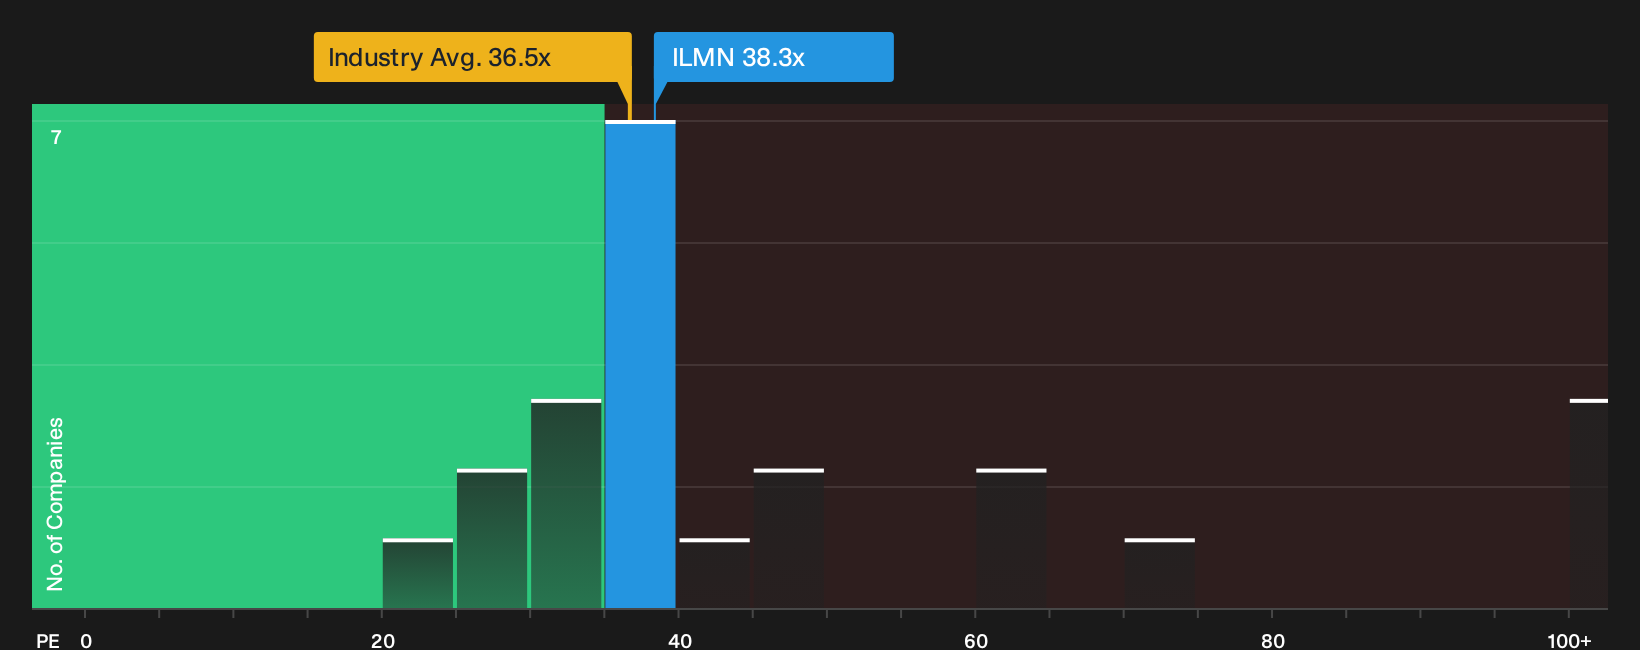
Illumina looks modestly undervalued against the $248.90 narrative fair value and a 3.7% discount to the Simply Wall St estimate. However, the current P/E of 38.3x sits above the global Life Sciences group at 35.9x and well above its own fair ratio of 28.2x. That richer multiple points to less room for error if growth or margins underwhelm, so the key question is whether this represents a valuation cushion or more of a tightrope.
To see how this price tag lines up with earnings expectations and margin assumptions in detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Illumina’s value case so far. If you want your own take, consider both the potential benefits and the concerns by reviewing the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Illumina?
Do not stop your research with Illumina when the broader market is full of different risk and reward profiles that could better match your goals and timeframe.
- Target higher potential upside by scanning a tightly filtered group of 34 high quality undervalued stocks that combine quality fundamentals with pricing that has not fully caught up.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results), where stronger finances can help cushion shocks and keep businesses on steadier footing.
- Get ahead of the crowd by researching a hand picked pool of 19 high quality undiscovered gems before wider attention potentially closes the valuation gap.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com