
Is Private Markets Data Altering The Investment Case For FactSet (FDS)?
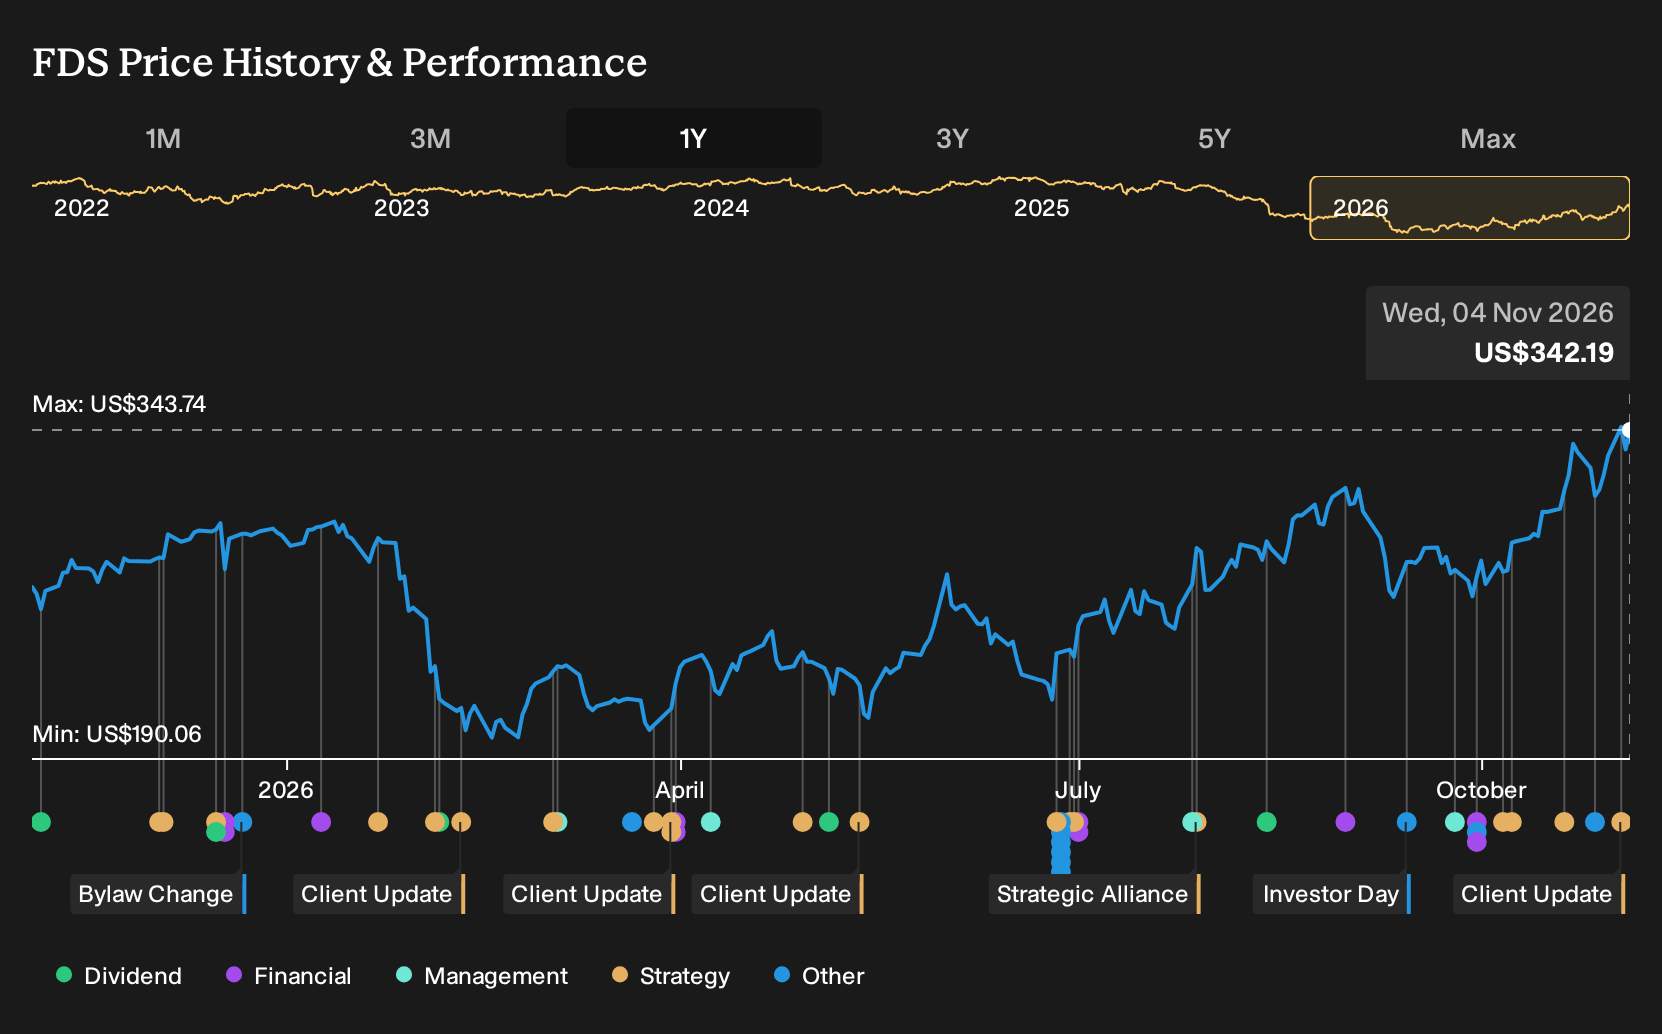
- On 2 November 2026, FactSet Research Systems reported a new partnership with Hamilton Lane that embeds private markets benchmarks and fund level data directly into FactSet’s portfolio analytics platform.
- The combination of Hamilton Lane’s fund and deal data with Nasdaq Private Market cap table information gives FactSet clients a more complete view of private assets inside existing workflows.
- We will now look at how FactSet Research Systems' deeper private markets data access could influence the broader investment narrative for the business.
Scan how other data and analytics stocks are positioned around private markets exposure by reviewing our curated list of 19 high quality undiscovered gems that may still be flying under most investors’ radar.
FactSet Research Systems Investment Narrative Recap
For a shareholder in FactSet Research Systems, the core belief is that a broad data and analytics platform can keep attracting long term contracts while AI tools and MCP delivery support steady, subscription driven growth. The Hamilton Lane and Nasdaq Private Market integrations fit this story by deepening content, although the near term revenue effect looks incremental rather than transformational.
Right now, the key short term swing factor is whether clients keep adopting higher value enterprise and AI products fast enough to offset pressure from cautious asset managers and banks. The biggest risk is slower ASV additions if price increases soften or tech budgets stay tight, which would limit margin progress after the current investment phase.
The Hamilton Lane partnership is the most relevant update for this narrative because it plugs a long standing gap in institutional quality private markets data inside FactSet Research Systems’ workflows. Investors watching catalysts around AI, MCP and enterprise contracts now have a clear operational step that links richer content to the whole portfolio analytics story.
This integration also interacts directly with existing risks. If rival platforms push hard into private assets and AI driven analytics, execution on the Hamilton Lane rollout, combined with Nasdaq Private Market cap table data, will help show whether FactSet can keep clients on one system for public and private holdings or whether competitive pressure starts to weigh on ASV momentum.
FactSet Research Systems' current story ties directly into these consensus numbers. Analysts are assuming revenue climbs at 5.7% per year and that earnings move from $533.5 million today to $704.3 million by 2029. That path implies revenues of about $2.9 billion and an earnings step up of roughly $170.8 million from current levels by the same forecast year.
Uncover why FactSet Research Systems' fair value indicates an 18% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
Some bearish analysts focus on integration risk for new areas like private markets rather than on FactSet Research Systems' AI story. Before this Hamilton Lane announcement, the most cautious forecasts were for revenue of about US$2.9b and earnings near US$653.1m by 2029. That tells you opinions differ sharply, so explore a few viewpoints before deciding how this news might reshape the story.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 38% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking for more investment ideas beyond FactSet Research Systems?
If the FactSet Research Systems story has sharpened your thinking about data platforms, keep that momentum going by widening your watchlist to other companies with different risk and return profiles.
- For investors who want potential upside paired with disciplined balance sheets, review a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially resilient businesses.
- If capital preservation and steadier return streams matter most to you, scan a 31 resilient stocks with low risk scores that filters for companies with more measured risk scores.
- When you are hunting for ideas that have not attracted broad attention yet, work through a 19 high quality undiscovered gems that surfaces lesser known stocks with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com