
3 LNG Stocks Retail Investors May Watch After Woodside’s Long Term Growth Plan
Woodside just put a big number on its LNG ambitions, with targets that run well into the next decade and a funding plan that could reshape how cash flows back to investors. That kind of clarity on projects, volumes and potential capital returns can move markets, which means portfolios tend to move with it. This article walks through 3 stocks exposed to this news and explains why each one may deserve a closer look now.
The three stocks covered next are only a starting sample, since the full screen surfaced 43 more listed LNG and gas producers with equally detailed stories that are not broken out here.
If you want to identify potential LNG opportunities and analyze where the highest conviction ideas might sit, go straight to the Global LNG & Integrated Natural Gas Producers screener.
Diversified Energy (DEC)
Overview: Diversified Energy produces, transports and markets natural gas, oil and liquids across multiple US shale basins, giving investors direct exposure to the natural gas value chain.
Operations: Diversified Energy generates about US$1.9b of revenue from producing and transporting natural gas, NGLs and oil entirely within the United States.
Market Cap: US$965 million
For investors looking at LNG and gas exposure, Diversified Energy offers a more regional link into US production that still sits squarely in the supply chain feeding liquefaction projects.
"Although the Birch Resources acquisition brings a large, liquids heavy Permian position with operating costs around US$5.70 per BOE and high EBITDA margins, integrating 68 Mboe/d of new production and 1.2 Tcfe of reserves at scale could strain field level cost control and dilute group margins and earnings if expected operating efficiencies do not materialize."
What happens to cash generation if a single pressure on cost discipline and integration efficiency shifts away from management’s current playbook?
If that cost discipline question is front of mind, the full narrative for Diversified Energy sets out how management plans to balance acquisition risk with potential cash flow acceleration.

Gulfport Energy (GPOR)
Overview: Gulfport Energy focuses on acquiring and producing natural gas, crude oil and NGLs in US shale basins, giving direct gas-field exposure within the LNG-oriented screener.
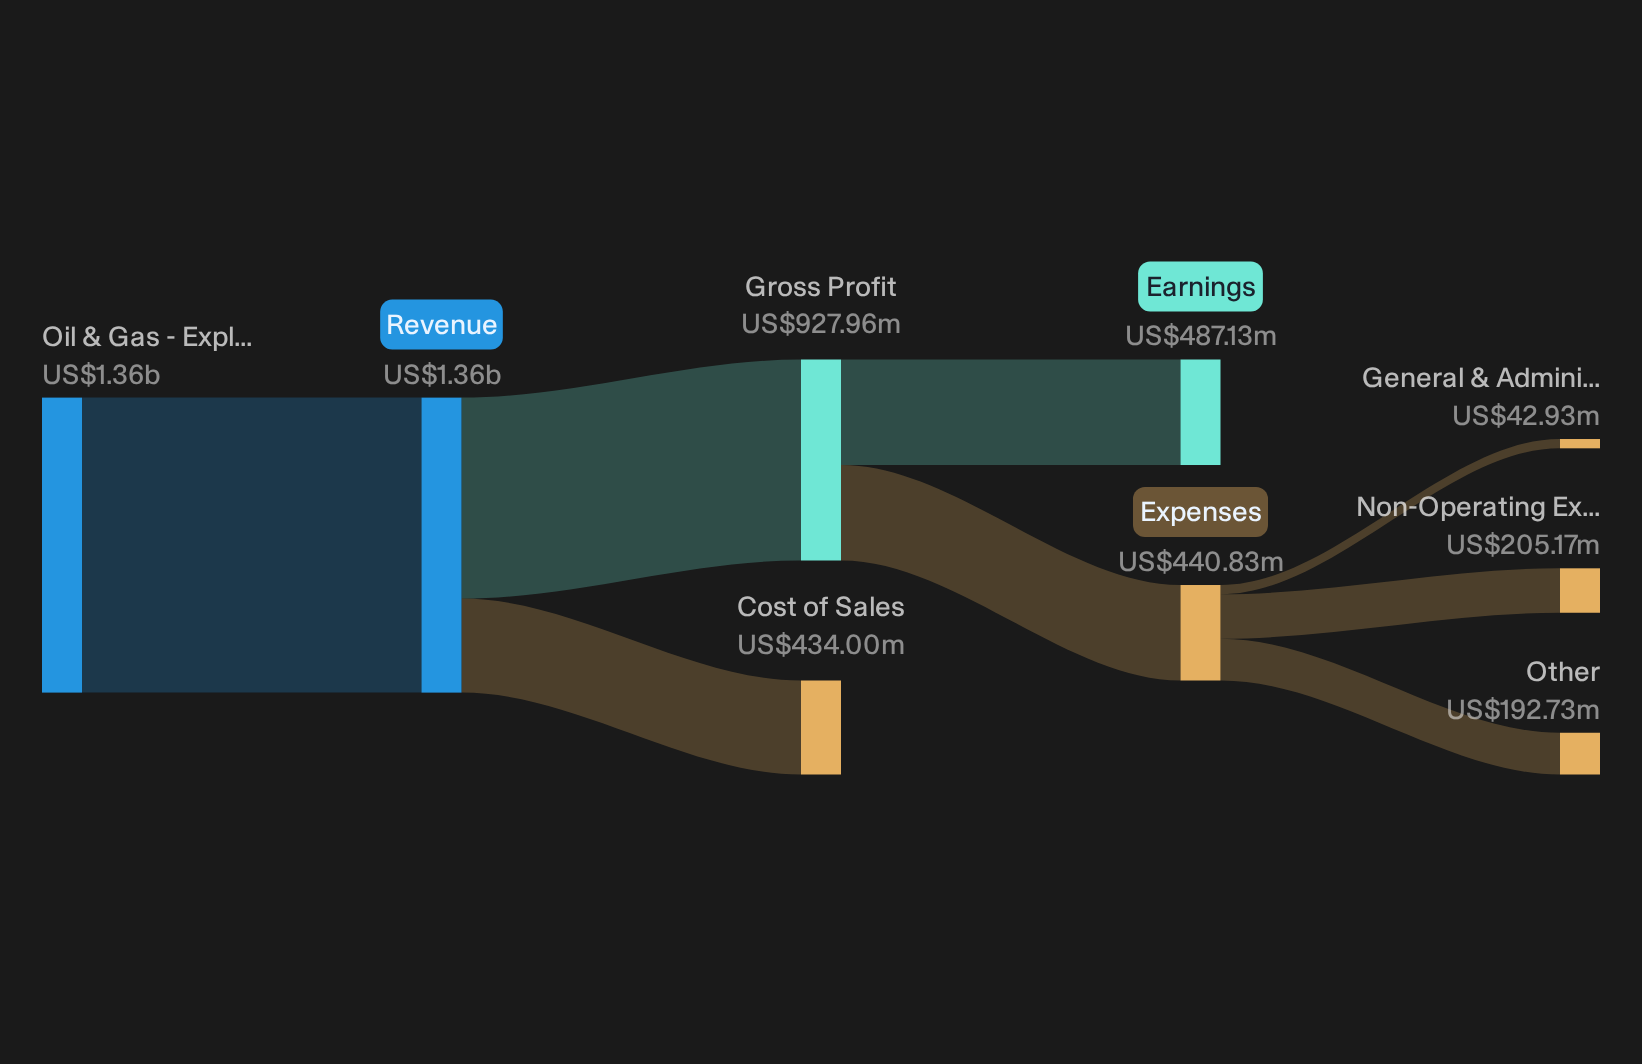
Operations: Gulfport Energy generates about US$1.4b in revenue from oil and gas exploration and production, primarily through its upstream operations.
Market Cap: US$2.9b
For LNG-focused investors, Gulfport Energy matters because it offers pure upstream gas and liquids exposure that can feed export projects without tying you to a single liquefaction developer.
"Planned growth in liquids volumes, with second half 2026 liquids production expected to be more than 50% higher than the first half and move the mix toward low teens, gives Gulfport Energy more exposure to liquids pricing that can support revenue diversification and steadier earnings."
The real hinge is how one quiet shift in Gulfport Energy’s capital allocation mix ends up affecting long term margins and cash generation.
That hinges on whether this shift is masking deeper return potential or hidden trade offs, and the full narrative for Gulfport Energy maps out how Gulfport Energy’s allocation could accelerate or stall value creation.
Williams Companies (WMB)
Overview: Williams Companies runs a large network of natural gas pipelines and midstream assets across major U.S. gas basins and demand hubs.
Operations: Williams Companies generates about US$5.8b from Transmission, Power & Gulf, US$3.1b from West, US$2.3b from Gas & NGL Marketing Services and US$2.2b from Northeast G&P, almost entirely in the United States.
Market Cap: US$88.6b
Williams Companies matters in this LNG focused screen because its pipes and gathering systems help move U.S. gas from shale fields to Gulf Coast export and power markets.
"Large-scale expansions of Williams Companies' pipeline network, including projects such as Shelby Connector with up to 1.5 Bcf per day potential capacity and Delta Access with up to 3.5 Bcf per day potential capacity, are being developed to move Western Haynesville gas to Gulf Coast LNG and power customers. These projects can lift future transported volumes and segment EBITDA."
What happens to Williams Companies' earnings path if a single assumption about long term contracted volumes shifts even slightly off the current track?
If that contract risk is what you keep circling back to, the full narrative for Williams Companies shows where Williams Companies' contracted volumes could be accelerating or quietly stalling.

Curious About High-Conviction Alternatives?
Fresh ideas do not stay quiet for long. Momentum shifts, early breakouts get caught, and under the radar stories close fast. Scan the next wave and act now.
- Spot income workhorses with yields that could anchor a portfolio while you keep hunting LNG ideas through the 5 dividend fortresses before that list gets crowded.
- Explore fast-moving themes in automation and factory intelligence by running the 93 robotics and automation stocks while these stories are still priced as early stage opportunities.
- Track companies building the rails for data hungry AI models by scanning the 53 AI infrastructure stocks before attention fully catches up with their role in the stack.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com