
HNI (HNI) Could Be 31% Undervalued On Its Q3 Earnings Beat
HNI (HNI) just posted a strong third quarter earnings beat, reporting non-GAAP EPS of US$1.62 on US$1.59 billion in revenue, supported by volume gains and the Steelcase integration.
Those results come against a backdrop of steady share price gains for HNI, with the stock up 4.8% over the past 7 days and 15.4% year to date, while the 1-year total shareholder return of 26.6% points to momentum that has been building rather than fading.
Scan the market for other companies showing earnings momentum and integration stories like HNI by reviewing our hand picked 19 high quality undiscovered gems.
HNI is now carrying a stronger earnings print, a bigger Steelcase platform and a higher share price. Does that recent run still leave enough upside to justify the risk on today’s valuation multiples?
Most Popular Narrative: 31% Undervalued
HNI is trading at $49.14 against a most-followed narrative fair value of $71, which frames the recent earnings beat inside a bigger multi year margin and cash flow story.
Expanded efficiency programs that now include Steelcase related savings and broader network optimization, with cumulative benefits expected to exceed US$150 million when mature, are building on earlier Mexico and KII initiatives and can further lift operating margins and non GAAP EPS.
See why 18 investors see HNI as 31% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the HNI story can break if hybrid work restrains office furniture demand again, or if pricing pressure and higher input costs squeeze margins instead of widening them.
Find out about the key risks to this HNI narrative.
Another View: HNI Looks Expensive On Earnings
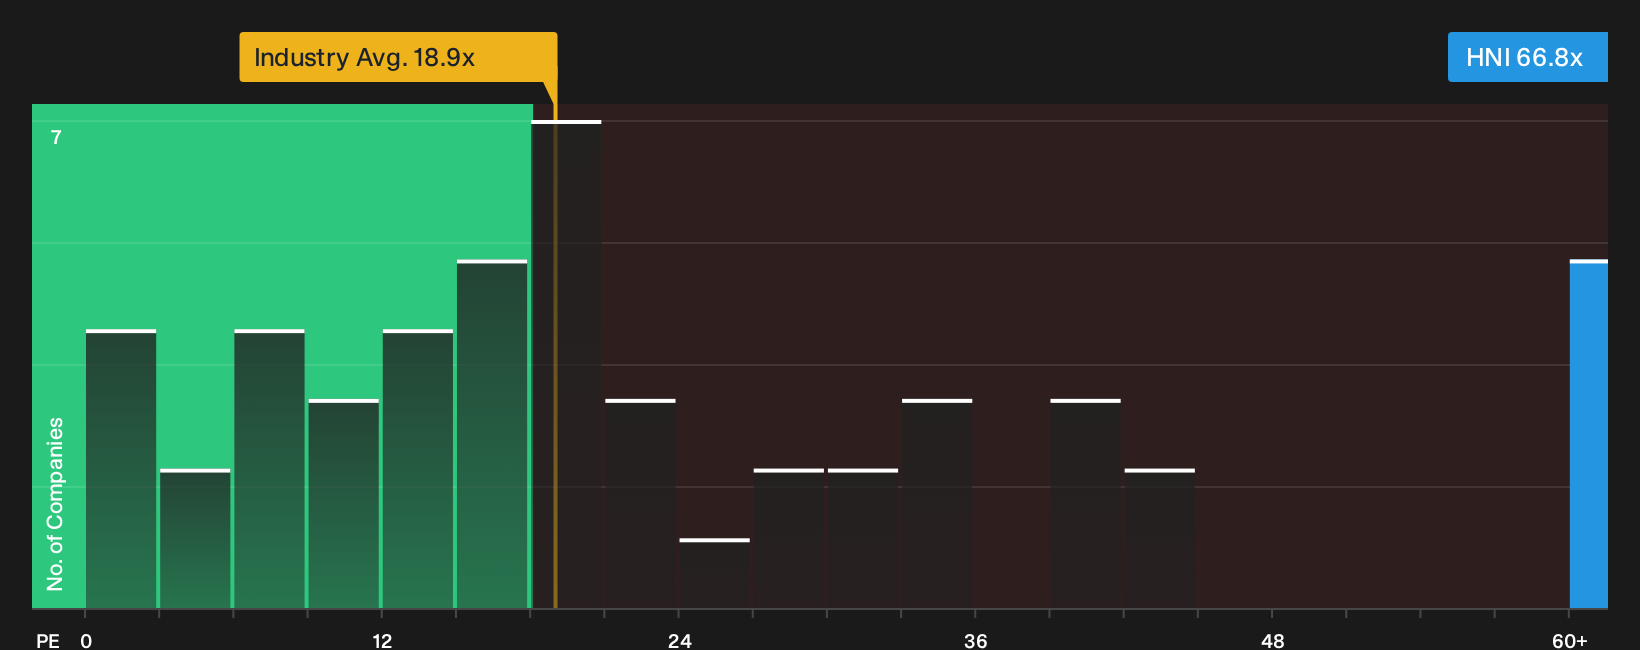
The story changes when the lens shifts from fair value models to simple earnings multiples. On a P/E of 66.8x, HNI trades far above the US Commercial Services sector at 18.9x and ahead of its own fair ratio of 45.7x. This points to richer expectations baked into the price.
Paying such a premium multiple can work if earnings track the optimistic forecasts. However, it also raises the risk that any stumble in margins, cash flow or office demand could hit the share price harder than the underlying business.
To see how this price stacks up against the underlying numbers, check out the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty in this HNI story looks promising, but the data also flags real concerns that could cut the other way. If you want to move quickly and build your own view before sentiment shifts again, start by weighing the 4 key rewards and 4 important warning signs.
Looking For More Ideas Beyond HNI?
Do not stop your research with HNI. Broaden your watchlist with a few focused stock lists that surface different types of opportunities before others spot them.
- Target resilient balance sheets by reviewing our curated list of solid balance sheet and fundamentals (25 results) that highlight companies pairing financial strength with underlying business quality.
- Hunt for value by scanning the 34 high quality undervalued stocks that flags stocks where fundamentals and price appear out of sync.
- Prioritise staying power by using the 31 resilient stocks with low risk scores that filters for businesses with lower risk scores and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com