
Freshworks (FRSH) Raises Outlook As Fair Value Stays In Focus
Freshworks (FRSH) moved back into focus after its third quarter update, where management raised full year 2026 guidance following revenue of US$245.43 million and a swing to quarterly profitability.
Freshworks shares have pulled back sharply in the very short term, with a 1-day share price return of down 6.29% and a 7-day share price return of down 13.78%. This is despite a 90-day share price return of 14.41% and a 1-year total shareholder return of 19.89%, which point to improving momentum from a weaker multi year record. Over longer periods, the 3-year total shareholder return is down 27.34% and the 5-year total shareholder return is down 65.06%, based on a latest share price of US$13.26.
Compare Freshworks' momentum and guidance reset with other SaaS players by scanning our hand picked 34 high quality undervalued stocks that also pair growing revenue with solid balance sheets.
Freshworks is back in the black and guiding higher, yet the share price has just been knocked down again. Is the meaningful upside still ahead, or was most of it already captured in the earlier rebound as valuation now stands?
Most Popular Narrative: 10.3% Undervalued
Freshworks' most followed narrative pegs fair value at $14.79, above the latest close of $13.26. This frames the recent pullback as a move against that valuation anchor.
The current valuation and recent share price strength imply that the market already prices Freshworks as fairly valued, with meaningful execution risk if AI driven uplift, EX mix shift, and cash generation do not match current expectations.
The main thing that has to go right is that Freshworks converts strong EX ARR momentum, rising Freddy AI adoption, and expansion of Freshservice into ITAM, ITOM, and ESM into durable net dollar retention while keeping CX steady and margins disciplined.
See why 33 investors see Freshworks as 10% undervalued.
Result: Fair Value of $14.79 (UNDERVALUED)
Still, if EX or Freddy AI adoption cools, or larger rivals squeeze Freshworks on pricing and renewals, this fair value narrative could unwind quickly.
Find out about the key risks to this Freshworks narrative.
Another View: Freshworks Through The Earnings Lens
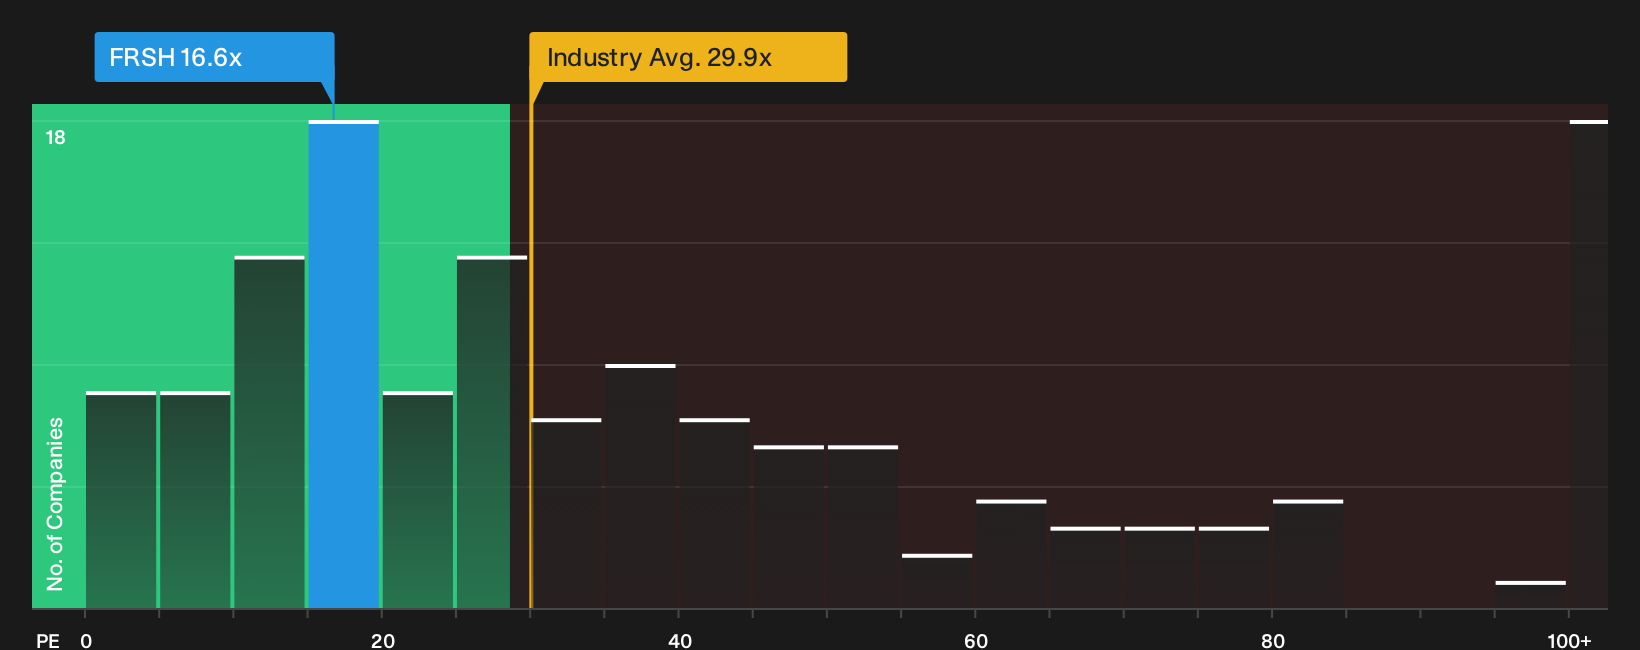
The fair value narrative puts Freshworks at $14.79, which looks supportive against a $13.26 share price. The earnings ratio tells a different story. FRSH trades on a P/E of 16.6x while the fair ratio is 9.8x, even though the broader US Software group sits at 29.9x and close peers average 67.1x. That gap between fair ratio and actual P/E points to less room for error if earnings slip or forecasts reset. The question is which anchor to rely on when volatility picks up next.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of raised guidance and a sharp pullback leaves sentiment around Freshworks finely balanced. Move quickly and pressure test the story for yourself with the full breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Freshworks?
If Freshworks has your attention, do not stop here. Broaden your watchlist with other opportunities that line up with your goals and risk comfort.
- Target resilience first by scanning a 31 resilient stocks with low risk scores that focuses on companies with lower risk scores and steadier profiles.
- Hunt for quality at a discount through a 19 high quality undiscovered gems that highlights lesser known businesses with solid fundamentals.
- Prioritise financial strength by reviewing a list of solid balance sheet and fundamentals (25 results) that filters for robust balance sheets and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com