
Is Wayfair (W) Fully Priced On Its Return To Profitability?
Wayfair (W) just delivered third quarter results that caught the market’s eye, reporting sales of US$3,420 million and a US$62 million profit compared with a loss in the same period a year ago.
The earnings release has landed alongside a sharp move in the share price, with Wayfair’s latest close at US$123.56 and a 1-day share price return of 11.0%, building on a 30-day share price gain of 16.5% and a 1-year total shareholder return of 22.5%.
Compare Wayfair’s rebound with a curated list of other retailers showing solid fundamentals and price momentum by scanning the 19 high quality undiscovered gems right after reviewing these results.
Wayfair has swung from loss to profit just as the share price has sprinted higher. Does that recent surge still leave enough upside in the risk reward, or has the easy part of the rerating already happened?
Most Popular Narrative: 10% Undervalued
Against Wayfair’s last close at $123.56, the most widely followed narrative pegs fair value at $123.66, essentially in line, and treats the current valuation as reflecting real progress on profitability and cost control while still flagging limited room for mistakes.
The numbers and this narrative’s view that Wayfair is fairly valued and bullish imply the share price already reflects meaningful progress on growth, profitability and dilution control, with limited room for disappointment.
See why 15 investors see Wayfair as 0% undervalued.
Result: Fair Value of $123.66 (ABOUT RIGHT)
Still, the Wayfair story carries tension, as a softer home furnishings category and a tough housing market are both capable of knocking that fair value narrative off course.
Find out about the key risks to this Wayfair narrative.
Another View: Wayfair Through The P/S Lens
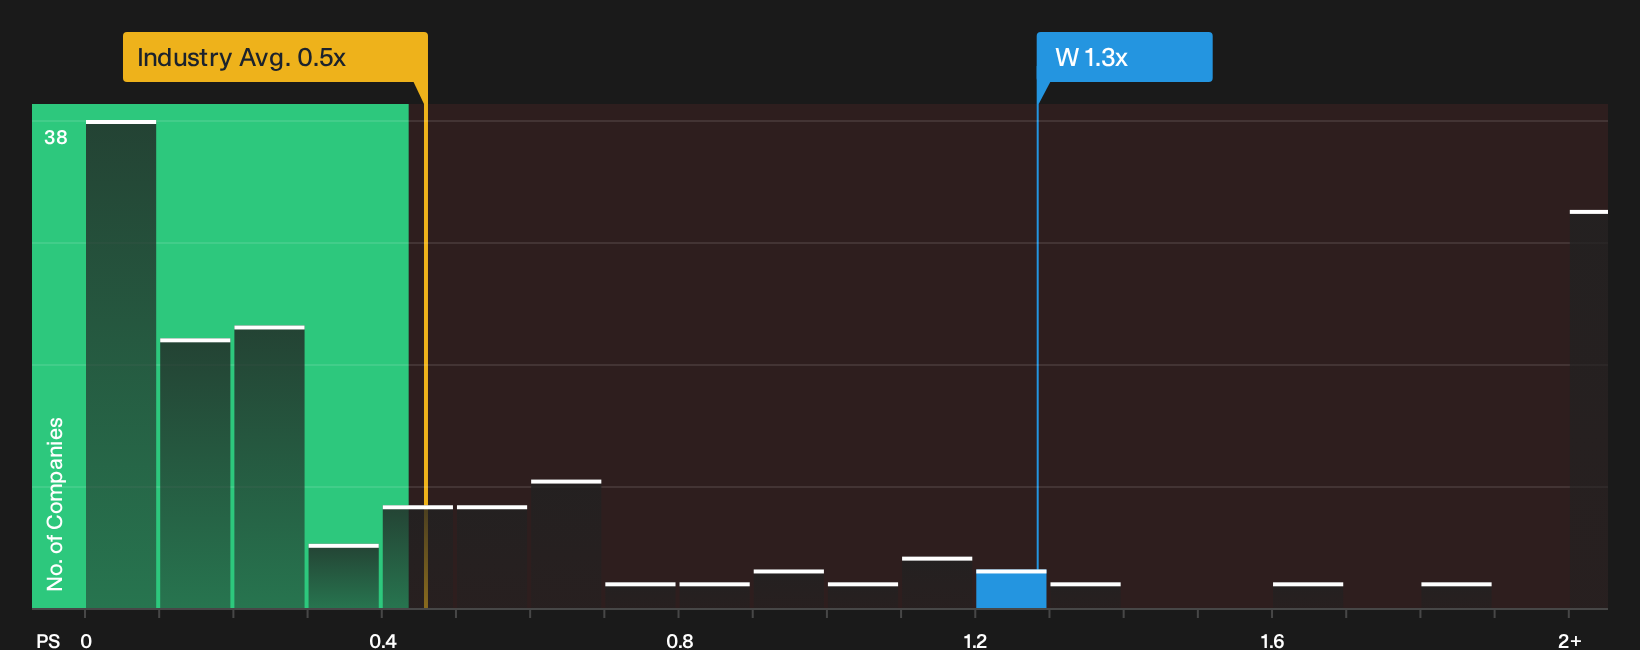
There is a different read on Wayfair when the focus shifts to simple sales multiples instead of discounted cash flows. The stock trades on a P/S of 1.3x, above the US Specialty Retail industry at 0.5x, yet below peers that sit closer to 1.8x.
The fair ratio for Wayfair is estimated at 0.8x P/S, which is well under the current 1.3x level. That gap suggests investors are already paying up relative to the fair ratio, even if the stock still looks cheaper than some direct comparables. The question is whether that premium feels comfortable given the firm is still working toward sustained profitability.
For a closer look at how these numbers stack up against both peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Wayfair is mixed, with clear positives and real question marks pressing on the story. Act while the information is fresh and weigh both sides by reviewing the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Wayfair?
If Wayfair has sharpened your focus on where capital is working hardest, do not stop at a single stock. Spread your research so one story never defines your portfolio.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations using the 34 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) so cash strength and balance sheet depth back the story, not just the share price chart.
- Lock in potential income streams by checking out 5 dividend fortresses that focus on higher yields supported by underlying business strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com