
What Dräger's Stronger Nine Month Profit Means For Shareholders
- Drägerwerk KGaA reported third quarter 2026 sales of €850.77 million and net income of €34 million, with nine month sales at €2,453.95 million and profit of €74.95 million.
- Nine month net income at Drägerwerk KGaA rose from €44.85 million to €74.95 million, suggesting cost and mix effects are helping earnings more than quarterly figures alone reveal.
- This article now explores how Drägerwerk KGaA's stronger nine month profit performance could influence its investment narrative for long term investors.
Compare Drägerwerk KGaA's latest earnings shift with a curated set of companies showing resilient profitability trends using the 194 high quality undervalued stocks.
Drägerwerk KGaA Investment Narrative Recap
To own Drägerwerk KGaA, you need to believe the shift from pure sales growth to more resilient earnings can continue, supported by services, connected systems and a healthier mix between Safety and Medical. The latest quarter showed steady sales and nine month profit of €74.95 million, so the near term earnings story still leans on cost control and mix rather than breakaway growth.
The key short term catalyst is whether Medical can move from patchy profitability into something more consistent while tariffs and foreign exchange stay manageable. The recent earnings release does not radically change that. It suggests progress, but also underlines that external cost pressures and Medical losses remain the biggest operational risk.
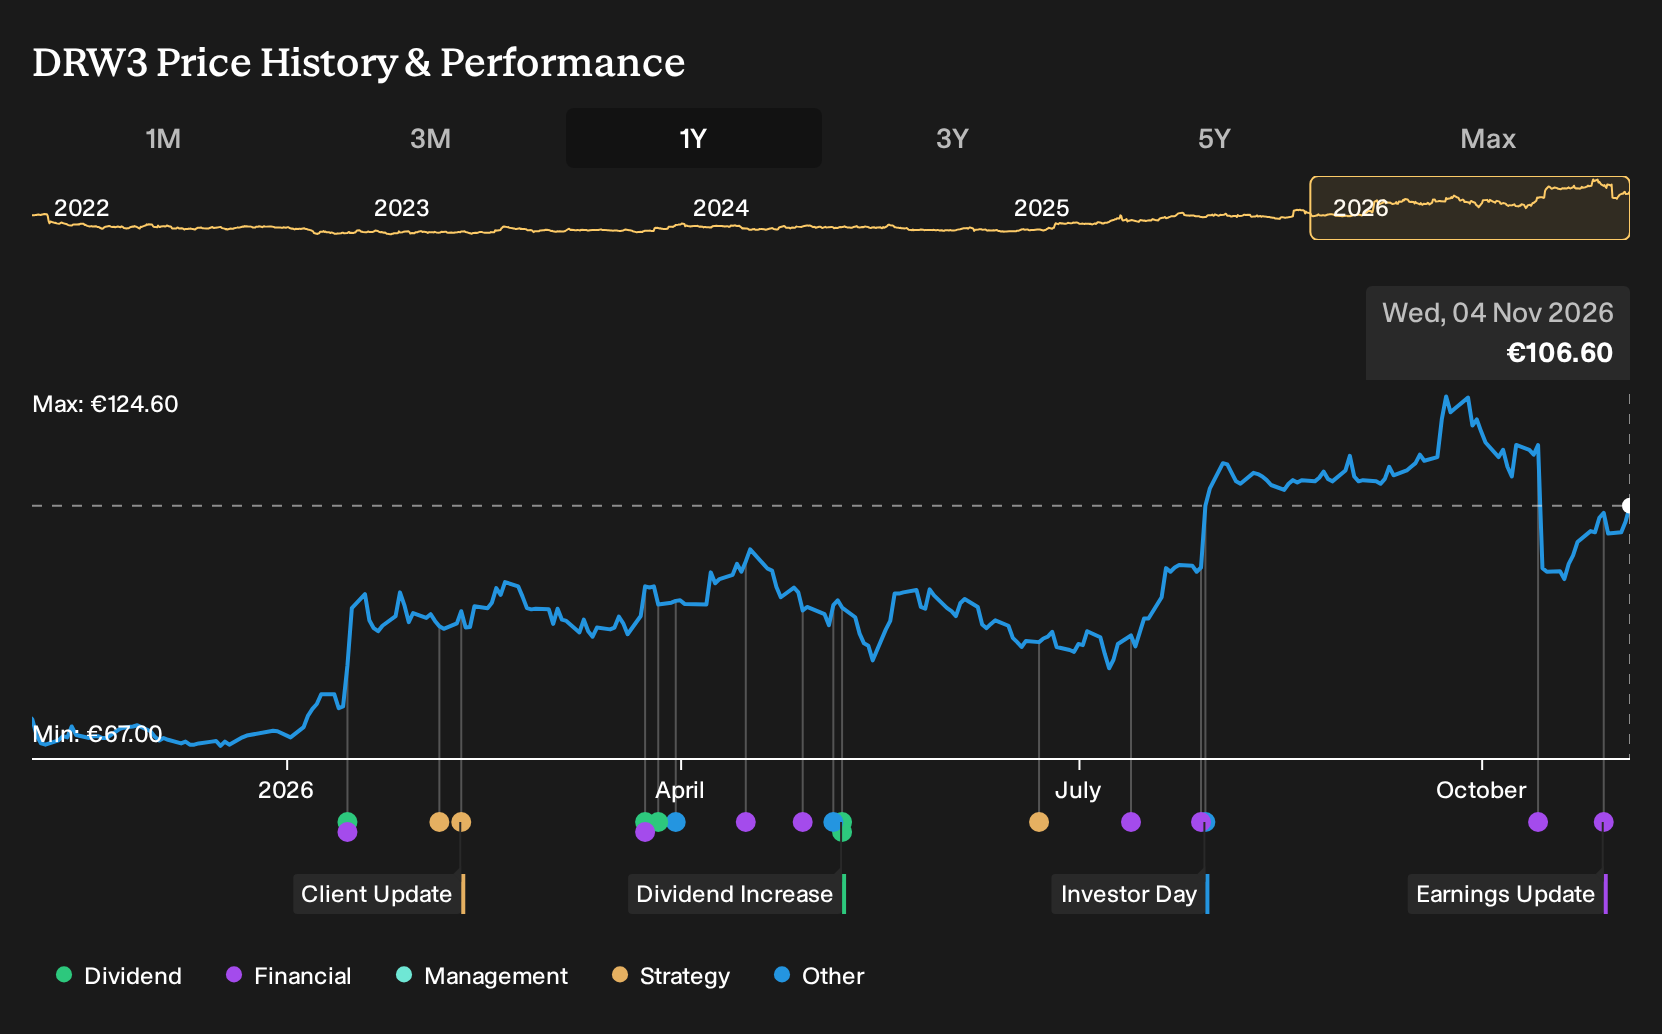
The most directly relevant disclosure is the nine month 2026 earnings update itself. Sales reached €2,453.95 million with net income of €74.95 million compared with €44.85 million a year earlier. For you as a shareholder or potential shareholder, that gap matters because the core narrative is about earnings quality catching up with already established top line scale.
This profit improvement sits alongside earlier commentary about margin focus, tariff refunds and cost measures. It gives some support to the idea that Drägerwerk KGaA can keep offsetting tariff and currency headwinds while pushing Medical toward breakeven and expanding Safety, including defense related projects. The risk is that external pressures or Medical underperformance slow that earnings trajectory just as investors are watching it most closely.
Drägerwerk KGaA's current analyst storyline points to revenues of €4.0b and earnings of €177.1 million by 2029, which assumes roughly 4.1% yearly revenue growth and an earnings increase of about €5.8 million from €171.3 million today.
Uncover why Drägerwerk KGaA's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the more cautious analysts focus on regulation as the swing factor for Drägerwerk KGaA. They were forecasting roughly €4.0b of revenue and earnings of about €188.3 million by 2029, yet still arrived at a €90.0 price target. That more reserved storyline might shift once this latest earnings update is fully absorbed.
Explore 4 other Drägerwerk KGaA fair value estimates, including one that suggests as much as 16% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Drägerwerk KGaA research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Drägerwerk KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Drägerwerk KGaA's overall financial health at a glance.
Looking for more Drägerwerk KGaA style investment ideas?
If Drägerwerk KGaA's story has sharpened your thinking about earnings quality and balance sheet strength, it can help to line it up against other potential opportunities. The Simply Wall St Screener lets you quickly scan for businesses that fit different risk and income profiles, then compare their fundamentals side by side.
- For investors who want potential upside while still paying attention to balance sheet resilience, consider a curated 194 high quality undervalued stocks that pair solid fundamentals with attractive prices.
- If income is a priority and you care about consistency as much as yield, use the screener to narrow in on 216 dividend fortresses that might align with a long term payout focus.
- Readers who lean toward capital preservation first and growth second can filter for 224 resilient stocks with low risk scores and see which businesses currently screen well on financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com