
Missed Aberdeen Group's Rally? Here Is What Early Buyers Saw
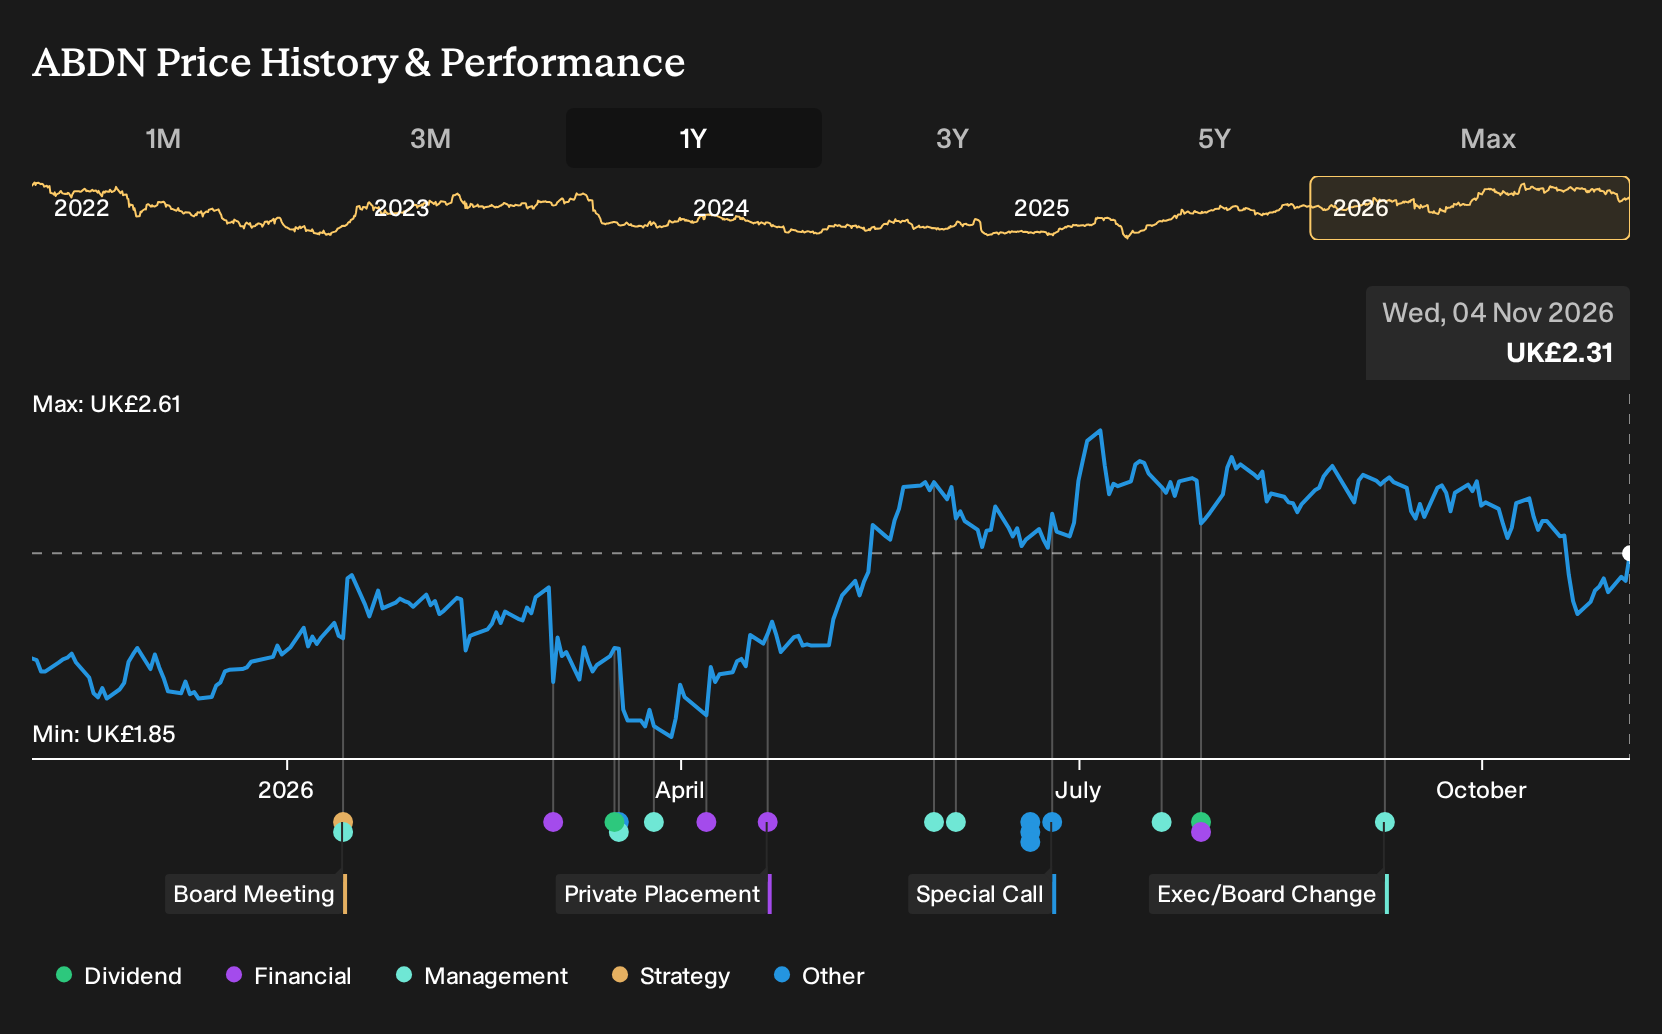
If you had bought Aberdeen Group on 4 November 2025, the last twelve months look very different now. Investors who held Aberdeen Group over the past year are up 20.6%, including dividends. That return lands against a backdrop of rising assets under management, faster interactive investor inflows, and fresh cost targets. The real puzzle is what early buyers were weighing at the time, given the split between growth hopes and margin worries already on record.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Aberdeen Group. Zero in on 14 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Aberdeen Group
The shares cost £2.05 at the start of the period, and anyone looking at Aberdeen Group then had to choose between two very different stories.
On the upbeat side, the bullish Narrative put Fair Value at £2.4. That view leaned on targeted cost savings and capital generation, including the idea that a £35 million annual benefit from the pension surplus could support earlier capital returns.
The opposing bearish case set Fair Value at £1.4. That camp focused on the shift from active to passive investing by partners such as Phoenix and the risk that rising regulatory and compliance costs would steadily crush margins.
What The Evidence Around Aberdeen Group Actually Tested
Aberdeen Group reported assets under management and administration of £579b at the end of September, 4% above the end of 2025, while interactive investor net inflows for the third quarter reached £3b. Those figures supported the focus on asset growth and capital generation. The half year told a tougher story. Revenue moved from £657m in H1 2025 to £677m in H1 2026, yet net income slipped from £247m to £241m and margin fell from 37.6% to 35.6%. The evidence cut both ways.
The lesson is simple. When a story leans on improving quality of earnings, you check whether higher assets or inflows are turning into stronger net margin. For another asset manager, track the link between reported AUM, net flows and the margin line, not just the headline growth in funds under management.
What Today's Aberdeen Group Price Already Bakes In
Aberdeen Group now trades at £2.31, and the selected Narrative’s Fair Value sits below that level. The core argument is that better trends in Interactive Investor and the Investments arm are already recognised in the valuation.
You would be asking whether growth and profitability in those areas can keep offsetting fee pressure and adviser outflows, given the need for ongoing reinvestment and technology spending.
"The main thing that has to go right is that growth and profitability in Interactive Investor and the Investments franchise, supported by cost savings and capital generation, offset ongoing headwinds in the Adviser business. The current valuation implies the share price already reflects sustained delivery on cost efficiencies, capital generation and growth in higher conviction areas, despite delays in the Adviser turnaround and continued scepticism from some analysts."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Aberdeen Group
After Aberdeen Group, you might look one step sideways. Asset managers live on client confidence. Payment networks rely on it too.
Where Aberdeen manages money, another business focuses on how money moves. It runs a closed-loop card network linking spenders and merchants.
That setup turns reputation into practical collateral. Cardholders effectively borrow trust, while merchants accept that promise at the point of sale.
The intermediary stands behind both sides and keeps that confidence functioning smoothly.
Regulators are now testing how that trust is monitored for illicit flows. Their decisions could reshape what it costs to keep this promise working.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 34% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com