
Coca Cola HBC (LSE:CCH) Could Be 2% Undervalued On Upgraded 2026 Outlook
Coca-Cola HBC (LSE:CCH) lifted its 2026 organic revenue guidance after reporting 9% organic revenue growth in Q3 2026. The increase was supported by higher volumes and pricing despite cost pressures and disruptions in Ukraine.
The upgraded guidance and Q3 trading update have come alongside strong share price momentum. Coca-Cola HBC’s stock has a 30.94% year-to-date share price return and a 43.67% one-year total shareholder return, which points to building optimism around execution and risk.
See how Coca-Cola HBC’s upgraded outlook compares with other consumer stocks showing strong fundamentals by using the hand-picked list of solid balance sheet and fundamentals (10 results) as a starting list.
Coca-Cola HBC now has upgraded guidance and a sharply higher share price, which signals confidence in the story. The harder question is whether that momentum is already fully reflected in what you pay today.
Most Popular Narrative: 2% Undervalued
The most followed narrative pegs Coca-Cola HBC’s fair value at £50.55, slightly above the last close of £49.34. This implies only a modest valuation gap and leans on a specific growth story to justify even that small difference.
The accelerated expansion and strong volume growth in high-potential emerging markets, with recent low double digit and low teens volume gains in Nigeria and Egypt and further opportunity in markets such as South Africa, Kenya, Ethiopia and Tanzania through the planned CCBA acquisition, keep Coca-Cola HBC exposed to additional revenue and earnings growth from a larger African footprint.
See why 48 investors see Coca-Cola HBC as 2% undervalued.
Result: Fair Value of £50.55 (UNDERVALUED)
Still, the story can break if energy related cost pressure keeps COGS per case rising, or if new sugar taxes hit Coca-Cola HBC’s core sparkling portfolio.
Find out about the key risks to this Coca-Cola HBC narrative.
Another View On Coca-Cola HBC’s Valuation
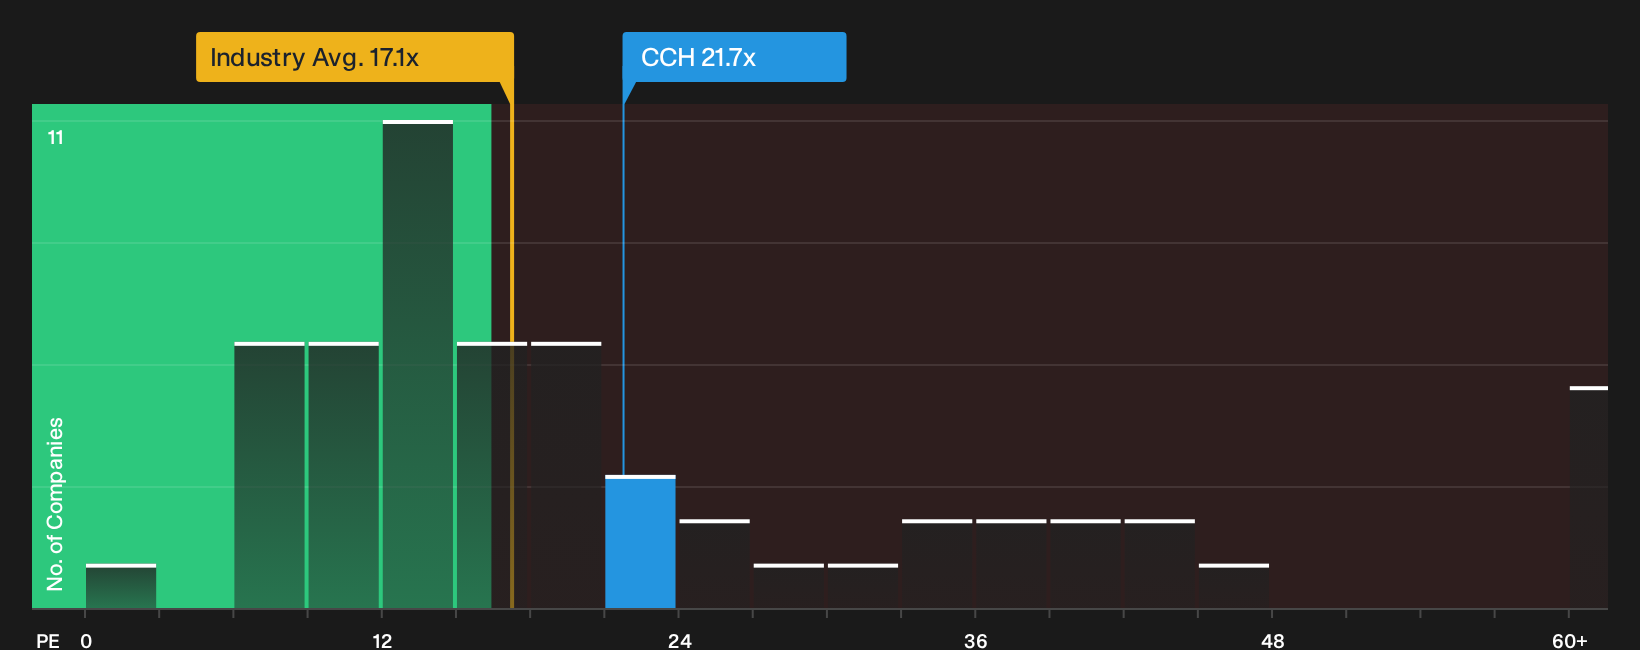
The fair value narrative points to Coca-Cola HBC being around 2% undervalued at £50.55. The market ratio picture is less clear. The P/E of 21.7x is below the Beverage industry on 35.7x and below peers at 26.1x, yet still above its own 23.9x fair ratio anchor. That mix of discount and premium raises a simple question for investors: Is this a margin-of-safety story or a full-price quality ticket?
To unpack what those ratios imply for upside risk and downside protection, review the detailed valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Coca-Cola HBC’s value story. If you want to move fast and build your own view, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Coca-Cola HBC?
If Coca-Cola HBC has sharpened your focus on quality and pricing power, do not stop here. The broader market still holds plenty of underappreciated setups.
- Target reliable compounding by using the 3 dividend fortresses that could suit investors who want income without drifting too far out on the risk curve.
- Hunt for mispriced quality with the 14 high quality undervalued stocks to see which solid businesses the market currently prices at a discount to fundamentals.
- Limit nasty surprises by scanning the 5 resilient stocks with low risk scores that filters for companies with sturdier financial profiles and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com