
ServiceNow (NOW) Stock May Look Fully Priced Despite The Earnings Miss
ServiceNow has seen its share price retreat sharply over the past year, and the slide has put a fresh spotlight on whether the current valuation is still backed up by the company’s earnings power. With the stock under pressure and sentiment swinging around AI automation and competition, the key issue for you is what today’s price really reflects about the underlying profit stream.
- The share price has fallen 38.2% over the past year, which puts the recent earnings record under closer scrutiny as investors reassess what level of profitability they are paying for.
- Recent earnings missed market expectations and triggered a steep selloff, which can reshape assumptions about future margins and how much earnings growth the market is willing to factor into ServiceNow’s valuation.
- Your read on ServiceNow is one view; the desks covering it have another. See what analysts think ServiceNow's shares could be worth.
For investors, the debate is whether ServiceNow’s current share price is adequately supported by the earnings it is generating today and what those profits suggest about the business from here.
If you are reassessing ServiceNow after this earnings shock and AI competition, it can help to cross check it against a focused list of 53 AI infrastructure stocks.
Is ServiceNow Getting Expensive on Earnings?
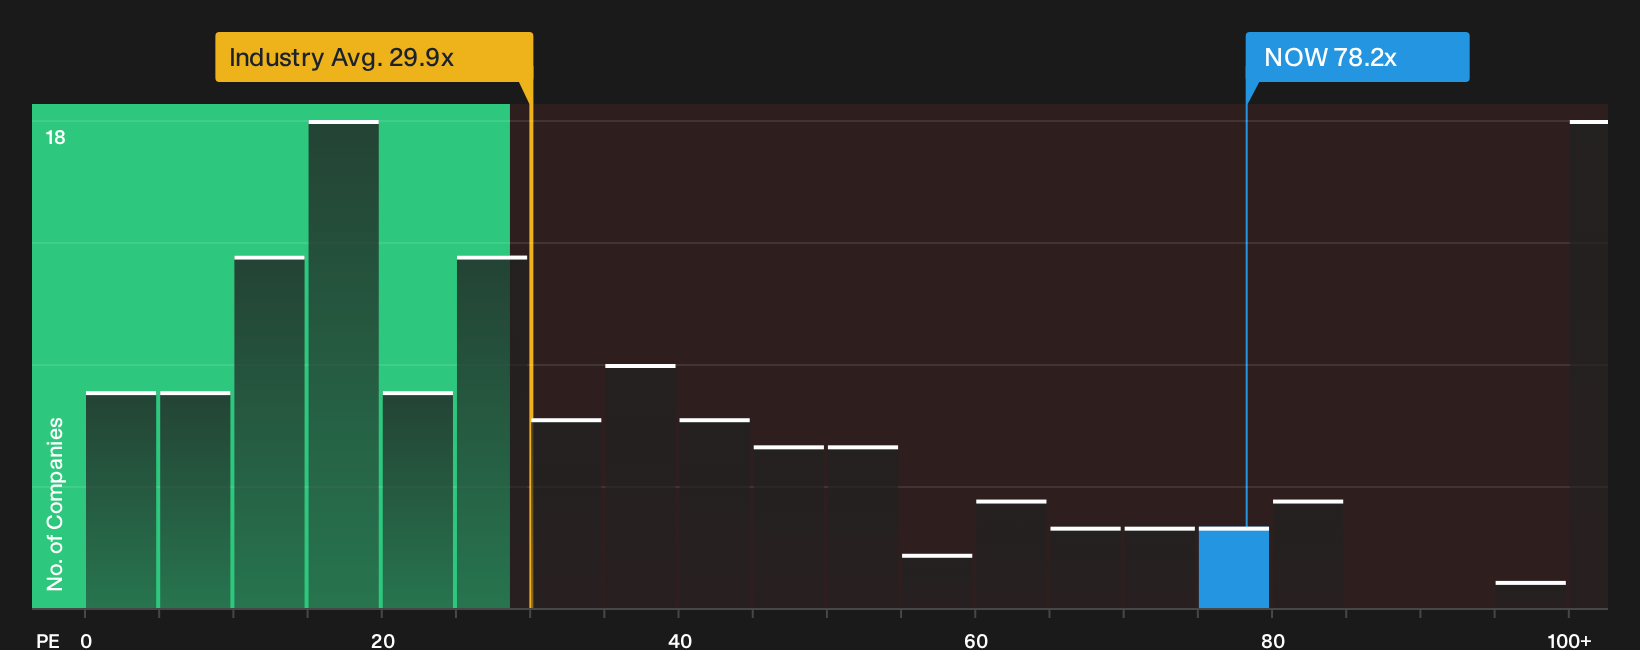
P/E fits ServiceNow because investors focus heavily on current and upcoming earnings for large, established software platforms. Right now, the stock trades on a P/E of 78.2x, which is markedly higher than the Software industry average of 29.9x and the peer average of 25.7x. That kind of gap means buyers are paying a sizeable premium for each dollar of profit relative to many other listed software businesses.
The fair value framework that adjusts for ServiceNow’s own growth profile, profitability and risk points to a lower multiple than today’s level. On this lens the shares screen as overvalued rather than cheap. Despite the sharp reaction to the recent earnings miss and softer guidance, the current P/E still embeds expectations that are richer than both the tailored fair mark and broad peer groups. You would therefore need strong conviction in the durability of ServiceNow’s earnings power for this premium to feel comfortable. Explore the numbers behind ServiceNow's P/E valuation.
The ServiceNow Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation debate around ServiceNow leaves off. They spell out which growth, margin and earnings paths would make the shares look meaningfully richer or cheaper than today’s price on the Community page. Each scenario links a specific fair-value estimate to a clear story about ServiceNow's possible catalysts and risks so you can track over time which version of events the business is actually moving toward.
The ServiceNow community is split between those who see an execution engine for enterprise AI and those who think AI expectations are already baked into the price.
Bull case: 36% undervalued
"ServiceNow is moving from being the system of record for enterprise workflows to becoming the system of action for enterprise AI ..."
Discover why this Narrative puts ServiceNow at 36% undervalued.
Bear case: 18% overvalued
"Current numbers and commentary imply a valuation that already reflects expectations for ServiceNow to continue growing subscription revenue around the low 20% range ..."
Explore why this Narrative puts ServiceNow at 18% overvalued.
One more ServiceNow check that sits beside the earnings math
Price, profits and AI stories only go so far if you do not know who is steering ServiceNow and how their incentives line up with your interests. See who runs ServiceNow and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com