
Hinge Health (HNGE) Stock Looks About Right On A 166% Run
Hinge Health has delivered a sharp run in its share price, and after such a move the real issue is whether the current market value lines up with what its earnings suggest the stock is worth. With the Discounted Cash Flow (DCF) lens focused squarely on those profits, investors are asking if the recent enthusiasm matches the income the business is generating.
- Over the past year the stock has returned 166.3%, which puts real weight on the question of whether that gain is grounded in the level and trajectory of its earnings.
- Record profitability and a rapidly expanding client base may support expectations for stronger future earnings, which directly feed into any estimate of intrinsic value built on cash the company can earn over time.
- The analysts covering Hinge Health have run their own numbers. See what analysts think Hinge Health's shares could be worth.
The issue now is whether Hinge Health's current share price is justified by its earnings once that record is weighed against what the Discounted Cash Flow (DCF) view of intrinsic value implies.
If you are weighing Hinge Health's recent 166.3% one year return against what its earnings justify, a focused stock screen can broaden your options through 34 high quality undervalued stocks.
Does Hinge Health Look Fairly Valued on Earnings?
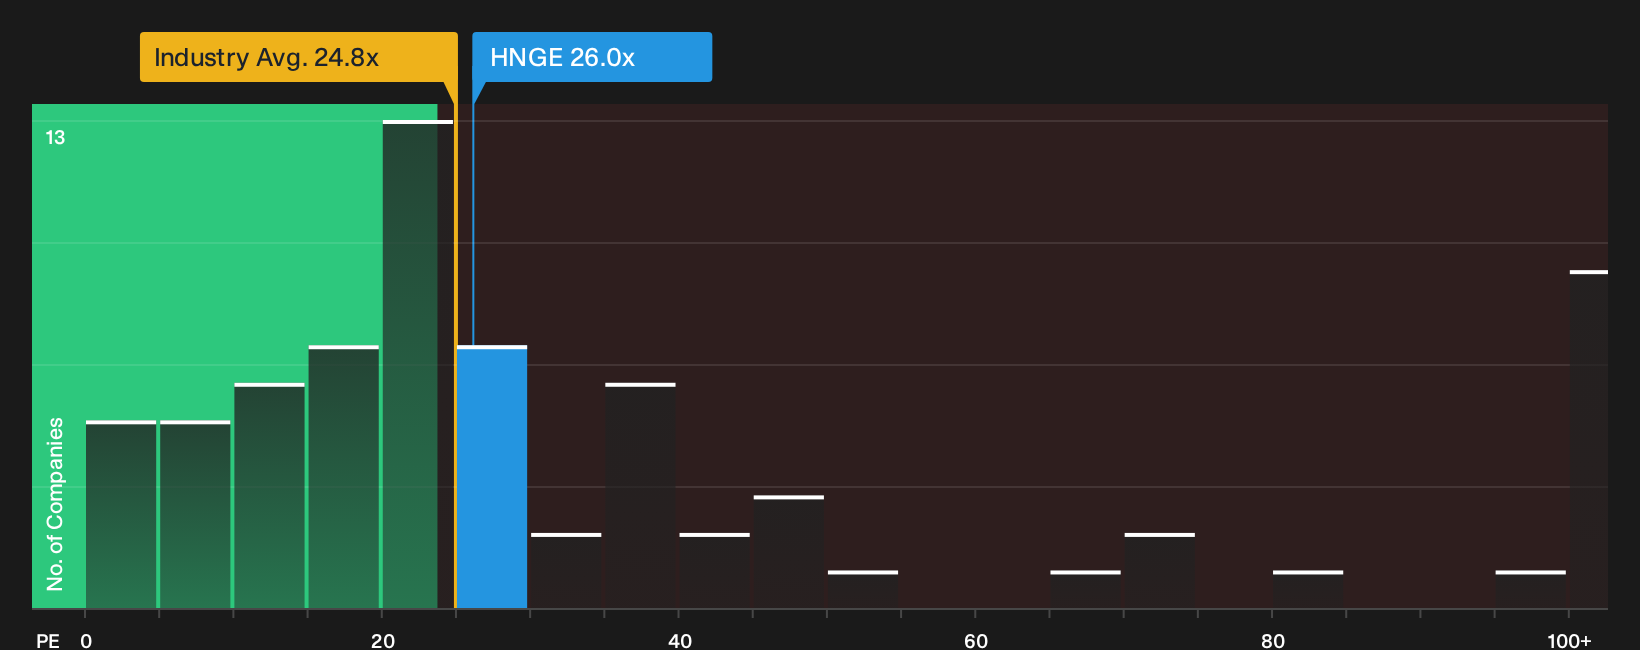
The P/E ratio works well for Hinge Health because the business is now reporting profits that give a clearer anchor for the share price. On this measure, Hinge Health trades on roughly 26.0x earnings, which is below the peer average of about 61.7x and close to the broader healthcare sector on roughly 24.8x. A fair value model that blends the group’s growth profile, margins, size and risk points to a slightly higher multiple, so the current P/E sits modestly under that tailored benchmark.
Because record Q3 2026 earnings and raised guidance have already reset expectations, the current P/E suggests investors are paying a premium to the sector but not to the more aggressive end of specialist peers. For you as a shareholder or prospective buyer, the key question is whether the recent profitability and client growth justify Hinge Health trading near this level rather than closer to high-growth peers, and whether that gap could close over time. Explore the numbers behind Hinge Health's P/E valuation.
The Hinge Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Hinge Health valuation puzzle leaves off by spelling out which assumptions about growth, profitability and future earnings would need to hold for the shares to be worth materially more or materially less than today’s price. Each narrative treats fair value as a specific thesis about how Hinge Health's business could play out over time, and you can revisit it as new information arrives on the Community page.
Community views on Hinge Health split between those who see more upside in the current valuation and those who think expectations already price in much of the story.
Bull case: 17% undervalued
"Hinge Health has quickly distinguished itself as one of the most successful IPOs of 2025, combining rapid revenue growth, widening margins, and a scalable AI‑driven care model…"
Discover why this Narrative puts Hinge Health at 17% undervalued.
Bear case: 6% overvalued
"The long-term success of Hinge Health depends on sustained employer and health plan enthusiasm for digital MSK solutions…"
Explore why this Narrative puts Hinge Health at 6% overvalued.
One more piece of the Hinge Health puzzle to check before you act
Market ratios and recent profitability anchor where Hinge Health trades today, but professional analysts have mapped out where they expect this business to be in a few years. That projected path is the missing comparison. Explore where analysts expect Hinge Health to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com