
KKR (KKR) Eyes STT GDC India Sale, Is The Stock Fully Priced?
Reports that KKR (KKR) and fellow shareholders are exploring a multi billion dollar sale of STT GDC India are putting fresh attention on how the asset manager recycles capital and manages data infrastructure exposure.
Investors have responded quickly to the STT GDC India sale reports, with KKR’s share price up 5.57% on the day to US$101.34 and posting a 12.65% 1 month share price return, although year to date the share price return is down 21.38%.
Scan how KKR’s move in data centers compares with other asset managers hunting infrastructure and cash flow resilience by reviewing the curated list of solid balance sheet and fundamentals (25 results) in this space.
The STT GDC India headlines have jolted KKR’s share price higher in a hurry. Do you treat this as an early entry on a reset asset manager, or wait for the excitement around data centers and recycled capital to cool before pricing really makes sense?
Most Popular Narrative: 20% Overvalued
Kkapirey’s long form narrative pegs KKR’s fair value at US$84.45 per share, which sits well below the latest close at US$101.34 and frames the current data center excitement as only part of a much bigger long term story.
Después de incorporar 1Q 2026, la tesis se refuerza más que cambia: KKR está evolucionando de un gestor de private equity a una plataforma de capital permanente con múltiples motores de crecimiento. En términos simples:
• Antes: gestor de fondos
• Hoy: gestor + asegurador + inversor estructural
• Mañana: posible conglomerado de capital global. La implicación final, en tono Buffett: Si la compañía continúa priorizando disciplina en capital, crecimiento del ingreso recurrente y alineación, la variable determinante para el inversor no será el próximo trimestre, sino la próxima década.
See why 14 investors see KKR as 20% overvalued.
Result: Fair Value of $84.45 (OVERVALUED)
Still, this narrative around KKR could be shaken if private credit losses hit fund fees harder than expected, or if fundraising for new vehicles materially slows.
Find out about the key risks to this KKR narrative.
Another View On KKR’s Valuation
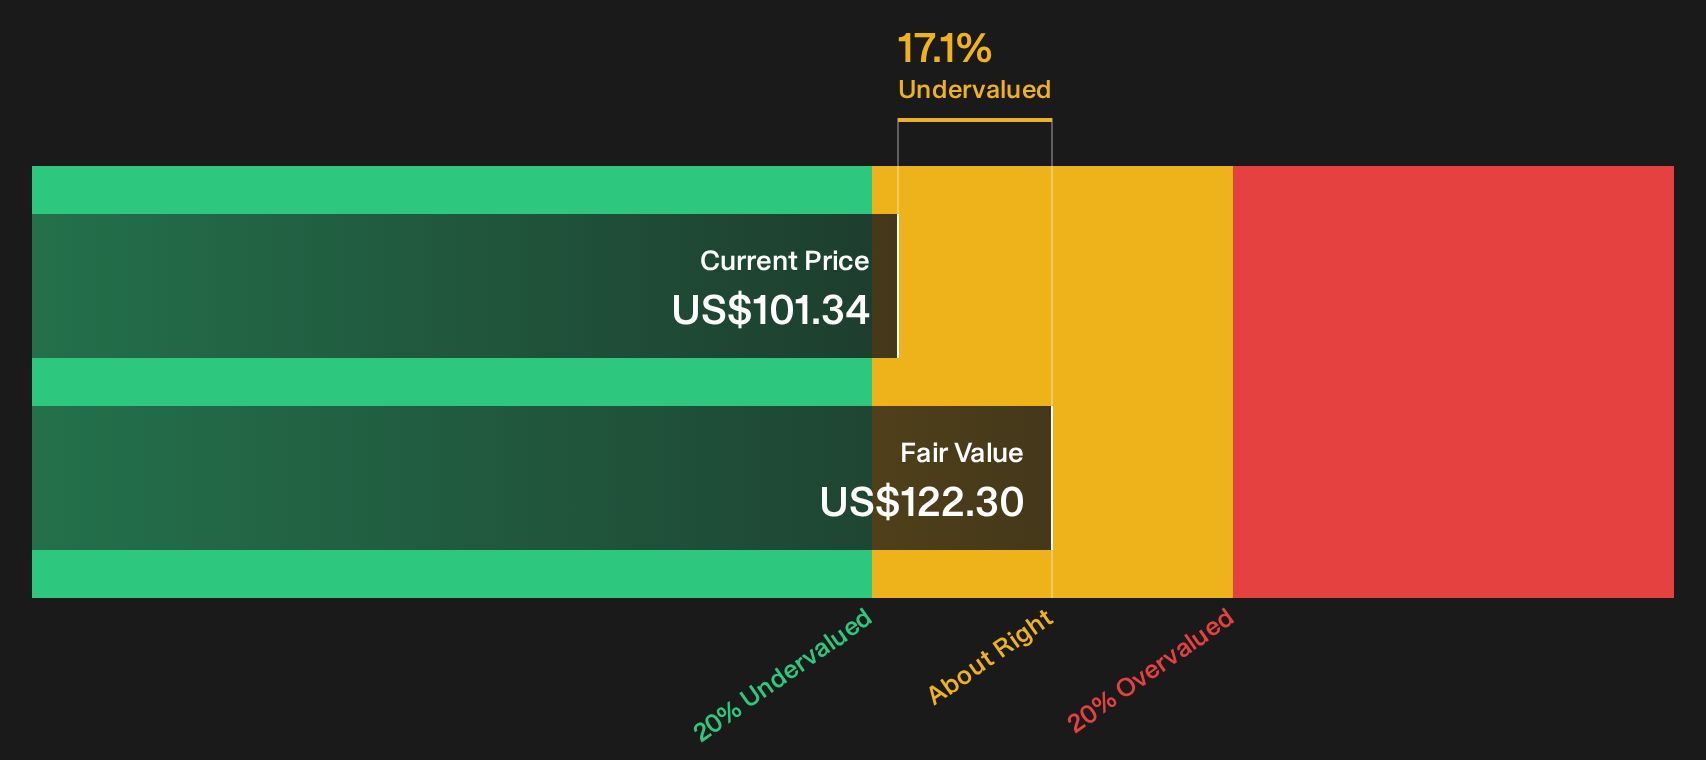
The long form narrative pegs KKR at a fair value of US$84.45 per share and calls the stock overvalued at US$101.34. Our DCF model points in a different direction. It values KKR at about US$122.30, which implies the shares trade at a discount. Which story do you trust more: the market pricing or the cash flow math?
To see how that cash flow framework works in practice, take a closer look at how the SWS DCF model treats recurring earnings, insurance float and stressed scenarios for KKR, then compare it with your own expectations for the next decade. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If sentiment around KKR feels split after these valuation signals, move quickly to pressure test the upside drivers that have investors optimistic. To weigh those potential bright spots against your own expectations, review the 3 key rewards.
Looking for more investment ideas beyond KKR?
If KKR has you thinking differently about capital recyclers and compounding, do not stop here. Put a few fresh filters to work and widen your opportunity set.
- Target dependable upside by scanning a 34 high quality undervalued stocks that screens for quality businesses trading below their assessed worth before other investors catch on.
- Prioritize resilience first by reviewing a 31 resilient stocks with low risk scores focused on companies with sturdier balance sheets and more measured risk profiles than the broader market.
- Hunt for tomorrow’s standouts early with a 19 high quality undiscovered gems built to surface under-followed stocks that still show strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com