
Intact Financial Stock In Focus After Earnings Fall
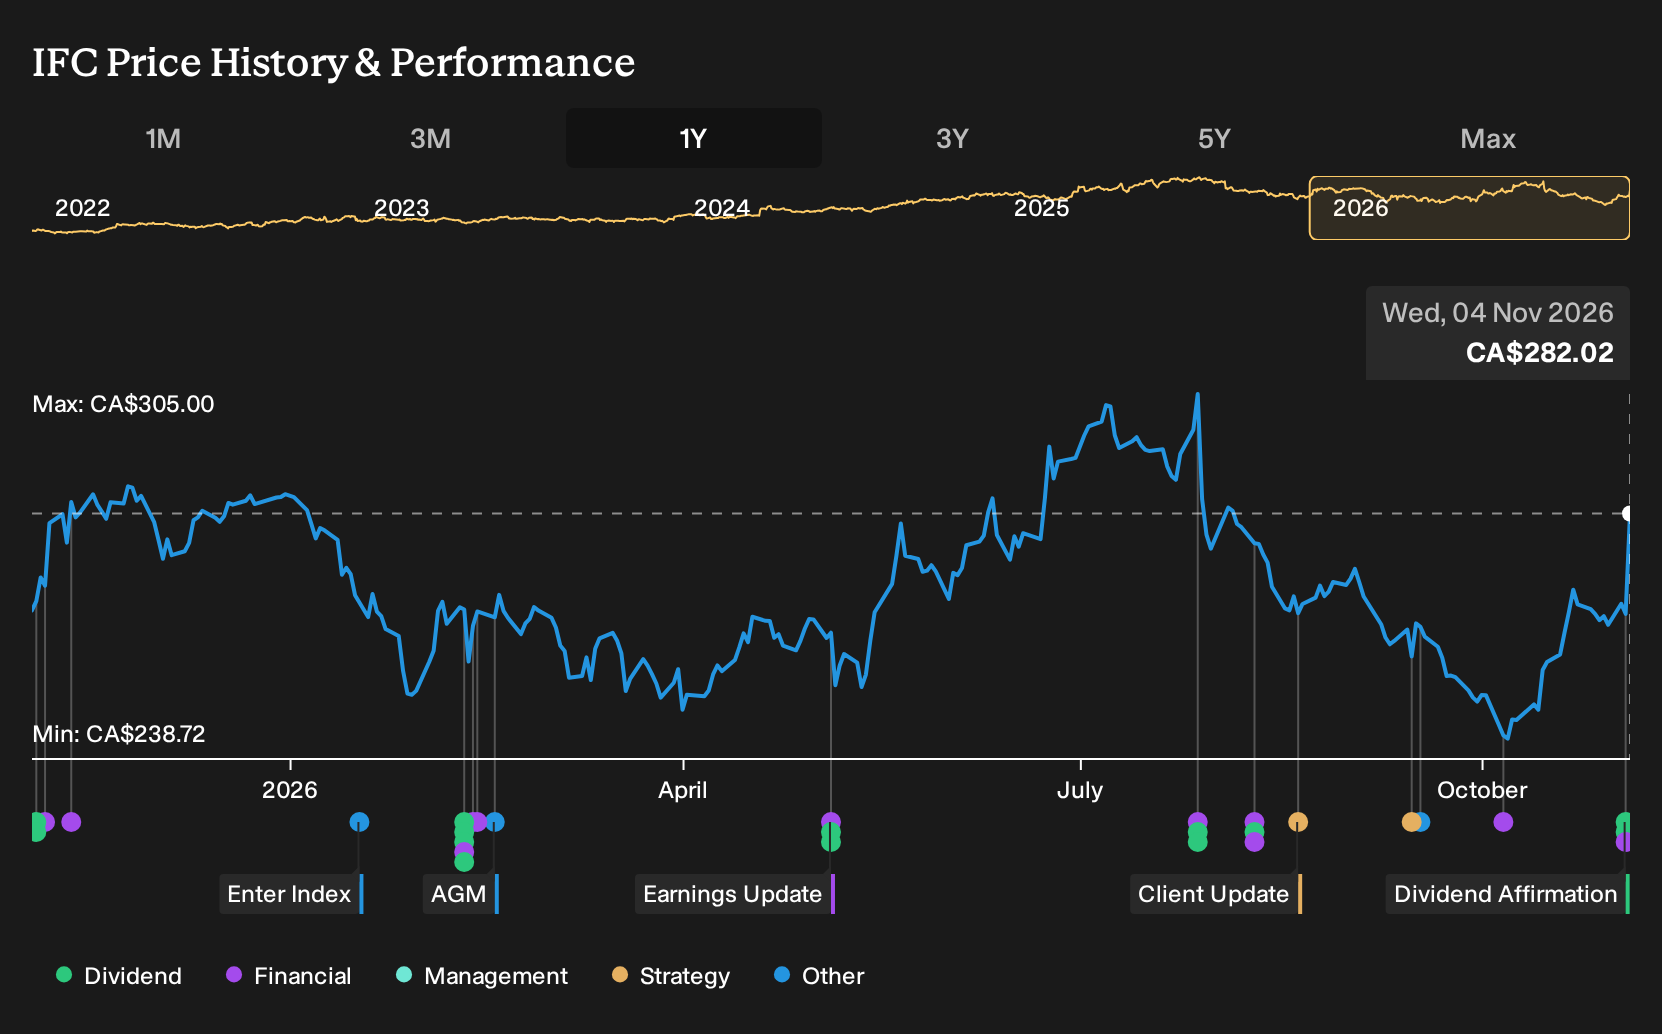
- Intact Financial reported third quarter net income of C$562 million and basic EPS from continuing operations of C$3.03, compared with C$861 million and C$4.73 a year earlier. Its board also approved quarterly common and preferred share dividends payable on December 31, 2026.
- The combination of lower earnings for both the quarter and year to date, alongside ongoing capital returns through dividends and C$397 million of share buybacks, illustrates how Intact Financial is balancing profit pressure with shareholder distributions.
- Investors may now consider how Intact Financial's weaker quarterly earnings per share could influence the longer term investment narrative around the insurer.
Compare Intact Financial's mix of earnings pressure and steady payouts with a curated group of insurers and financials by scanning the 9 resilient stocks with low risk scores, which prioritize resilient balance sheets and controlled risk profiles.
Intact Financial Investment Narrative Recap
To own Intact Financial, you need to be comfortable with an insurer that leans on disciplined underwriting, technology driven efficiency and careful capital use, while living with real exposure to catastrophe losses and UK&I execution risk. The latest quarter showed lower net income and EPS, so the near term focus sits on how quickly loss ratios and UK&I combined ratios can be stabilised.
The most important short term catalyst is operational follow through in personal lines pricing, specialty underwriting and UK&I remediation. The biggest risk is that elevated catastrophe losses and UK&I volatility persist. The recent earnings and capital return update affects sentiment, but does not appear to change these core drivers in a material way.
The board’s decision to affirm a C$1.47 quarterly dividend on Intact Financial common shares looks most relevant here because it directly interacts with that earnings pressure. Investors now have to weigh a steady cash distribution against a quarter where net income and EPS from continuing operations were below the prior year.
This payout, alongside approved preferred share dividends and completion of C$397 million in buybacks, keeps capital returns visible while the business works through catastrophe and UK&I challenges. The key question for you is whether underwriting execution, technology benefits and specialty growth can support both these dividends and the operational catalysts that matter most.
Intact Financial's narrative projects CA$26.3b revenue and CA$3.0b earnings by 2029. This assumes revenue remains fairly flat over time and implies a CA$0.2b earnings decrease from CA$3.2b today.
Discover why Intact Financial's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about C$309 and C$432, so opinions on Intact Financial span a wide valuation band. You are weighing these retail viewpoints against live issues like catastrophe losses, UK&I execution work and ongoing buybacks, which can all reshape how future results are assessed.
Explore 2 other Intact Financial fair value estimates, including one that suggests it could be worth just CA$308.62.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Intact Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Intact Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to review Intact Financial's overall financial profile at a glance.
Looking for more investment ideas beyond Intact Financial?
If this update on Intact Financial has sharpened your questions about risk, income and valuation, it can help to line it up against a broader watchlist. The Simply Wall St Screener lets you quickly filter for different profiles so you can compare this insurer with other opportunities that match your own comfort level.
- If you want potential mispricing combined with quality, review a curated 5 high quality undervalued stocks that pair solid fundamentals with attractive valuations.
- If dependable income is higher on your agenda, scan a focused set of 3 dividend fortresses that offer elevated yields with an eye on sustainability.
- If balance sheet strength matters most to you, start with a list of solid balance sheet and fundamentals (6 results) that already screens for financial resilience and fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com