
How Lower Output Guidance Will Impact Capstone Copper Stock Investors
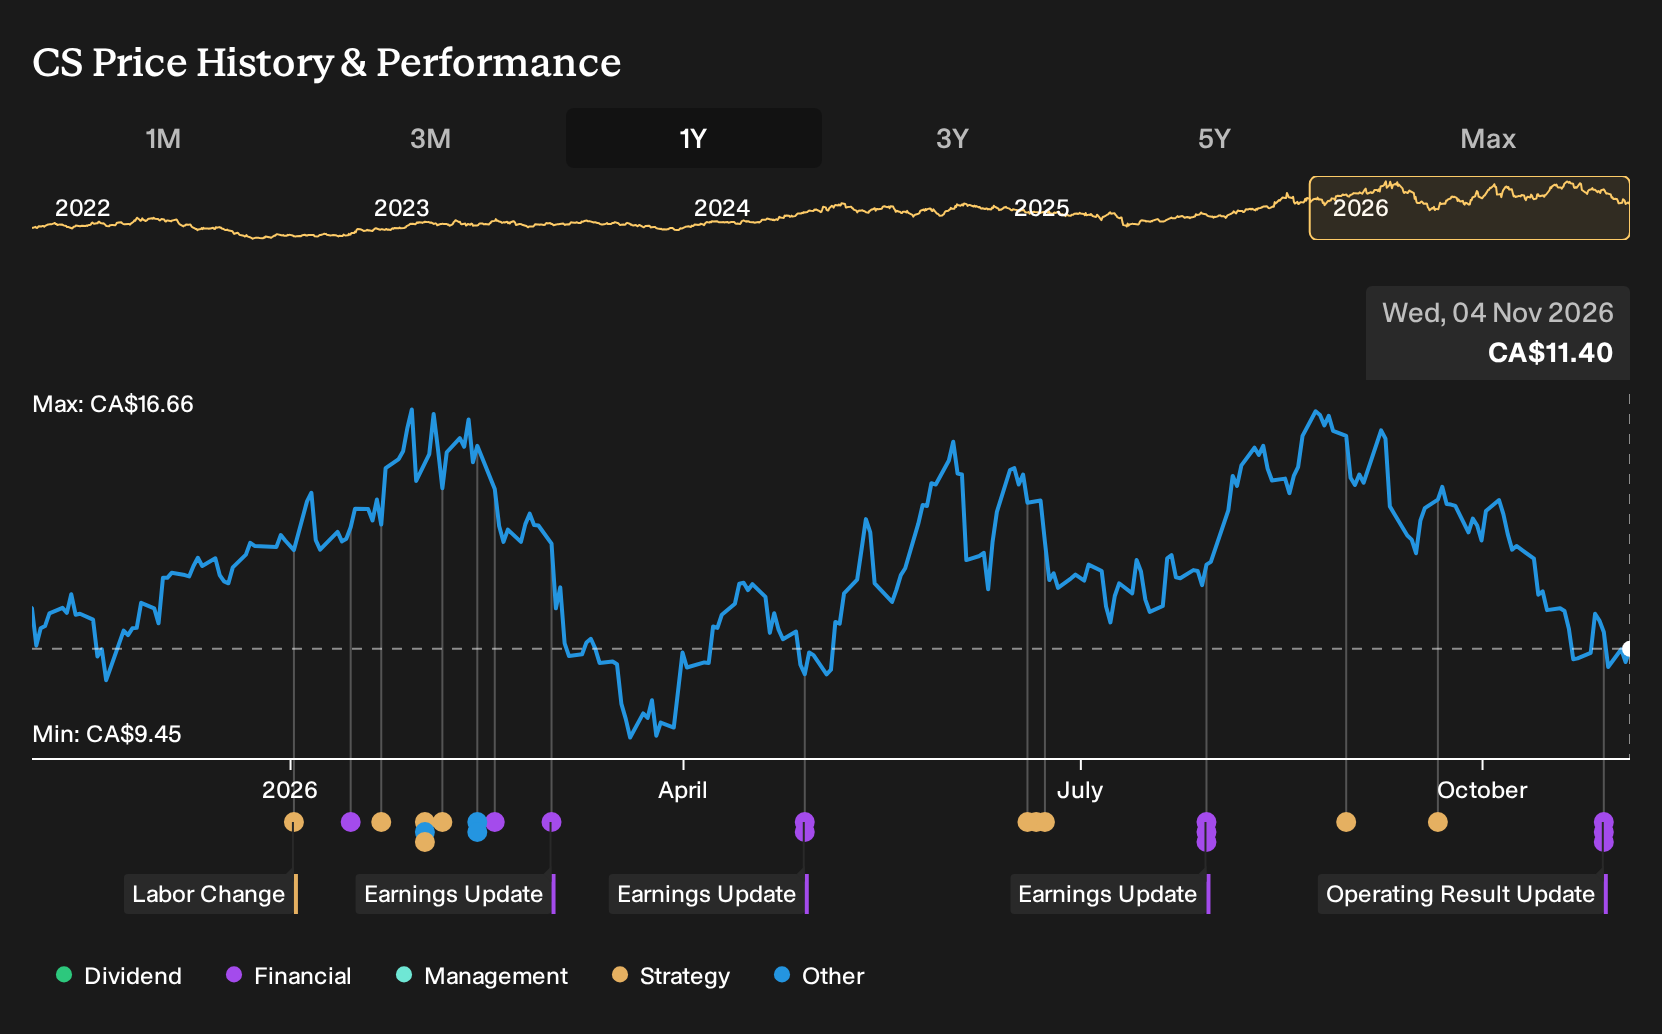
- Capstone Copper reported Q3 2026 copper output of 45,218 tonnes, down from 55,280 tonnes a year earlier, alongside lower quarterly net income despite higher sales. The company now expects 2026 production to land at the low end of its 200,000 to 230,000 tonne guidance range.
- The miner is counting on a stronger Q4 after completing the Mantoverde Optimized sulphide concentrator tie in, while using zero cost copper collars and sulfuric acid driven cathode flexibility to manage margins on higher cost production.
- We will now assess how Capstone Copper's investment narrative is affected by weaker Q3 production and earnings, together with low end 2026 guidance.
Compare Capstone Copper's production story with other potential copper beneficiaries by scanning a curated list of 16 top copper producer stocks that could react differently to the same commodity backdrop.
Capstone Copper Investment Narrative Recap
To own Capstone Copper, you need to be comfortable with a concentrated group of large mines and a production profile that leans heavily on projects like Mantoverde and Mantos Blancos. The latest quarter underlined that point, with Q3 copper volumes and net income both weaker year on year, and full year guidance now tracking to the low end of the 200,000 to 230,000 tonne range.
The key near term catalyst is execution on a stronger Q4 as the Mantoverde Optimized sulphide concentrator tie in moves into regular operation. The biggest current risk is that operational hiccups or grade issues at a few core sites again restrict output, which could stress costs and cash coverage of growth spending if production softness persists.
The production guidance update is the most relevant new piece of information for you as a shareholder. Management now expects 2026 copper output to finish at the low end of the 200,000 to 230,000 tonne target, with a heavier lift planned for Q4 once the Mantoverde Optimized tie in is complete and copper grades improve at Mantoverde and Mantos Blancos.
The same guidance also frames 2027 as a year of similar cathode production, given current sulfuric acid pricing, with some room to flex output if reagent costs ease. When you layer in the recently added zero cost copper collars for about 6,000 tonnes of 2027 cathode output, you get a clearer picture of how Capstone Copper is trying to protect margins while it pursues volume recovery and prepares for larger projects such as Santo Domingo.
Capstone Copper's current analyst narrative points to revenue of $3.6b and earnings of $755.1m by 2029, based on assumed yearly revenue growth of 10.9%. That outlook implies an earnings increase of about $279.7m from the $475.4m reported today.
Uncover why Capstone Copper's fair value indicates a 58% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Capstone Copper focuses on legal risk around Cozamin. The most cautious analysts were assuming slower annual revenue growth of 5.1% to about $3.2b and earnings of $743.9m by 2029. That is a more constrained story, and the latest weak Q3 output could push those expectations even lower or prompt revisions.
Explore 4 other Capstone Copper fair value estimates, including one that suggests as much as 29% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Capstone Copper research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Capstone Copper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Capstone Copper's overall financial health at a glance.
Looking for more investment ideas beyond Capstone Copper?
If the Capstone Copper story has you thinking about portfolio balance, it can help to line it up against other opportunities with very different risk and income profiles using the Simply Wall St Screener.
- For investors who want potential upside with tighter risk controls, start with a set of 9 resilient stocks with low risk scores that score well on resilience and downside protection.
- If you prefer cash flow today rather than waiting on long term copper projects, scan a group of 3 dividend fortresses that aim to combine higher yields with more established payout histories.
- For those hunting for less crowded stories, broaden the watchlist with 9 high quality undiscovered gems that pair solid fundamentals with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com