
Carriage Services (NYSE:CSV) misses Q3 2026 revenue estimates, stock drops 12.1%
Funeral services company Carriage Services (NYSE:CSV) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 2.4% year on year to $100.3 million. The company’s full-year revenue guidance of $417.5 million at the midpoint came in 3.6% below analysts’ consensus estimates. Its non-GAAP profit of $0.59 per share was 25.5% below analysts’ consensus estimates.
For more on Carriage Services, read our free full research report.
Carriage Services (CSV) Q3 2026 highlights:
- Revenue $100.3 million vs S&P analysts’ consensus estimates of $109.5 million (2.4% year-on-year decline, 8.4% miss)
- Adjusted EPS $0.59 vs S&P analysts’ consensus estimates of $0.79 (25.5% miss)
- Adjusted EBITDA $27.71 million vs analysts’ consensus estimates of $32.98 million (27.6% margin, 16% miss)
- Revenue guidance The company lowered its revenue guidance for the full year to $417.5 million at the midpoint from $440 million, a 5.1% decrease
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $2.97 at the midpoint, a 13.8% decrease
- EBITDA guidance $127.5 million at the midpoint for the full year, below analysts’ consensus estimates of $135.3 million
- Operating margin 19.3%, down from 23.4% in the same quarter last year
- Free cash flow margin 18.9%, up from 17.5% in the same quarter last year
- Market capitalization $544.1 million
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Over the last five years, Carriage Services grew its revenue at a weak 2.3% compounded annual growth rate, falling below our standards.
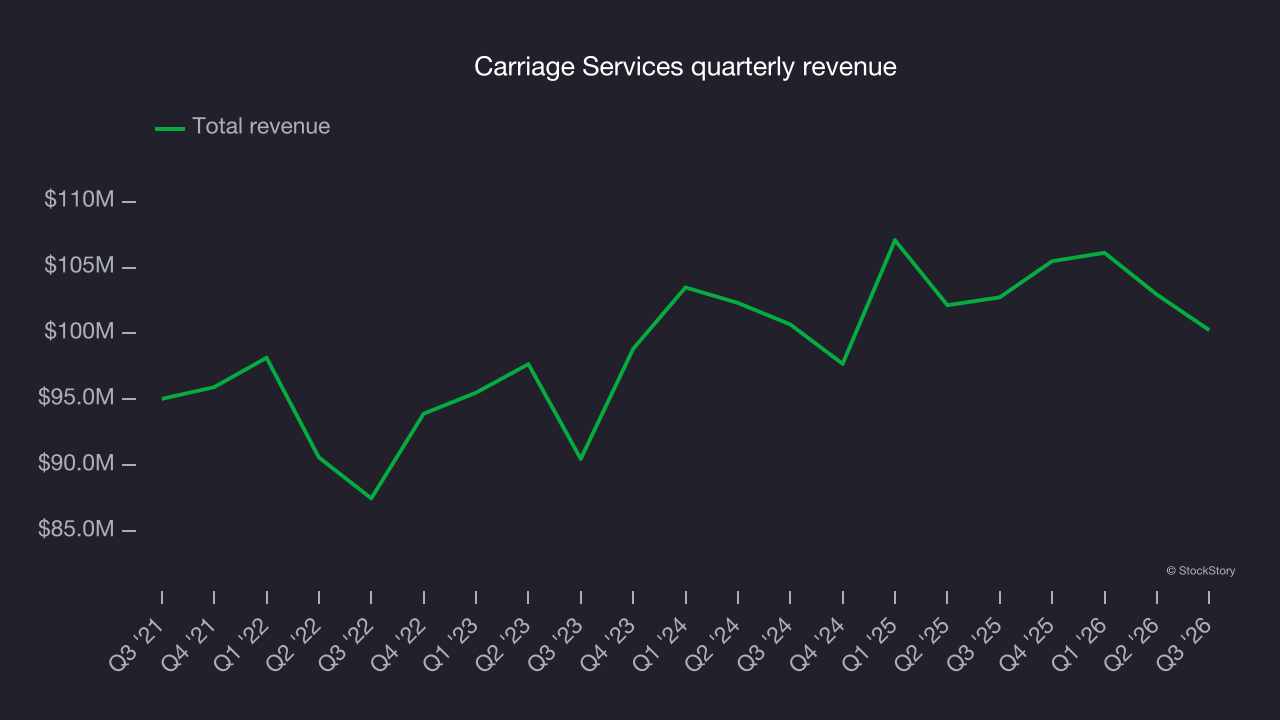
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new product or trend. Carriage Services’s recent performance shows its demand has slowed as its annualized revenue growth of 1.2% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 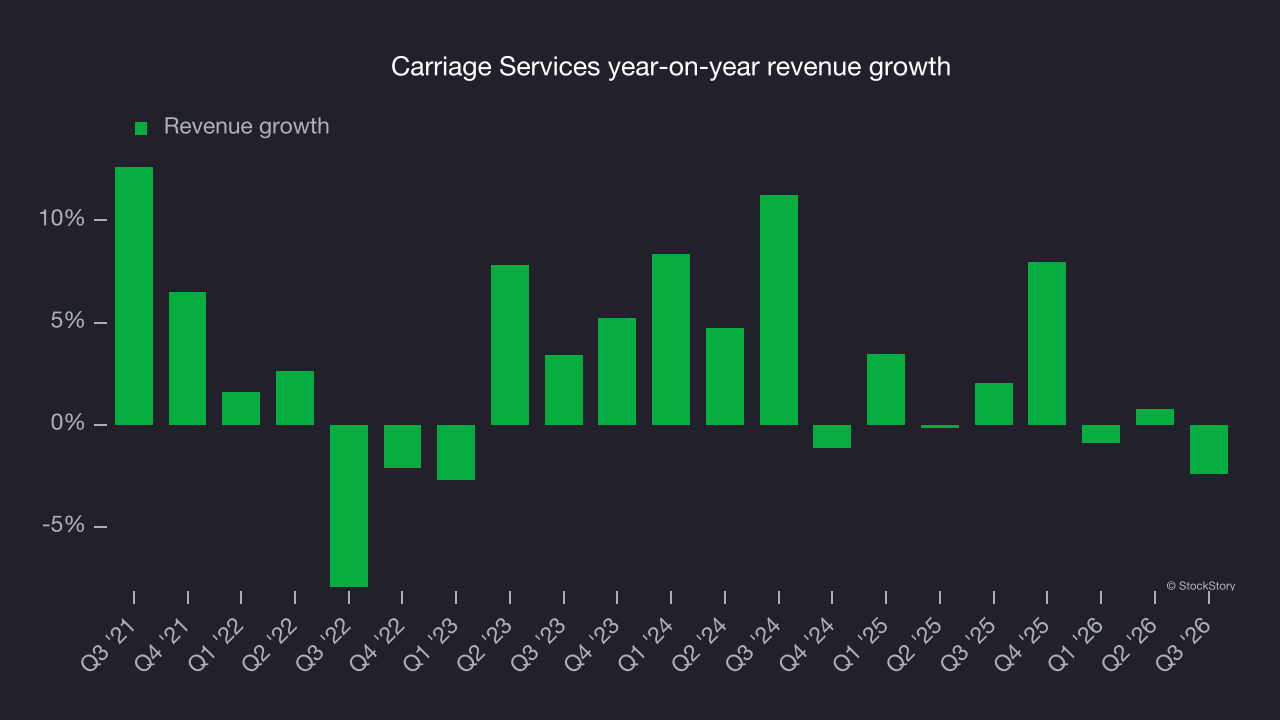
This quarter, Carriage Services missed Wall Street’s consensus estimates and reported an uninspiring 2.4% year-on-year revenue decline, generating $100.3 million of revenue.
Looking ahead, sell-side analysts expect revenue to grow 9.7% over the next 12 months, according to S&P. Although this projection suggests its newer products and services will catalyze better top-line performance, it is still below average for the sector.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Carriage Services’s operating margin has generally stayed the same over the last 12 months, falling short of the increases generally expected from economies of scale and cost efficiency over time.
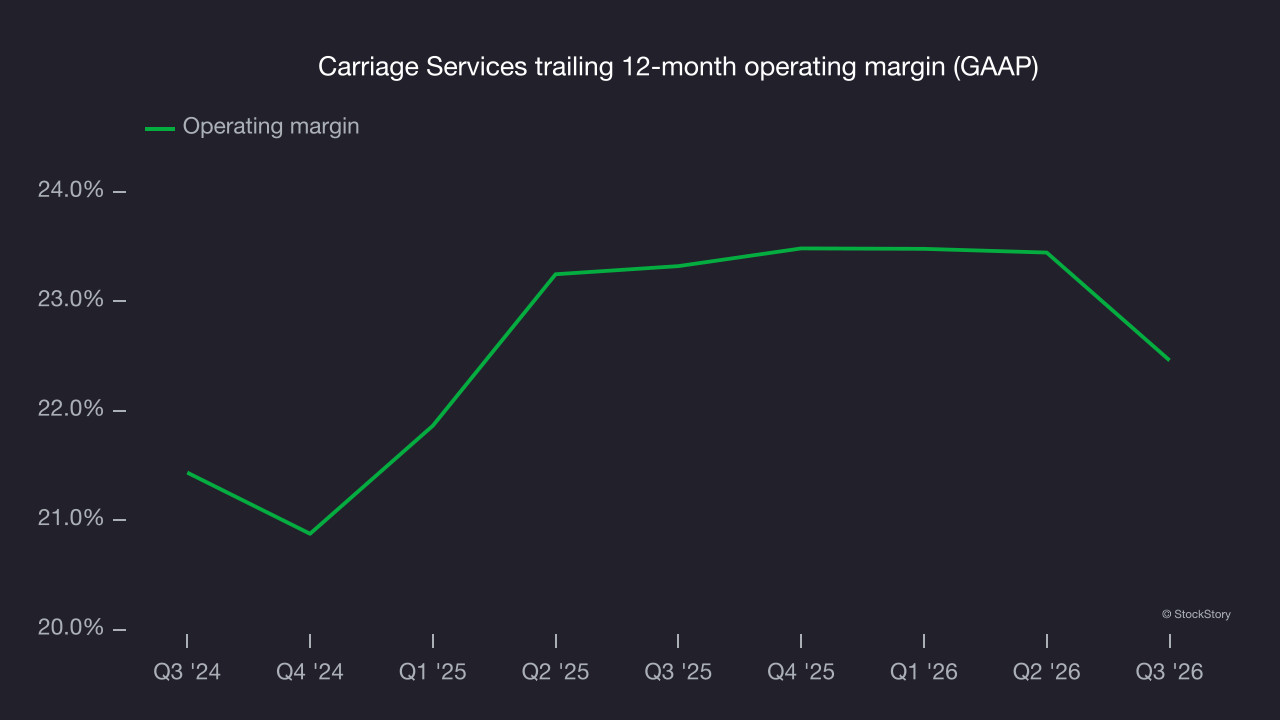
In Q3, Carriage Services generated an operating margin of 19.3%, down 4.1 percentage points year on year. This contraction shows it was less efficient because its expenses increased relative to its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Carriage Services’s flat EPS over the last five years was below its 2.3% annualized revenue growth. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
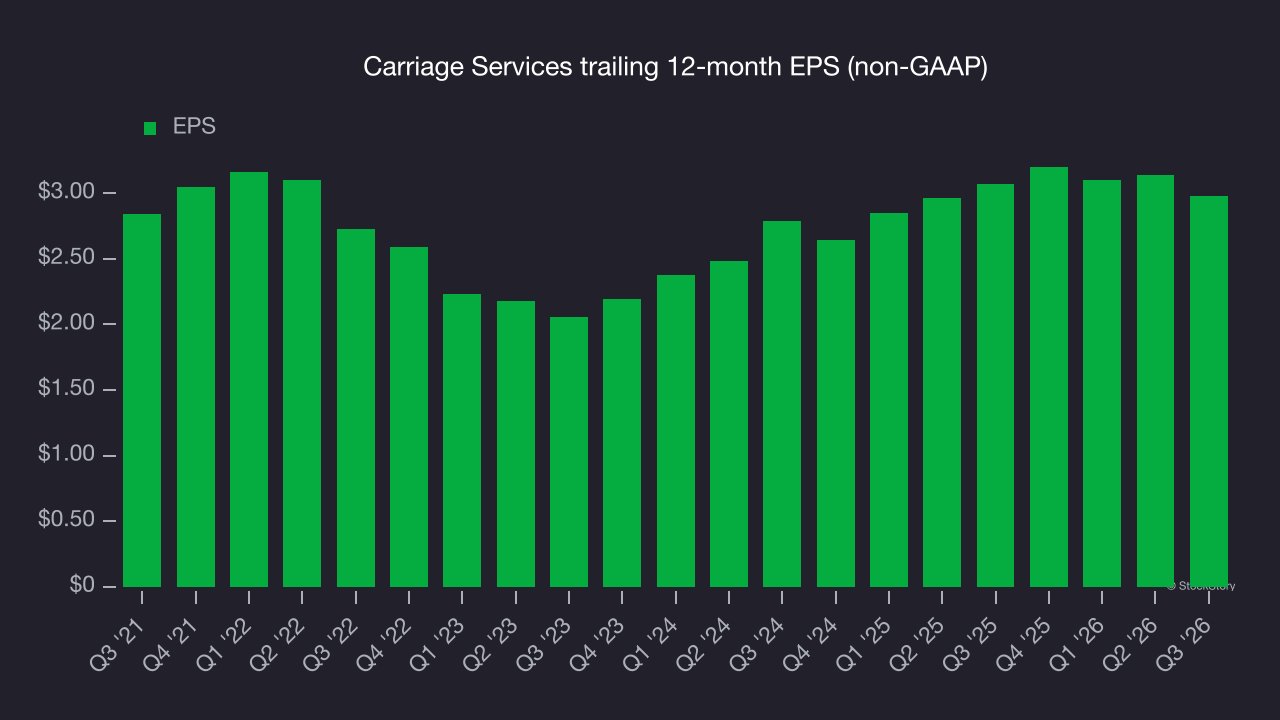
In Q3, Carriage Services reported adjusted EPS of $0.59, down from $0.75 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Carriage Services’s full-year EPS to grow 18.7% from $2.98 to $3.54, according to S&P.
Key takeaways from Carriage Services’s Q3 results
Carriage Services delivered a weaker quarter with few positives, as revenue fell short of Wall Street’s consensus estimates and full-year revenue guidance also missed expectations. Shares plunged 12.1% to $31.66 immediately after the release.
Carriage Services may have had a difficult quarter, but longer-term business quality and valuation matter more than the latest results when deciding whether to invest in the stock. For more on Carriage Services, read the full research report here (it’s free).