
Airtel Africa (LSE:AAF) Could Be 30% Undervalued After Half Year Results
Airtel Africa (LSE:AAF) moved back into focus after reporting half year results on 30 October 2026, alongside an interim dividend declaration and completion of a £109 million share buyback program.
Airtel Africa’s half year update landed against a choppy share price backdrop, with a 1 day share price return of 5.69% and a 7 day gain of 3.03% coming after a 30 day share price decline of 10.24% and a 90 day fall of 16.08% as investors weighed the interim dividend, completed £109 million buyback and recent earnings release. Even with the share price down 22.95% year to date, longer term momentum in total shareholder return remains strong, with 3 year and 5 year total shareholder returns of 166.11% and 148.87%. This suggests the recent pullback contrasts with the broader multi year outcome for holders.
Scan how Airtel Africa compares with other potential rebound candidates by reviewing 14 high quality undervalued stocks with resilient cash flows and balance sheets that have already been vetted for you.
Airtel Africa now trades well below both analyst targets and some intrinsic value estimates. After that sharp year to date pullback, where does a fair price really sit within that wide valuation gap?
Most Popular Narrative: 30% Undervalued
Airtel Africa’s most followed narrative points to a fair value of £3.96 against the last close at £2.79. This frames the current price as a sizeable discount built on specific growth and profitability assumptions.
The combination of continued strong population growth, a young demographic profile, and currently low mobile and data penetration rates across Airtel Africa's markets provides a long multi-year runway for organic customer expansion and ARPU growth. This directly supports sustained increases in revenue and EBITDA.
Rapidly rising smartphone penetration (now at ~46% but still well below global averages) and accelerating data consumption (data traffic up 47%) are driving higher-value data revenues, with substantial room for further ARPU uplift and mix improvement as 2G users migrate to 4G/5G. This positively impacts both topline and margins.
See why 38 investors see Airtel Africa as 30% undervalued.
Result: Fair Value of £3.96 (UNDERVALUED)
Still, the Airtel Africa story depends heavily on currency stability and regulatory decisions. Either of these factors could quickly challenge the current undervaluation thesis.
Find out about the key risks to this Airtel Africa narrative.
Another View: Airtel Africa Through The P/E Lens
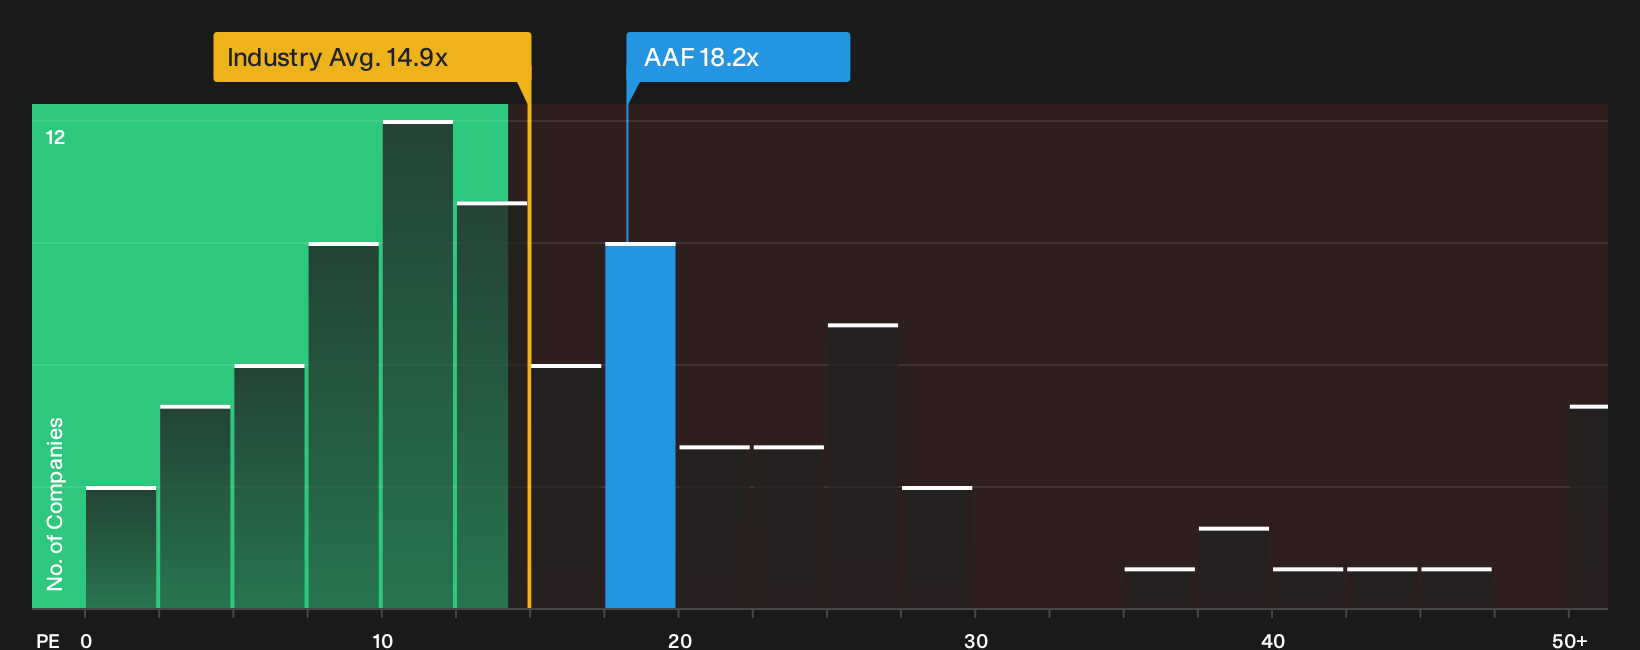
There is a very different message coming from Airtel Africa’s current P/E of 18.2x. That level is higher than the global wireless telecom industry at 14.9x, yet far below both the peer average of 41.1x and a fair ratio of 31.2x that the market could move toward.
For you, that mix of premium versus the sector and discount versus peers and the fair ratio highlights a trade-off between valuation risk if sentiment turns and potential upside if investors re-rate the stock closer to that fair ratio. Which side of that trade-off feels more realistic to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed messages around Airtel Africa leave you unsure, move quickly to check the underlying positives and pressure test the optimism yourself. Then weigh those findings against the 3 key rewards.
Looking for more Airtel Africa style investment ideas?
If Airtel Africa is on your radar, do not stop there. Broaden your watchlist and pressure test your thesis against other opportunities before the market moves on.
- Target income potential by scanning companies with resilient payouts using the 3 dividend fortresses.
- Hunt for mispriced quality by reviewing a curated 5 high quality undiscovered gems that might not yet be widely followed.
- Prioritise capital preservation by focusing on a 5 resilient stocks with low risk scores that filters for sturdier balance sheets and steadier trading profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com