
Will Third Quarter Growth Change Mettler Toledo's (MTD) Narrative
- Mettler-Toledo International reported third quarter 2026 results on 5 November, with consensus ahead of the release pointing to year over year gains in revenue and earnings per share supported by contributions from China, emerging markets, sales and marketing programs, and recent acquisitions.
- The fresh read on how China and other emerging regions are performing against softer pockets in Industrial and Lab puts a spotlight on whether Mettler-Toledo International's mix shift toward higher value services and process analytics is holding up in real operating conditions.
- We will now look at how Mettler-Toledo International's investment narrative could be shaped by anticipated third quarter revenue and EPS strength.
See how Mettler-Toledo International's latest quarter compares to other high quality operators by checking our curated list of 19 high quality undiscovered gems in similar market sweet spots.
Mettler-Toledo International Investment Narrative Recap
To be comfortable as a Mettler-Toledo International shareholder, you need to believe the shift toward higher value services, software and process analytics can keep offsetting softer demand in parts of Industrial and Lab. The upcoming third quarter numbers matter most as a real world check on that mix, especially in China and other emerging regions.
The key near term catalyst is evidence that service, bioprocessing and automation related orders are resilient enough to support margins despite tariff and cost headwinds. The biggest risk remains margin pressure if tariffs or weak European specialty chemical demand intensify faster than pricing, productivity and cost programs can respond.
The third quarter 2026 report on 5 November is the relevant milestone here. It provides a fresh look at how Mettler-Toledo International is executing on automation, digitalization and bioprocessing demand while managing tariffs and softer end markets. You are essentially watching to see whether the growth engines and the pressure points remain in balance.
Given the lack of new corporate announcements tied to this specific release, the focus stays squarely on operating delivery. Revenue of US$4.1b and net income of US$905.6m on a trailing basis set the context. However, the value in this print lies in the quality of regional trends, service traction and cost discipline, and in how those data points reshape your view of both catalysts and risks.
Mettler-Toledo International's current analyst narrative points to revenues of US$4.8b and earnings of US$1.1b by 2029, based on a 4.9% yearly revenue growth rate and an earnings increase of about US$194.4m from US$905.6m today.
Uncover why Mettler-Toledo International's fair value points to an 11% potential downside to its current price that leaves little room for error.
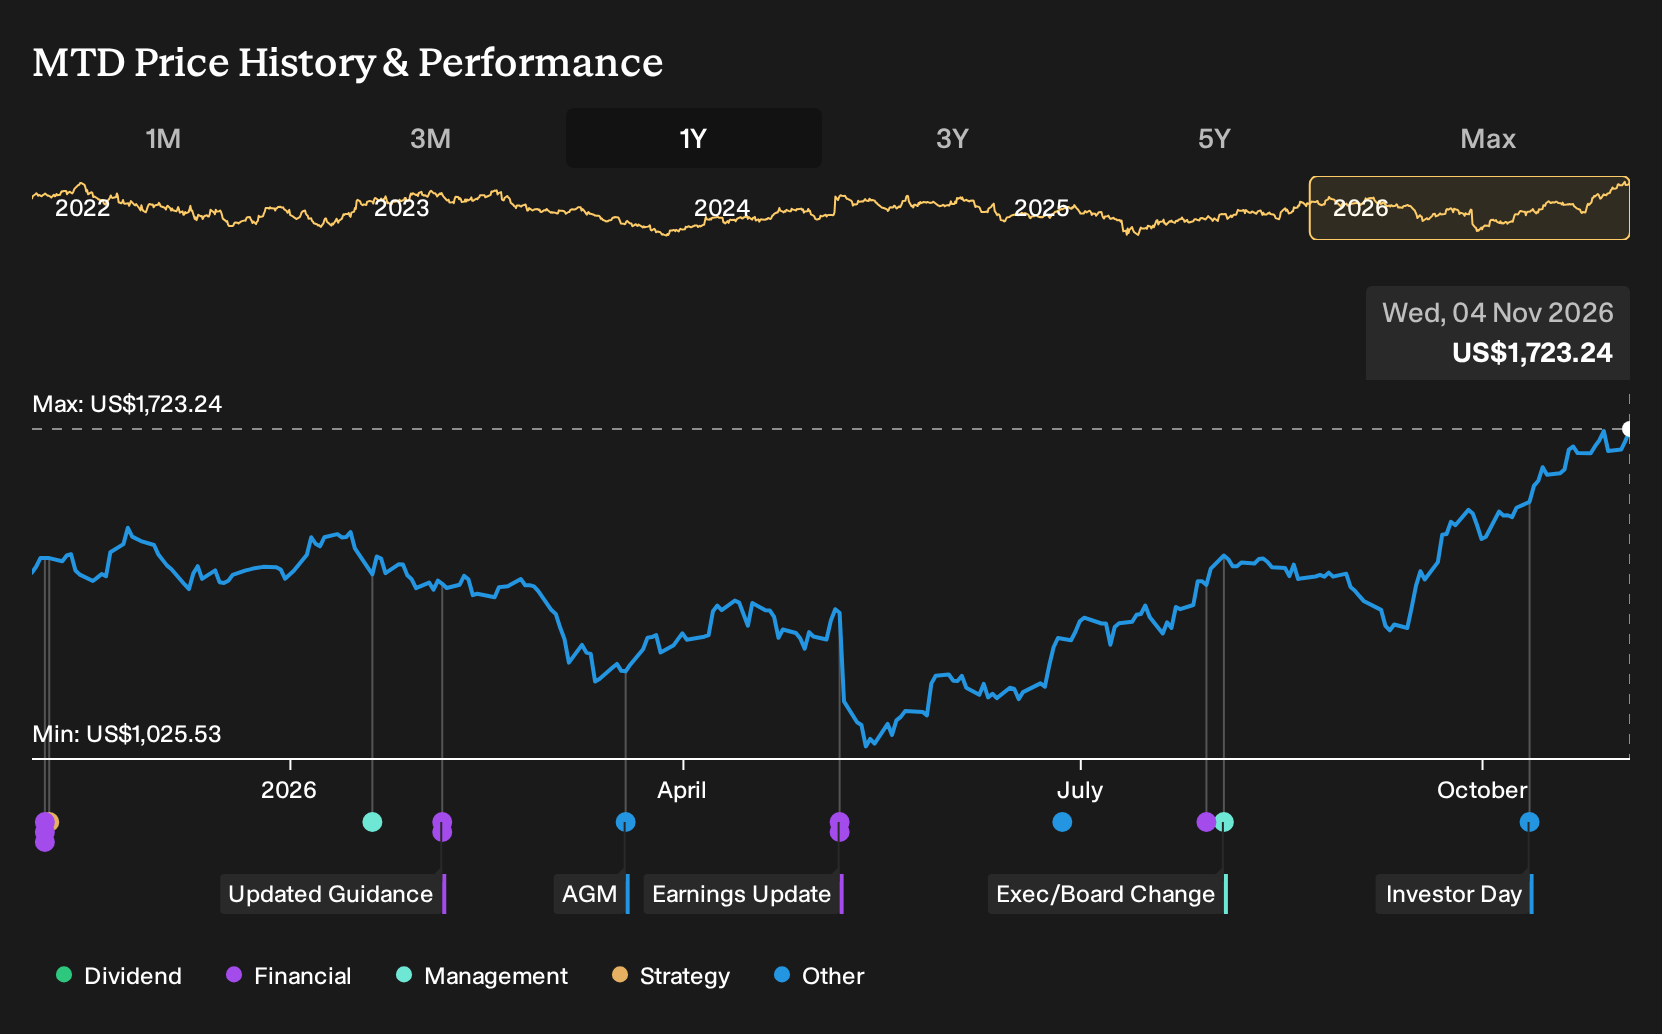
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster tightly between about US$1,414 and US$1,526 per share, so retail opinions on Mettler-Toledo International currently lean toward a narrow band. Those estimates do not yet reflect tariff or European demand risks, or potential automation and bioprocessing tailwinds. Use them as a starting point and compare several alternative perspectives before deciding how this aligns with your own expectations.
Explore another Mettler-Toledo International fair value estimate, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mettler-Toledo International research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mettler-Toledo International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mettler-Toledo International's overall financial health at a glance.
Looking for more investment ideas beyond Mettler-Toledo International?
Once you have a view on Mettler-Toledo International, it often helps to cross check that thinking against a wider watchlist. The Simply Wall St Screener can surface other businesses with traits that match your risk tolerance and return goals, so you are not relying on a single story.
- For investors who care most about strong balance sheets and resilient fundamentals, consider starting with a list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without stretching their finances.
- If your focus is on long term compounding with some valuation support, you might prefer a 34 high quality undervalued stocks that combine quality profiles with prices that still look reasonable on the numbers.
- For readers who are especially sensitive to volatility and capital preservation, it can help to build a watchlist from a 31 resilient stocks with low risk scores that score well on Simply Wall St's risk metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com