
Silgan Holdings (SLGN) Stock Climbed, What Is Behind The Latest Attention?
Silgan Holdings (SLGN) has reaffirmed its cash return policy, with the board declaring a quarterly dividend of $0.21 per share, payable on December 15, 2026, to shareholders of record on December 1.
Silgan Holdings’ latest dividend declaration lands after a busy few weeks, with the stock showing a 21.92% 1 month share price return and a 12.47% gain over the past week, while the 1 year total shareholder return of 10.68% points to steadier long run progress.
Spot 4 dividend fortresses that, like Silgan Holdings, pair consistent cash returns with established business models and have already started to move on stronger income stories.Bulls see Silgan Holdings’ steady dividend and recent share price jump as proof the market is re-rating a resilient cash generator. Bears point to softer earnings per share. Which story does the current valuation lean toward?
Most Popular Narrative: 18% Undervalued
Against a last close of $42.66, the most followed narrative for Silgan Holdings points to a fair value of $52.23. This frames the recent dividend move inside a wider story about contracts, mix and margins.
The main factor that has to go right is that Dispensing and Specialty Closures and pet food metal containers continue to deliver volume and EBIT growth that offsets mix headwinds, raw material cost lags and pockets of weakness such as Brazil.
The current valuation implies the market is giving limited credit for the guidance range on adjusted EPS, the contribution from Dispensing and Specialty Closures now representing more than half of adjusted EBITDA, and the company’s ability to generate significant free cash flow while staying within its leverage targets.
See why 4 investors see Silgan Holdings as 18% undervalued.
Result: Fair Value of $52.23 (UNDERVALUED)
Still, the bullish narrative around Silgan Holdings can unravel if resin and other input costs stay elevated for longer, or if Brazil-style volume pressure spreads to more regions.
Find out about the key risks to this Silgan Holdings narrative.
Another View: What Multiples Say About Silgan Holdings
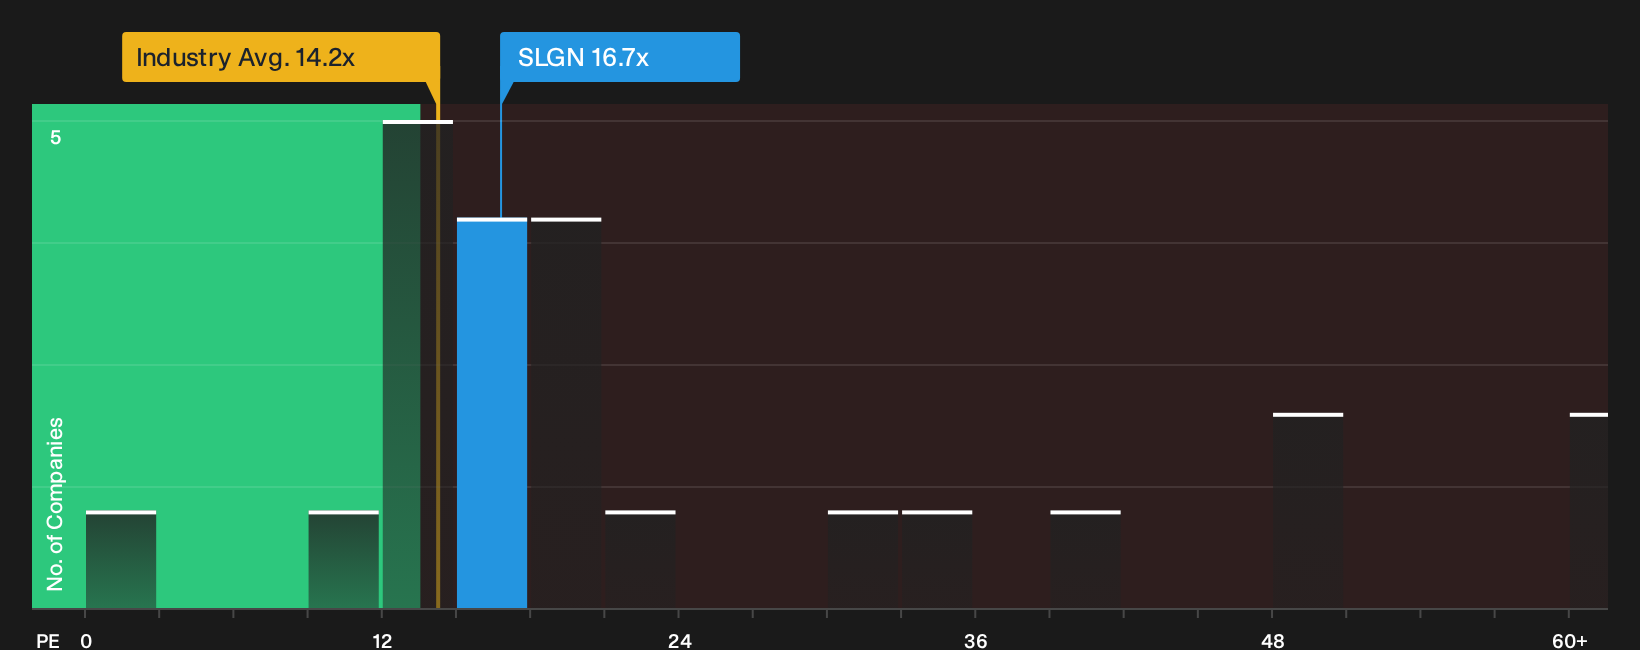
Silgan Holdings screens as undervalued on fair value estimates, yet the market is not giving it away on earnings. The stock trades on a P/E of 16.7x, which is richer than the Global Packaging industry at 14.1x, but lower than its peer average of 30.2x and under a fair ratio of 18.8x.
That mix of a premium to the sector, a discount to direct peers and some headroom to the fair ratio points to real valuation risk if earnings disappoint, but also room for sentiment to improve if execution lines up with forecasts. Which side of that balance feels more realistic to you right now, given your own expectations for the business?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Silgan Holdings story appears mixed so far. If you want to move quickly and base your own view on hard data, consider reviewing the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Silgan Holdings?
If Silgan Holdings has sharpened your focus on quality and price, broaden your watchlist now so you do not miss the next compelling setup.
- Target dependable income by scanning companies that combine higher yields with balance sheet strength using the 4 dividend fortresses.
- Hunt for mispriced quality by reviewing the 34 high quality undervalued stocks that pair resilient fundamentals with room for sentiment to catch up.
- Strengthen capital preservation by filtering for the 30 resilient stocks with low risk scores that keep volatility and financial red flags in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com