
Does Revenue And EPS Drop Change The Bull Case For Universal (UVV)?
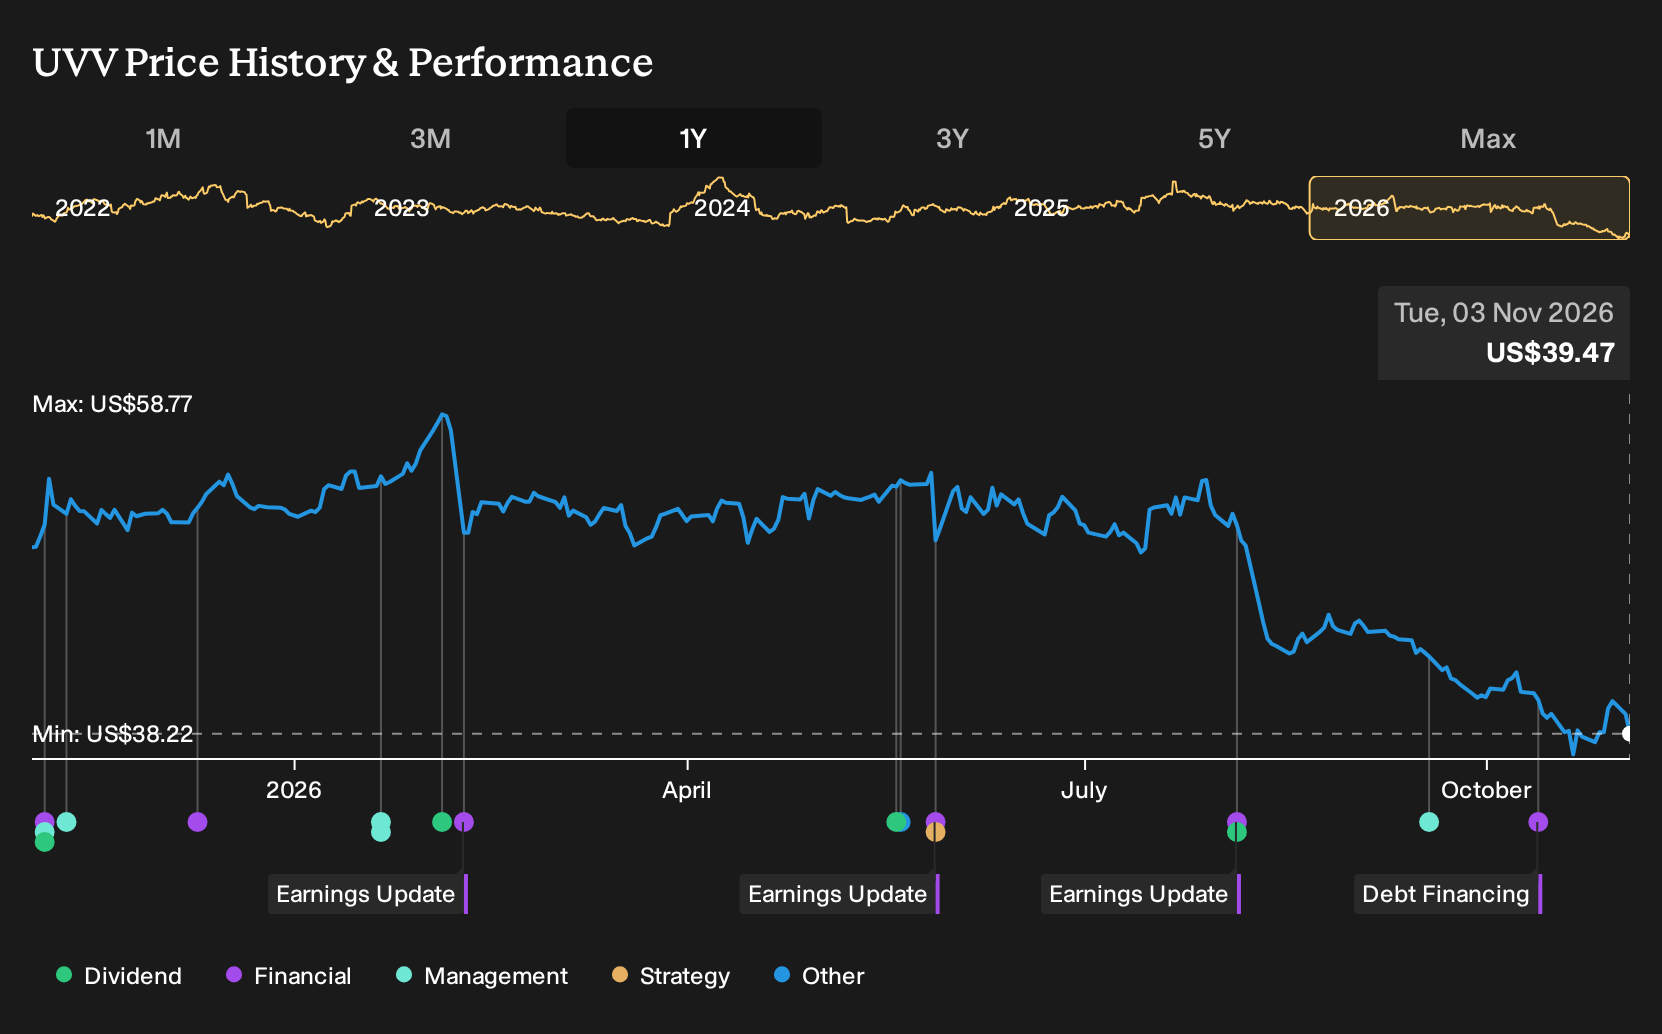
- Universal Corporation has scheduled its Q2 2027 earnings release for after the market close on 4 November 2026, following a recent quarter where revenue declined 11.8% and earnings per share fell 44.3%.
- The business currently carries net debt of $877.6 million, equal to 3.8x EBITDA, while paying an 8.02% dividend yield at $3.32 per share annually. This puts balance sheet pressure and cash distributions in sharp focus for investors.
- We will look at how Universal's investment narrative aligns with the sharp earnings drop reported last quarter and the upcoming Q2 results.
Scan beyond Universal's upcoming Q2 report and compare its balance sheet and income profile with a curated list of solid balance sheet and fundamentals (23 results) that may handle earnings pressure very differently.
Universal Investment Narrative Recap
An investor in Universal needs to believe the tobacco and ingredients operations can stabilise earnings after a sharp setback. That means tighter control of working capital, steady demand from large manufacturers, and better utilisation in the ingredients facilities. The near term catalyst is whether Q2 shows any easing in the 11.8% revenue drop and 44.3% EPS fall.
The biggest risk right now sits in the combination of margin pressure and leverage. Net debt of US$877.6 million at 3.8x EBITDA leaves less room if pricing weakens or volumes soften further. If Q2 fails to show progress on profitability or cash generation, that balance sheet strain stays front of mind.
The upcoming Q2 2027 release on 4 November 2026 is the key announcement tying all of this together. It gives you a fresh look at how Universal is handling expected oversupply in leaf tobacco, tariff uncertainty, and the drag from a less favourable product mix in ingredients. Those issues sit behind the recent revenue and earnings declines.
This update also matters for income focused holders watching the 8.02% dividend yield and US$3.32 per share payout. Earnings coverage is already thin and interest costs are not well covered. Any further squeeze on margins or cash flow would increase the risk that the current capital return profile proves hard to maintain over time.
What Analysts Are Building Into The Universal Story
Universal's narrative projects revenues of US$2.7b and earnings of US$235.7 million by 2029, based on a starting point of revenue that analysts expect to decline 1.3% per year and current earnings of US$19.1 million. This implies an earnings increase of about US$216.6 million over that period.
Uncover why Universal's fair value indicates a 70% potential upside to its current price that investors may see materialize sooner than expected.
Exploring Other Perspectives
Simply Wall St Community members only provide two fair value estimates for Universal, ranging from US$67 up to about US$183 per share, which signals a very wide spread in expectations. Those views were formed before the recent 11.8% revenue drop and 44.3% EPS fall, so you may want to weigh fresh earnings pressure, tobacco oversupply risk, and ingredients margin strain before deciding which camp you lean toward.
Explore another Universal fair value estimate, including one that suggests as much as 363% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Universal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal's overall financial health at a glance.
Looking For More Investment Ideas Beyond Universal?
Once you have a view on Universal, it can help to put that thesis alongside other opportunities that offer different mixes of balance sheet strength, income potential, and valuation appeal. The Simply Wall St Screener is built for exactly that kind of comparison.
- For investors who care most about financial resilience, start with a 30 resilient stocks with low risk scores that have historically handled tougher conditions with lower volatility and stronger balance sheets.
- If income is your priority, scan a focused set of 4 dividend fortresses that combine higher yields with fundamentals you can scrutinize in detail.
- To widen your opportunity set beyond well known stocks, comb through a curated 19 high quality undiscovered gems that may not yet be heavily followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com