
Did Lindt's Fall Catch You Out? What Investors Missed
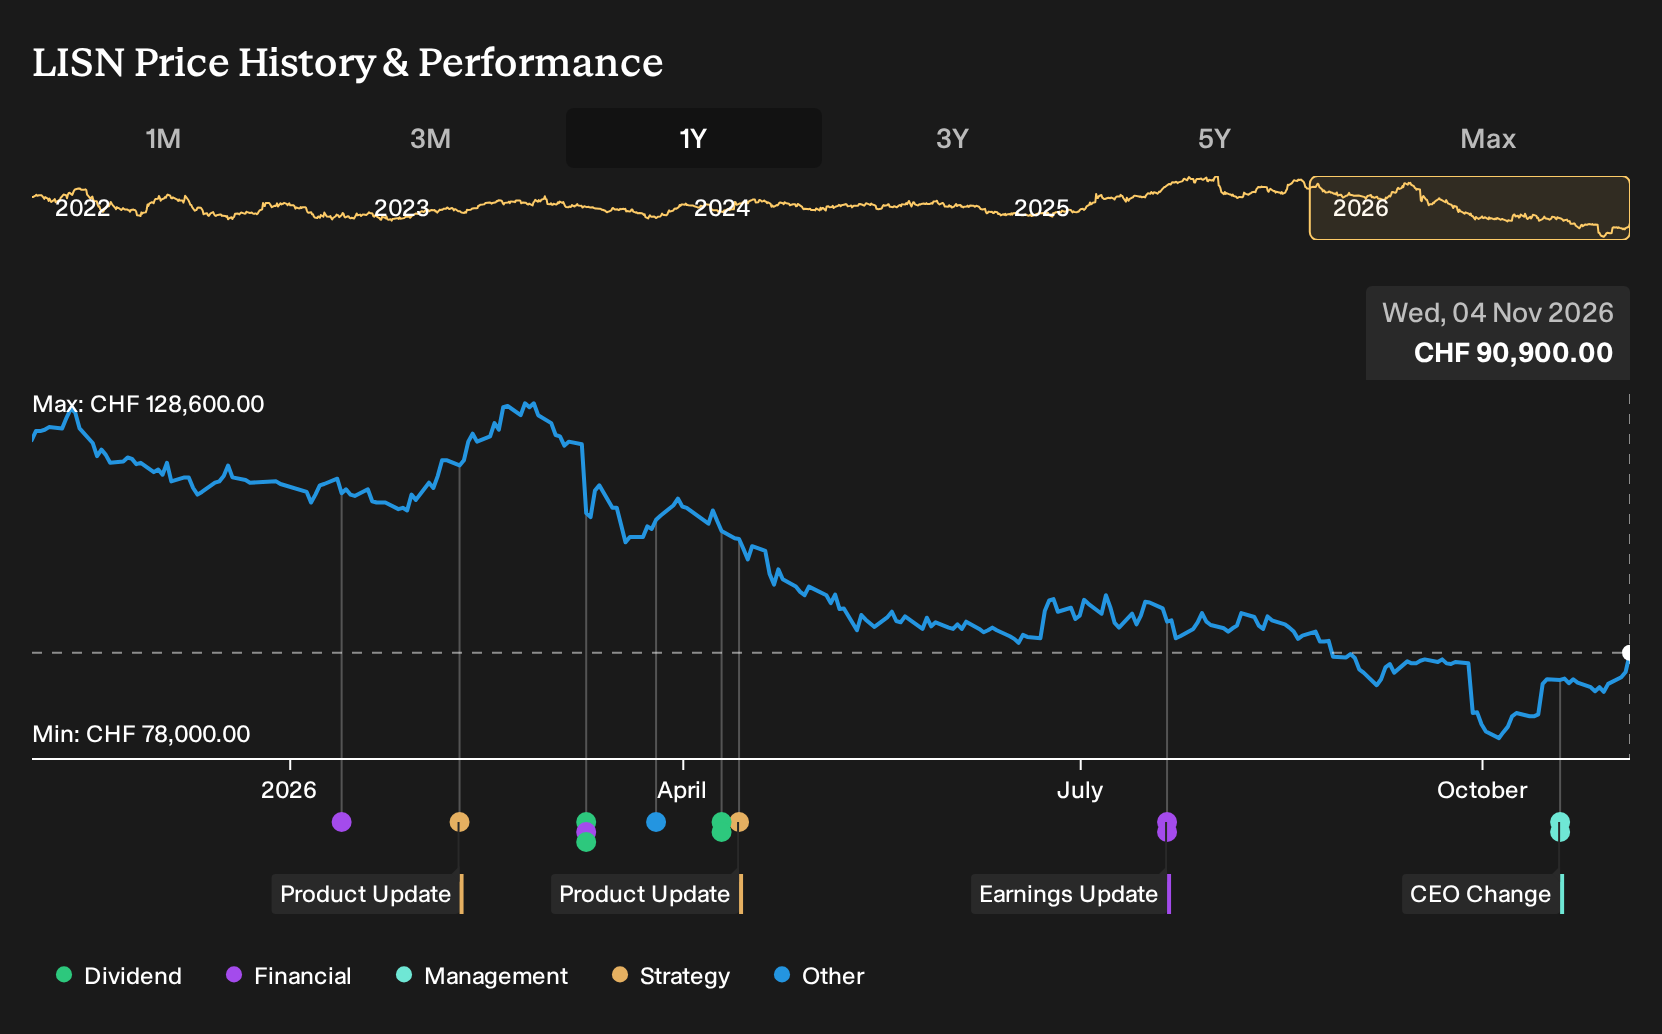
If you had looked at Chocoladefabriken Lindt & Sprüngli in late 2025 and decided that the bullish analysts had the better story, the opportunity might have seemed too tempting to ignore. For Chocoladefabriken Lindt & Sprüngli shareholders, the loss over the past year was 25.7%, including dividends. With that result now on the table, which assumptions or early warnings in those July 2025 forecasts most deserved closer scrutiny at the time?
If the move has made Chocoladefabriken Lindt & Sprüngli harder to judge, start where the gap is still open and scan 197 high quality undervalued stocks.
The Two Stories Investors Faced On Chocoladefabriken Lindt & Sprüngli
The shares cost CHF124,400 at the start of the period, and Chocoladefabriken Lindt & Sprüngli sat between two sharply different stories about its future.
On the bullish side, the fair value was framed at CHF147,000 as a price implied by optimistic assumptions, built on revenue rising 8.7% a year and profit margin reaching 13.0% within roughly three years.
The bearish view pointed to a fair value of CHF97,000, tied to slower 5.7% annual sales growth, and argued that changing consumer health preferences could pressure long term demand for premium chocolate.
What The Results Changed For Chocoladefabriken Lindt & Sprüngli
Lindt & Sprüngli’s key shock in the period was the CEO departure after a sales slump and a near 40% share price fall from the peak. This leaned toward the cautious case about demand and pricing power. Reported figures showed revenue slipping slightly while net income and net margin edged up, so profitability resilience partly countered the gloom. Overall, the evidence cut both ways.
The main assumption this episode tested was pricing-led growth. For any other consumer brand, you would track volume versus price changes, net revenue and net margin after large price hikes to see if shoppers are accepting the trade off.
What Today’s Chocoladefabriken Lindt & Sprüngli Price Asks You To Believe
Chocoladefabriken Lindt & Sprüngli now trades at CHF90,900 after a loss of 25.7% over the past year, while the selected Narrative’s Fair Value sits above the current price.
The Narrative focuses on global retail, emerging market subsidiaries and cash conversion. A buyer today would need to believe that price-led growth can translate into lasting volume, margin stability and strong free cash flow across Europe, North America and newer regions.
"The main factor that has to go right is that Lindt converts price-led growth and heavy cocoa and cost volatility into sustained volume growth and stable or improving margins across Europe, North America and newer markets, while maintaining premium brand strength."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 32% below our estimate - uses quick payback boutique openings and digital channels to extend brand reach.
- Company 2 - 33% below our estimate - chases data centre GPU demand while defending an entrenched AI software moat.
- Company 3 - 38% below our estimate - converts a subsea project backlog into faster tiebacks and longer service contracts.
Those are three of them. See all 195 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com