
Credo Technology Group Holding (CRDO) Leads OCP Telemetry Standards, Is The AI Upside Already Priced In?
Credo Technology Group Holding (CRDO) moved back into focus after jointly leading new Open Compute Project telemetry standards with Oracle, as investors weighed this technical milestone against recent share price weakness.
For context, Credo Technology Group Holding has swung sharply in recent months, with a 1 day share price return of 7.78% following the OCP telemetry news, a 30 day share price return down 28.98%, and a 1 year total shareholder return down 12.85%. The 3 year total shareholder return remains very large at roughly 9x, which points to long term momentum that contrasts with the recent pullback as investors reassess both growth potential in AI infrastructure and execution risks around its expanding optical products.
Scan beyond Credo Technology Group Holding and see which peers are also trying to ride the AI infrastructure build out using the curated 53 AI infrastructure stocks.
After a sharp monthly drop followed by a quick one-day rebound, Credo Technology Group Holding now presents a clear decision point. Do you pay up after the OCP bounce, or wait in case the next wobble offers a cheaper entry?
Most Popular Narrative: 30% Undervalued
On the most followed view, Credo Technology Group Holding screens as undervalued, with a narrative fair value of $215 against a last close of $150.91. That gap puts the focus squarely on whether current AI demand and margins can support the implied expectations in the years ahead.
Credo Technology Group is a high-growth semiconductor connectivity company benefiting from the expansion of AI infrastructure, data centres and high-speed optical and electrical networking. Q1 FY2027 revenue increased 114.7% year over year to $479.0 million, while Q2 revenue guidance of $525 to $535 million implies another approximately 9.6 to 11.7% sequential increase.
See why 23 investors see Credo Technology Group Holding as 30% undervalued.
Result: Fair Value of $215 (UNDERVALUED)
Still, the bullish Credo Technology Group Holding story can crack if AI infrastructure demand slows, or if revenue and margin trends fall short of guidance.
Find out about the key risks to this Credo Technology Group Holding narrative.
Another View: Multiples Say Credo Technology Group Holding Is Pricey
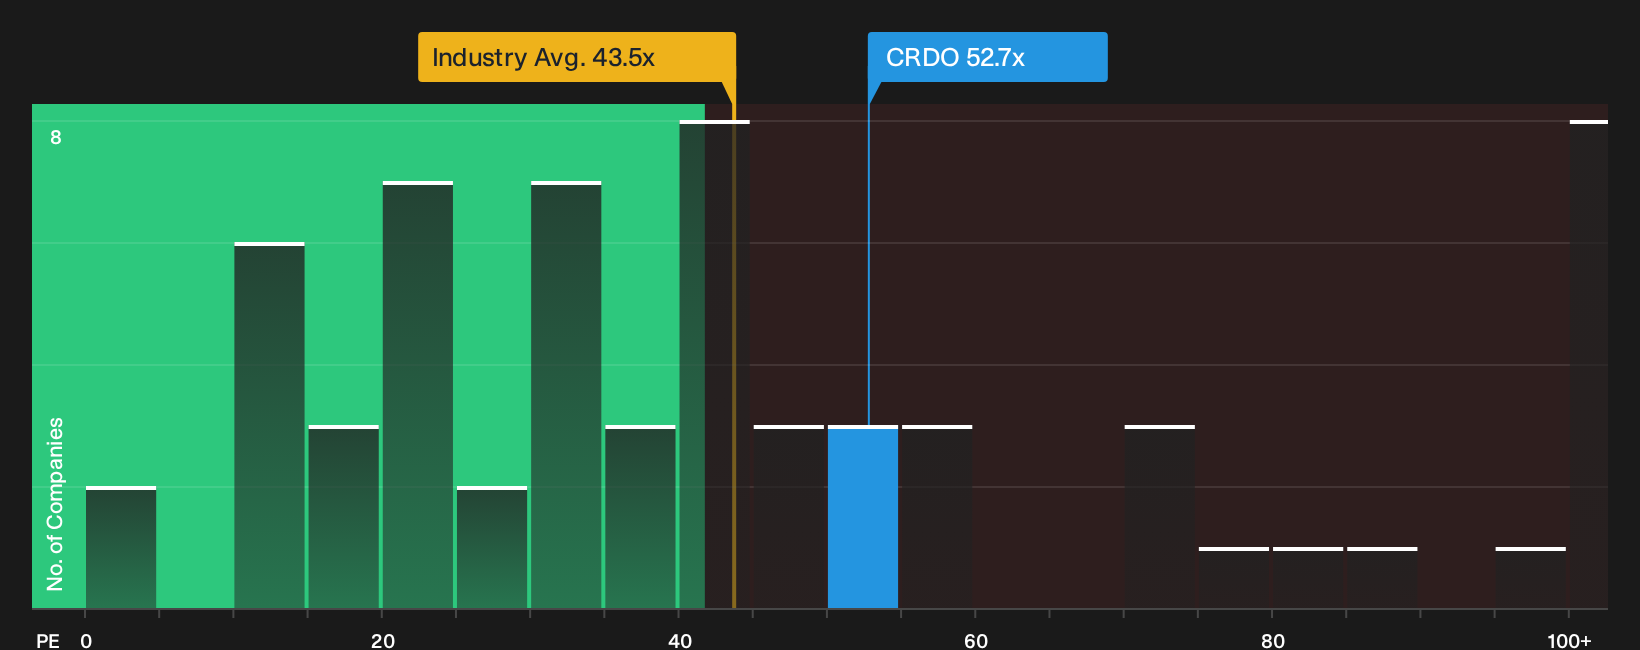
There is a very different message when you switch from narrative fair value to simple earnings multiples for Credo Technology Group Holding. The stock trades on a P/E of 52.7x, which is above the US Semiconductor industry average of 43.5x and slightly higher than the peer group at 52.5x.
It also sits above a fair ratio of 44.5x that our models suggest the P/E could drift toward over time, which points to less room for error if growth or margins wobble. The question for you is whether that premium feels like a cushion or a thin tightrope.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Credo Technology Group Holding so far, right, with both risk flags and clear bright spots in view. So move fast, review the underlying metrics yourself, and weigh the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Credo Technology Group Holding?
If Credo Technology Group Holding has you thinking harder about pricing, do not stop here. Use the screener to uncover fresh setups before the crowd does.
- Target potential bargains by scanning a curated pool of companies trading below intrinsic estimates with the 35 high quality undervalued stocks.
- Focus on resilience and capital preservation by filtering for businesses with strong finances using the list of solid balance sheet and fundamentals (23 results).
- Hunt for under-the-radar opportunities by reviewing a handpicked group of strong fundamental plays through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com