
Prediction: Micron Stock Will Triple in 2027
Key Points
Micron is one of the fastest-growing stocks on the market.
The high demand that has resulted in a severe shortage of memory chips won't ease up anytime soon.
Micron (NASDAQ: MU) stock has had a great 2026. It's the fourth-best-performing S&P 500 stock this year, rising around 220% so far. In many years, that might have been enough to make it the best-performing stock, but with so many big winners this year, it's going to have to settle for a top-five finish.
I could see it repeating this performance in 2027. How? It simply needs to execute on its business and trade at a reasonable valuation.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a "Double Down" signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same "Total Conviction" signal is flashing for a company 1/100th the size of Nvidia. Continue »
Image source: The Motley Fool.
Demand for memory chips is huge
Micron manufactures memory chips. There are two primary kinds: DRAM and NAND. NAND is what's used for long-term data storage, such as in solid-state drives (SSDs). DRAM memory is higher speed, but can't retain information when the chip is not receiving power. These are utilized inside consumer computers and AI computing units. AI computing units use a specific subsegment of DRAM, known as high bandwidth memory (HBM). While all types of memory are in short supply, HBM is where the focus truly is.
There is not enough memory chip production capacity in the world to meet surging demand, so the industry is in a supply-constrained state. Though all of the major players in the memory space are building new manufacturing facilities, that's not going to get any better anytime soon. Micron told investors during its most recent earnings call that it expects memory market tightness to get worse in 2027 and 2028.
Micron itself plans to open six new production facilities (three by mid-2027 and three in 2028) over the next two years. That will dramatically increase its production output, but it remains to be seen whether that increase, and the additional capacity of its peers, will be sufficient to satisfy AI data center operators' demand.
Furthermore, one of Micron's two chief competitors, SK Hynix, recently said that it has pre-sold all of the HBM and DRAM it will have the capacity to manufacture through 2029. Micron is likely seeing similar demand, and with capacity selling out three years in advance, it's likely that 2030 and 2031 will also see shortages.
These conditions will keep memory chip prices sky-high for many years, which bodes well for Micron's business. The memory industry has a history of cyclical downturns, but the next one may not be coming for another five years or more. That leaves plenty of time for it to make a ton of money and buy back huge amounts of stock to boost shareholder returns.
After all, its stock is dirt cheap.
The market isn't valuing Micron's stock highly
Micron's stock is valued at a cheap level, trading for just 12 times trailing earnings and 5 times forward earnings.
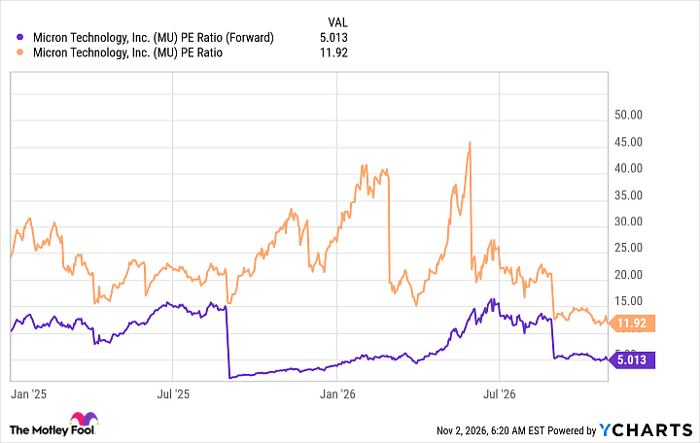
MU PE Ratio (Forward) data by YCharts.
Over the past few years, Micron's stock has traded above 20 times trailing earnings. If the company hits analyst expectations and its stock returns to that level, it would quadruple. While I think there is a strong likelihood that the market is actually underappreciating Micron's growth drivers, I'm not confident the stock will be fairly valued.
The market currently has a bearish outlook on AI due to the sheer amount of capex spending that is happening in the space. However, I think that's a short-sighted view, and the amount of growth in the AI sector justifies the spending. All of the AI hyperscalers have told investors that they view the risk of underspending and falling behind as far worse than the risk of overspending on infrastructure. Furthermore, that market is still in a complex, contested state right now, so overspending on AI computing capacity really isn't a worry, at least right now.
Micron will continue to play a huge part in the AI infrastructure build-out, and right now looks like an excellent time to buy the stock.
Keithen Drury has positions in Micron Technology. The Motley Fool has positions in and recommends Micron Technology. The Motley Fool has a disclosure policy.