
Keysight Stock Gets A Fresh Look After AI Test Launches And CFO Handover
- Keysight Technologies has recently launched the XR3 low profile 14-bit oscilloscope and showcased AI driven test solutions across AI infrastructure, high speed interconnects, RF, cyber security and EV charging, while outlining an orderly CFO handover from long serving finance chief Neil Dougherty to Jason Kary.
- The product roll out and AI focused test portfolio indicate a closer integration between Keysight Technologies hardware, higher margin software tools and recurring services, at the same time that an internally promoted CFO with operational and capital markets experience steps in to manage that evolving mix.
- This analysis examines how Keysight Technologies' investment narrative is influenced by the XR3 launch and the broader expansion of its AI centric test portfolio.
Keysight Technologies Investment Narrative Recap
For an investor to stay with Keysight Technologies, the core belief is that demand for AI centric test, high speed interconnects and aerospace or defense programs keeps feeding a rich mix of instruments, software and recurring services. The near term swing factor is still execution on that mix shift and the Spirent integration, which the latest XR3 and AI test launches generally support rather than reset.
The biggest near term risk remains operational, not headline driven. Supply constraints that have pushed about US$100m of orders outside the normal revenue window, and any stumble in hitting planned Spirent cost synergies, could limit margin progress even with solid order flow. Recent announcements do not remove that exposure.
The XR3 oscilloscope is the clearest operational link to the current AI and data center test theme. It adds dense, 1U rack friendly measurement capacity with 14 bit resolution and hardware accelerated analysis tools tied into Keysight’s software ecosystem. That kind of product is designed for multi rack, high channel count environments where AI servers, optical links and power systems all need parallel test and debug.
Viewed alongside Keysight’s AI driven measurement portfolio, the XR3 illustrates how hardware, emulation software and services can be sold as a package, which is central to the margin story investors are watching. It also raises the execution bar. Management needs to keep new products tightly integrated with Spirent assets, maintain support quality across complex systems and avoid new bottlenecks that could worsen the existing supply and timing risk.
Keysight Technologies' current analyst narrative points to revenues of US$10.4b and earnings of US$2.8b by 2029, based on an assumed 16.5% yearly revenue growth rate and an earnings increase of about US$1.5b from US$1.3b today.
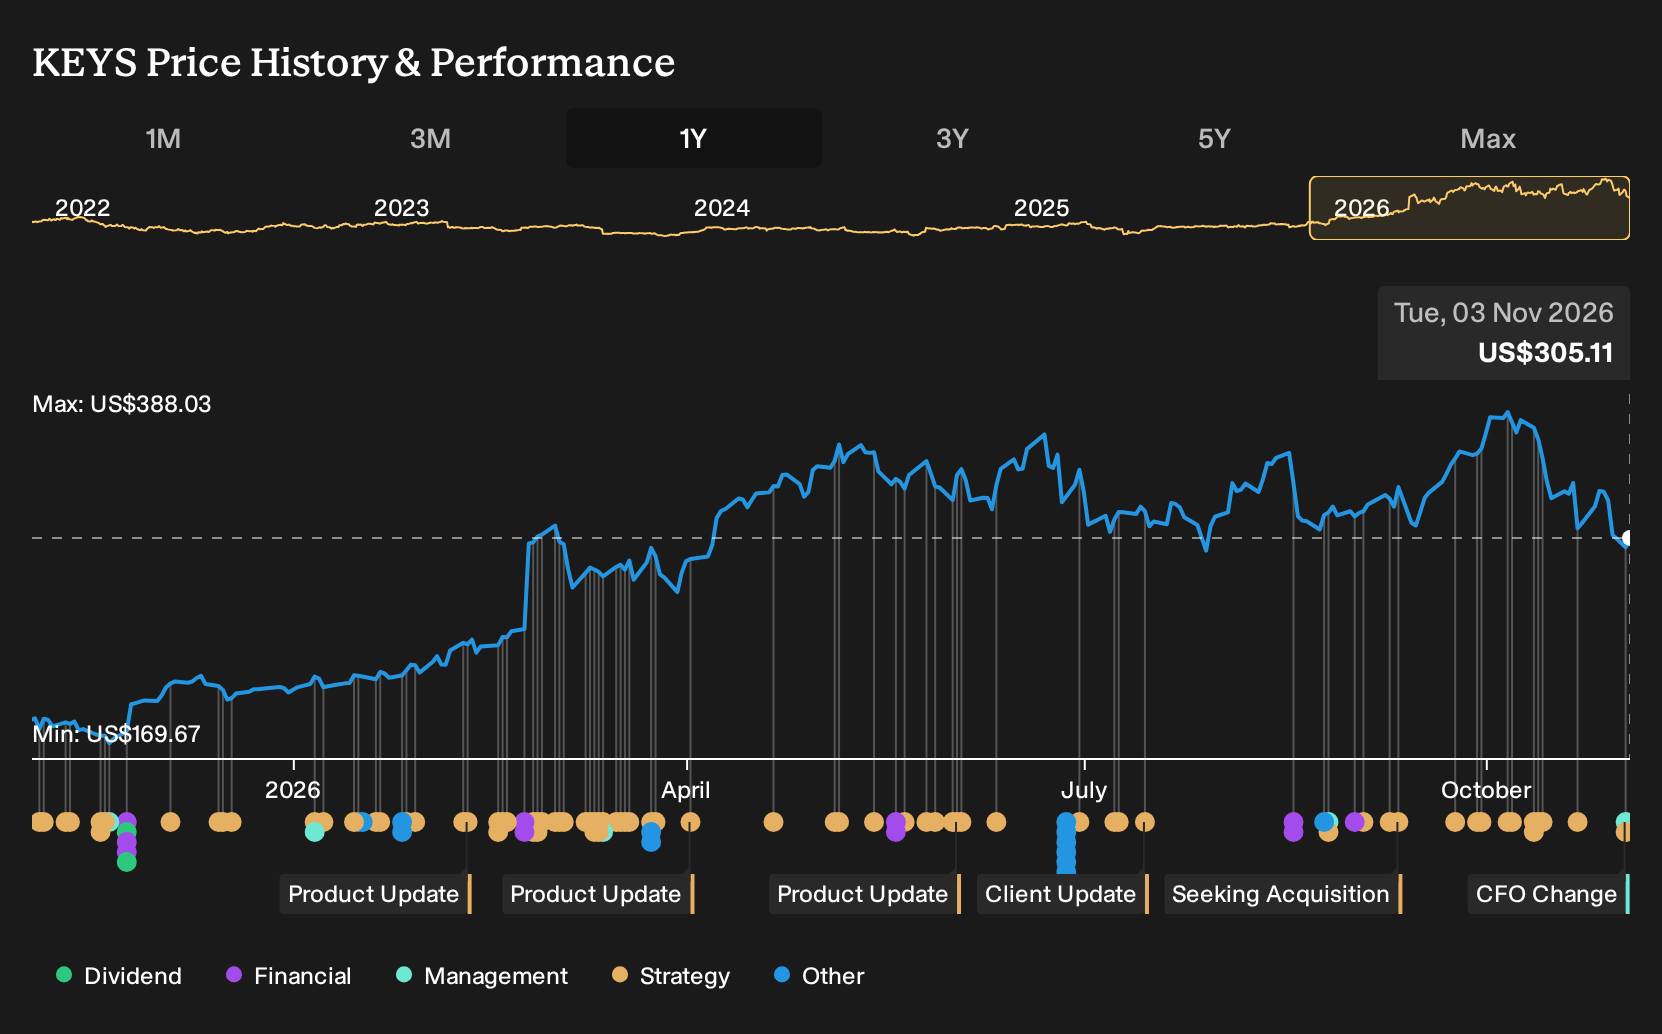
Uncover why Keysight Technologies' fair value indicates a 36% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Keysight Technologies focuses on supply constraints as a future tailwind rather than a headache. Those analysts were already pencilling in about US$11.2b of revenue and US$3.1b of earnings by 2029, ahead of consensus. With the XR3 and AI heavy test launches now on the table, opinions may spread out even further, so it can help to compare several narratives before deciding what this news means for you.
Explore 2 other Keysight Technologies fair value estimates, including one that suggests as much as 38% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Keysight Technologies research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Keysight Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keysight Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Keysight Technologies?
Once you have a view on Keysight Technologies, it can help to line it up against other opportunities that fit different goals, from income to resilience to potential mispricing. The Simply Wall St Screener gives you a quick way to scan for stocks that match the type of portfolio you want to build, rather than forcing everything through the same lens as Keysight.
- If you care most about valuation and quality together, use our screener to review 35 high quality undervalued stocks that combine stronger fundamentals with prices that analysts consider attractive.
- For readers who put capital preservation near the top of the list, the same tool can surface 30 resilient stocks with low risk scores that may suit a more cautious approach.
- Those hunting for under the radar opportunities can filter for 19 high quality undiscovered gems that pair solid business profiles with relatively limited attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com