
Nebius Stock Faces AI Data Center Permit Risk After US Election Results
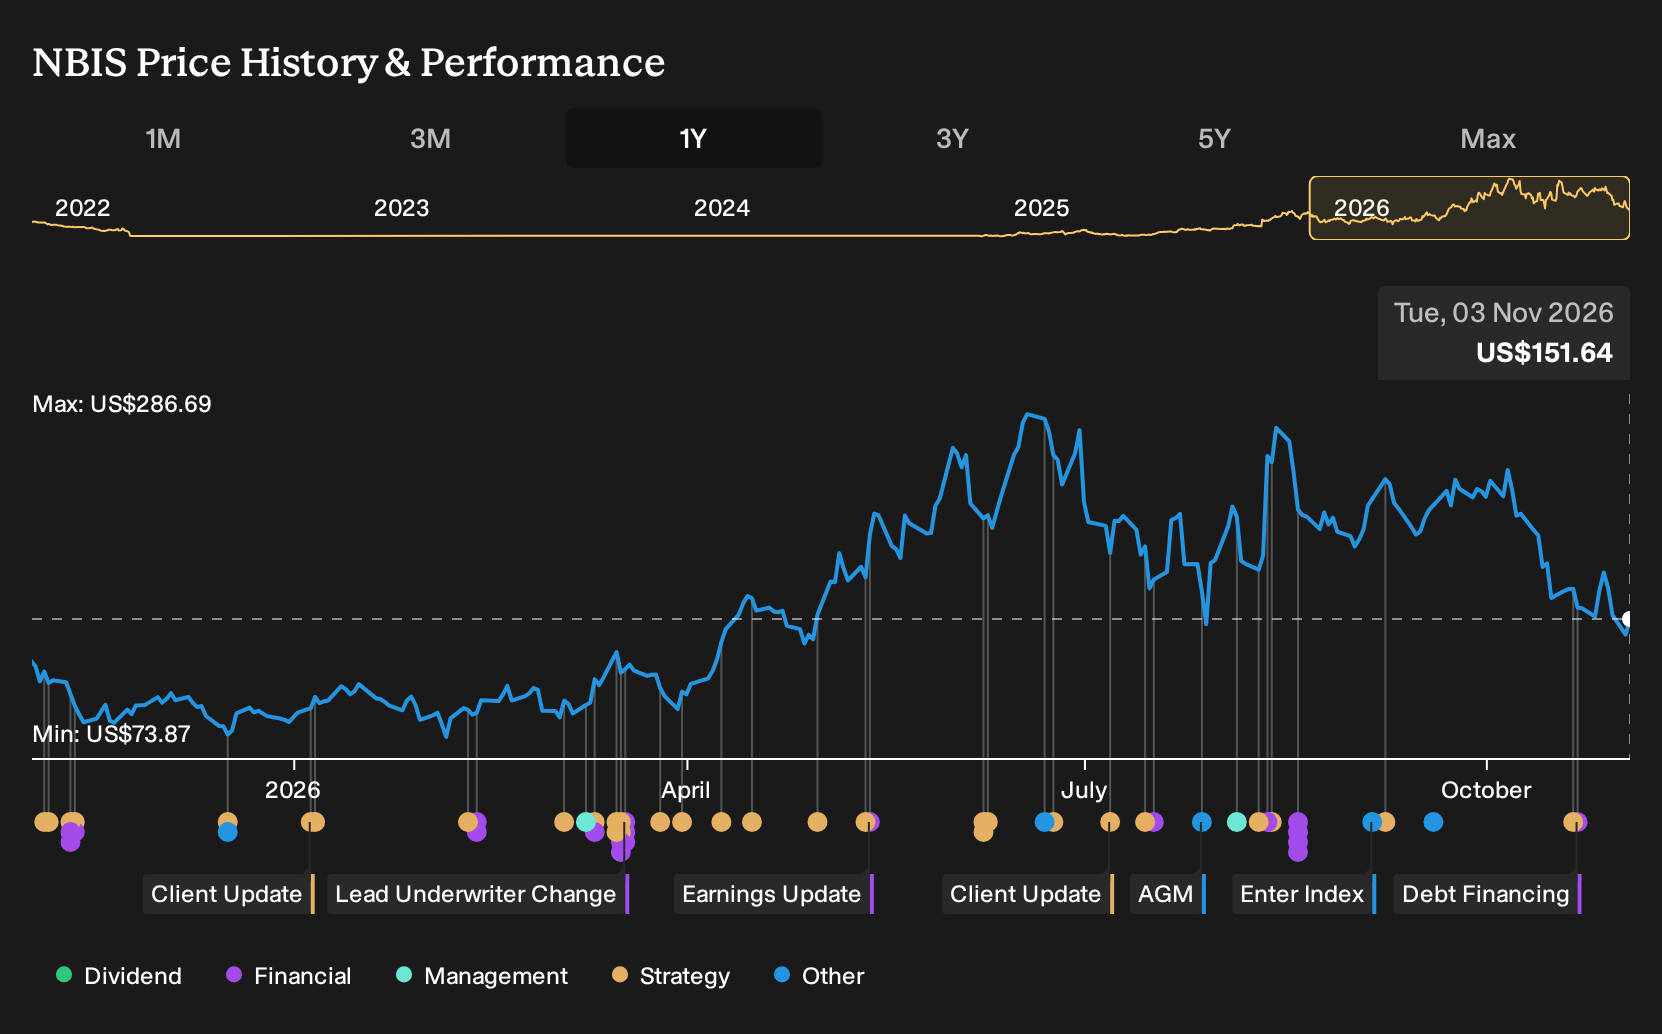
- Nebius Group N.V. entered into a US$3.5b senior secured facility with Citi to support its global AI data center build-out and broaden its funding sources.
- Alongside this financing, Nebius is rolling out live GPU spot pricing, rebate programs and expanded AI Builder support across Europe, which directly targets customer cost control and utilization of high-cost GPU capacity.
- We will now examine how Nebius Group's investment narrative is affected by rising regulatory risk related to new AI data centers.
Compare Nebius Group's AI data center story with hand-picked peers by scanning the 53 AI infrastructure stocks that are also racing to secure capital and scarce GPU capacity.
Nebius Group Investment Narrative Recap
To own Nebius Group, you need to believe its full stack AI infrastructure can keep attracting large, long-duration contracts while it scales data center capacity efficiently across the US and Europe. The US$3.5b Citi facility strengthens Nebius Group’s ability to fund that build. The key near term catalyst is execution against its current contract backlog and how convincingly management updates investors at the November 12 report.
The biggest risk right now sits on the regulatory side. Election results and talk of moratoriums on new AI data centers in key states could slow US build timelines or raise power related costs. If approvals drag or environmental rules tighten, Nebius Group’s heavy capital spending could take longer to translate into usable capacity and revenue.
The most relevant recent announcement here is Nebius Group’s public live spot pricing and capacity tools for GPU compute across Europe. That roll out gives customers a clearer handle on usage and cost, while the rebate program helps reduce idle GPU time. Together, these steps tighten the operational link between expensive hardware and billable workloads.
For investors watching catalysts, that operational focus matters as regulatory questions grow louder in the US. Stronger utilization and more predictable pricing on the European footprint can partially counter any delays in American data center projects. It also puts more weight on Nebius Group’s ability to manage margins, especially with profit margins currently at 3.1% and heavy data center spending funded largely with external borrowing.
Nebius Group's narrative projects US$29.3b revenue and US$2.7b earnings by 2029. That profile assumes revenue growth of 178.7% a year and an earnings increase of about 64x from US$42.4m today.
Uncover why Nebius Group's fair value indicates an 85% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most cautious analysts focus less on regulation and more on funding risk for Nebius Group. Before this week’s debt deal, the lowest forecasts already assumed revenue of about US$23.9b and earnings of roughly US$3.0b by 2029, yet implied a much lower P/E of 15.9x. That is a far more skeptical story about how future capital, including the new US$3.5b facility, might be priced and what equity holders could reasonably expect. Use that contrast as a prompt to explore multiple narratives rather than anchor on any single forecast.
Explore 11 other Nebius Group fair value estimates, including one that suggests as much as 28% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nebius Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Nebius Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nebius Group's overall financial health at a glance.
Looking For More Ideas Beyond Nebius Group?
If you want to stress test your thesis on Nebius Group against other opportunities, the Simply Wall St Screener can help you quickly spot different types of stocks that match your risk and return preferences.
- For investors who care most about valuation support and quality fundamentals, scan a focused universe through 35 high quality undervalued stocks that may offer more grounding for your next idea.
- If capital preservation and smoother portfolio swings matter to you, filter candidates with steadier profiles by checking out the 30 resilient stocks with low risk scores as a starting watchlist.
- When you want to get ahead of the crowd and research potential up and comers early, narrow the field using the 19 high quality undiscovered gems that meet your quality and fundamentals criteria.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com