
Viridian Therapeutics (VRDN) Could Be 32% Undervalued Following Lumvoa FDA Approval
Viridian Therapeutics (VRDN) is back in focus after the recent FDA approval and immediate launch of Lumvoa for thyroid eye disease, a key milestone that now stands alongside softer third quarter earnings.
The recent FDA green light for Lumvoa has arrived alongside a mixed trading picture, with Viridian Therapeutics’ share price up 29.64% over the past month and 19.36% over 90 days, yet down 18.02% year to date. The 3-year total shareholder return of 70.51% signals longer term holders have still seen material gains as sentiment has swung with regulatory progress and widening losses.
Scan how Viridian Therapeutics fits into the broader rare disease opportunity set by reviewing the hand-picked 34 healthcare AI stocks that blend cutting-edge therapy development with AI-driven drug discovery.
Viridian Therapeutics has already rerated on Lumvoa’s approval, yet the market is still weighing heavier losses against that new thyroid eye disease asset. Has most of the revaluation already happened, or is the bigger move still ahead?
Most Popular Viridian Therapeutics Narrative: 32% Undervalued
On the most followed narrative, Viridian Therapeutics screens at a fair value of $36.75 against a last close of $25.15, so the gap between modeled cash flows and market price is wide on these numbers.
A roughly US$2b TED IGF-1R market with 6,000 to 7,000 patients treated annually and single digit penetration gives Viridian Therapeutics room to grow within an underpenetrated class.
A concentrated prescriber base of about 2,000 core physicians and a field force of just under 100 sales reps, combined with buy and bill distribution and limited need for channel stocking, may allow Viridian Therapeutics to generate incremental revenue without a proportionate rise in operating expenses.
See why 2 investors see Viridian Therapeutics as 32% undervalued.
Result: Fair Value of $36.75 (UNDERVALUED)
Still, Viridian Therapeutics needs analyst optimism on rapid revenue expansion and a sharp margin swing to hold, since slower uptake or higher costs could quickly challenge this undervalued narrative.
Find out about the key risks to this Viridian Therapeutics narrative.
Another View: Viridian Therapeutics Looks Expensive On Sales
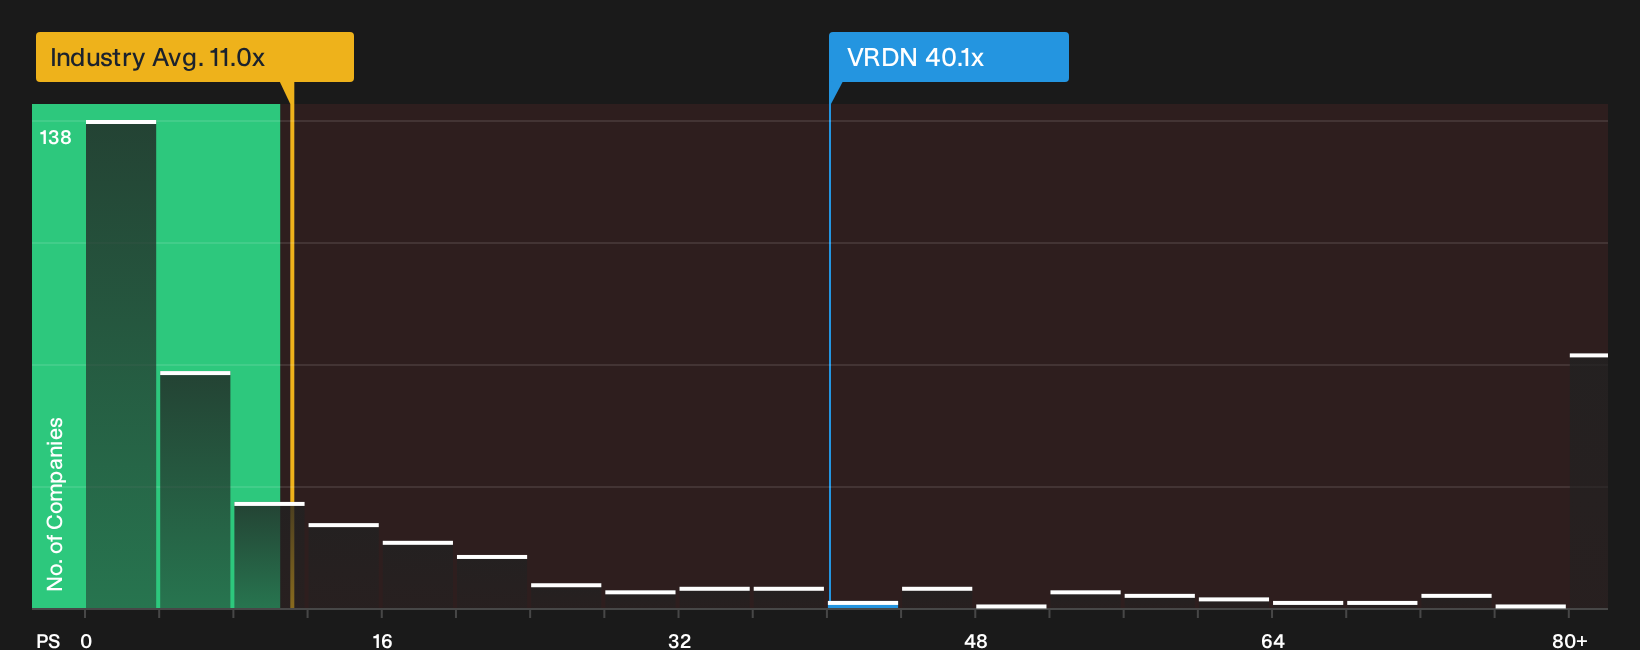
Viridian Therapeutics screens as undervalued on cash flow models, yet its P/S ratio of 40.1x is far above the US Biotechs industry at 11.3x and peers at 10.8x. The fair ratio sits at just 0.1x. How comfortable are you paying such a premium for revenue that is still early stage?
For investors who want to see how this high P/S compares with detailed earnings and cash flow scenarios, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Viridian Therapeutics so far, with both caution and optimism in play. Consider reviewing the underlying numbers yourself and weighing the 2 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Viridian Therapeutics?
Broaden your opportunity set beyond Viridian Therapeutics and put fresh ideas on your radar with targeted screeners that surface different types of potential setups.
Skip the noise and focus on potential upside by reviewing 19 high quality undiscovered gems that pair strong fundamentals with lower visibility in the market.
- Target dependable income streams by checking out 4 dividend fortresses that aim to combine higher yields with a focus on resilience.
- Limit portfolio shocks by scanning 30 resilient stocks with low risk scores that prioritise financial strength and historically steadier performance profiles.
- Hunt for mispriced quality by using 35 high quality undervalued stocks built to surface businesses where fundamentals and current pricing appear out of sync.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com