
Top 3 Undervalued Stocks To Watch In November 2026
When oil prices rebound on renewed Middle East supply fears, investors often rush toward whatever looks most resilient and liquid. That rush can overlook quieter businesses that keep generating solid cash flow while their share prices lag behind estimated fair value. That mismatch is where potential opportunity sits for patient buyers. This article highlights three stocks that our cash flow focused screen currently flags as trading below intrinsic value.
The three stocks covered below are only a small sample, as the full screen surfaced 452 more businesses with similarly interesting cash flow stories that do not fit into a short article. To see the complete list and quickly identify ideas that fit your style, head straight to the Undervalued Stocks Based On Cash Flows screener.
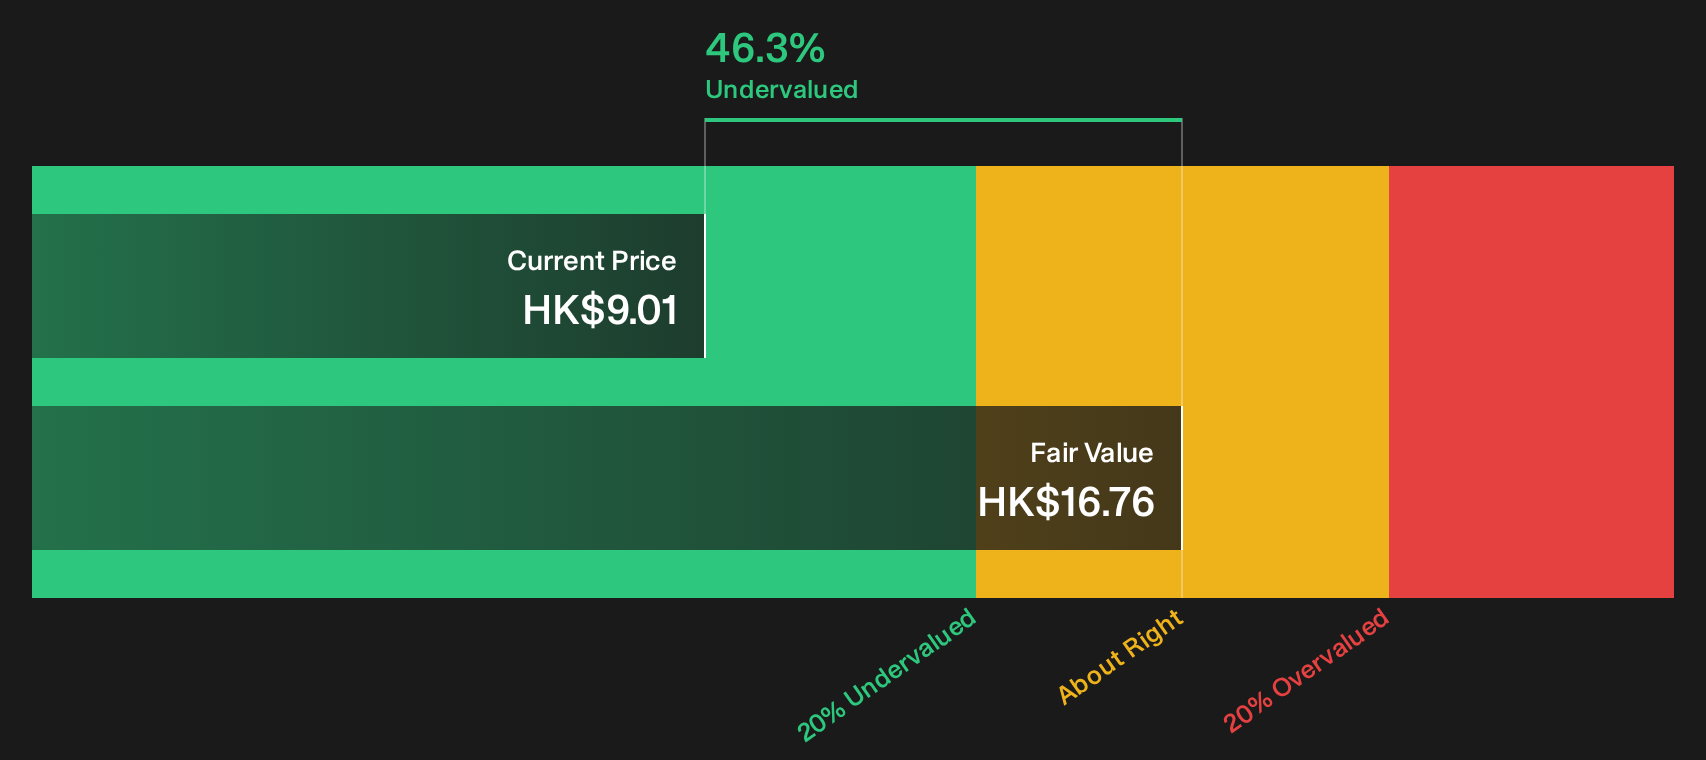
China Tower (SEHK:788)
Overview: China Tower operates telecom towers and related digital infrastructure across China, earning recurring fees from long-term site, power and maintenance services.
Operations: The business generates all its CN¥98.1b revenue from telecommunications tower infrastructure services and related activities in mainland China.
Market Cap: HK$157.5b
China Tower matters for this cash flow focused screen because its shared tower network and site services convert long-term telecom demand into recurring rental income.
"The ongoing rollout and densification of 5G infrastructure in China, now reflected in China Tower adding 364,000 new 5G base stations in 2025 and 187,000 in the first half of 2026 with over 95% delivered through co-location, continues to support leasing demand that can help sustain tower and DAS revenue and support earnings."
What happens to that earnings profile now largely hinges on how one less visible funding pressure shapes free cash flow and future flexibility.
That funding trade off is exactly what the full narrative for China Tower unpacks, showing where cash generation, leverage and telecom demand might be quietly decoupling from the share price.
MINEBEA MITSUMI (TSE:6479)
Overview: MINEBEA MITSUMI supplies bearings, motors, sensing devices and access hardware used in electronics, autos and industrial equipment worldwide.
Operations: MINEBEA MITSUMI generates revenue mainly from Semiconductors & Electronics at ¥613.5b, Motor, Lighting & Sensing at ¥491.2b and Access Solutions at ¥338.3b.
Market Cap: ¥1.22t
MINEBEA MITSUMI matters for this cash flow focused list because its Motor, Lighting & Sensing products tie long-term OEM contracts directly to recurring cash generation, even though they share the stage with several sizeable segments.
"MinebeaMitsumi is expanding monthly ball bearing capacity from roughly 404 million units to over 460 million by late 2028 to serve AI server and data center demand, which could lift group revenue and support operating margin leverage as higher value bearings scale."
What happens to that earnings power now largely depends on how one untested shift in demand mix filters through pricing and long-run margins.
That demand shift is exactly what the full narrative for MINEBEA MITSUMI unpacks in detail, separating temporary noise from areas where MINEBEA MITSUMI’s cash engine could quietly be accelerating.

CyberAgent (TSE:4751)
Overview: CyberAgent runs internet advertising, media streaming, and smartphone game services in Japan, monetising digital audiences through ads and content.
Operations: CyberAgent generates ¥478.2b from Internet Advertising, ¥269.7b from Game, and ¥246.6b from Media & IP, almost entirely in Japan.
Market Cap: ¥650.4b
CyberAgent fits this cash flow focused screen because its internet advertising arm turns Ameba traffic and related media assets into recurring, high visibility ad revenue that underpins group earnings, while other divisions contribute additional monetisation layers.
"The Media & IP segment, including ABEMA, has moved from gradually decreasing losses to reporting operating profit of JPY 4.9b in the first quarter of FY 2026 while ABEMA turned profitable, so further monetisation of original IP such as anime and films now has a clearer path to influence segment revenue and operating margins."
What happens to that improved profit base now hinges on how one evolving mix between advertising, media and games reshapes margins over the next few years.
That shifting mix is exactly what the full narrative for CyberAgent unpacks. It maps where CyberAgent’s cash flows may be quietly accelerating while old segment labels still mask the change.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout list will not stay under the radar for long. Scan these fresh lineups before the crowd and consider your options.
- Target reliable income ideas by scanning a curated mix of high-yield companies in the 215 dividend fortresses while payout strength and price support still align.
- Explore the next wave of growth by reviewing curated 160 AI small caps that already pair real revenue traction with AI momentum.
- Monitor electrification trends by tracking producers in the 16 top copper producer stocks while demand stories are still being priced in gradually.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com