
Curtiss Wright (CW) Reshapes Leadership And Capacity, Is The Stock Cheap?
Curtiss-Wright (CW) has put leadership changes and fresh capital spending at the center of its story. New Segment Presidents and a planned US$30 million Texas expansion give investors concrete moves to track.
Over the past year Curtiss-Wright has swung between strong history and a tougher recent patch, with the share price up 2.82% in the last session and 4.37% over the past week, but down 8.77% over 30 days and 33.49% over 90 days. Long-term total shareholder returns of 140.51% over three years and 273.36% over five years point to momentum that has built over time, even as recent moves suggest investors are reassessing growth prospects and risk around the US$497.76 price level in light of the leadership reshuffle and US$30 million Texas expansion.
Spot similar leadership and capacity expansion stories at work by scanning our hand-picked 41 power grid technology and infrastructure stocks, which highlights opportunities at the intersection of manufacturing investment, infrastructure build out, and long-term industrial demand.After a sharp 90 day slide and fresh headlines on leadership and Texas spending, the real fork in the road is simple. Do you treat Curtiss-Wright’s current valuation as an entry point now, or wait for a clearer reset?
Most Popular Narrative: 27% Undervalued
The prevailing Curtiss-Wright narrative pegs fair value at about $681, well above the recent $497.76 close. This frames the recent share price slide as a discount that rests on some demanding assumptions about growth, margins, and capital deployment actually playing out.
The global nuclear resurgence remains in play for Curtiss-Wright. Management now expects the commercial nuclear business to roughly double from its 2023 base by 2028 and to reach about US$1.5b in annual revenue by the mid 2030s, with potential AP1000 and SMR content supporting a long-cycle uplift in segment revenue and margins that is not yet fully reflected in near term guidance.
See why 18 investors see Curtiss-Wright as 27% undervalued.
Result: Fair Value of $681.38 (UNDERVALUED)
Still, Curtiss-Wright’s reliance on large defense and nuclear contracts, along with questions over whether investors will keep paying a higher P/E, could both weaken that undervaluation story.
Find out about the key risks to this Curtiss-Wright narrative.
Another View: Curtiss-Wright Looks Expensive On Earnings
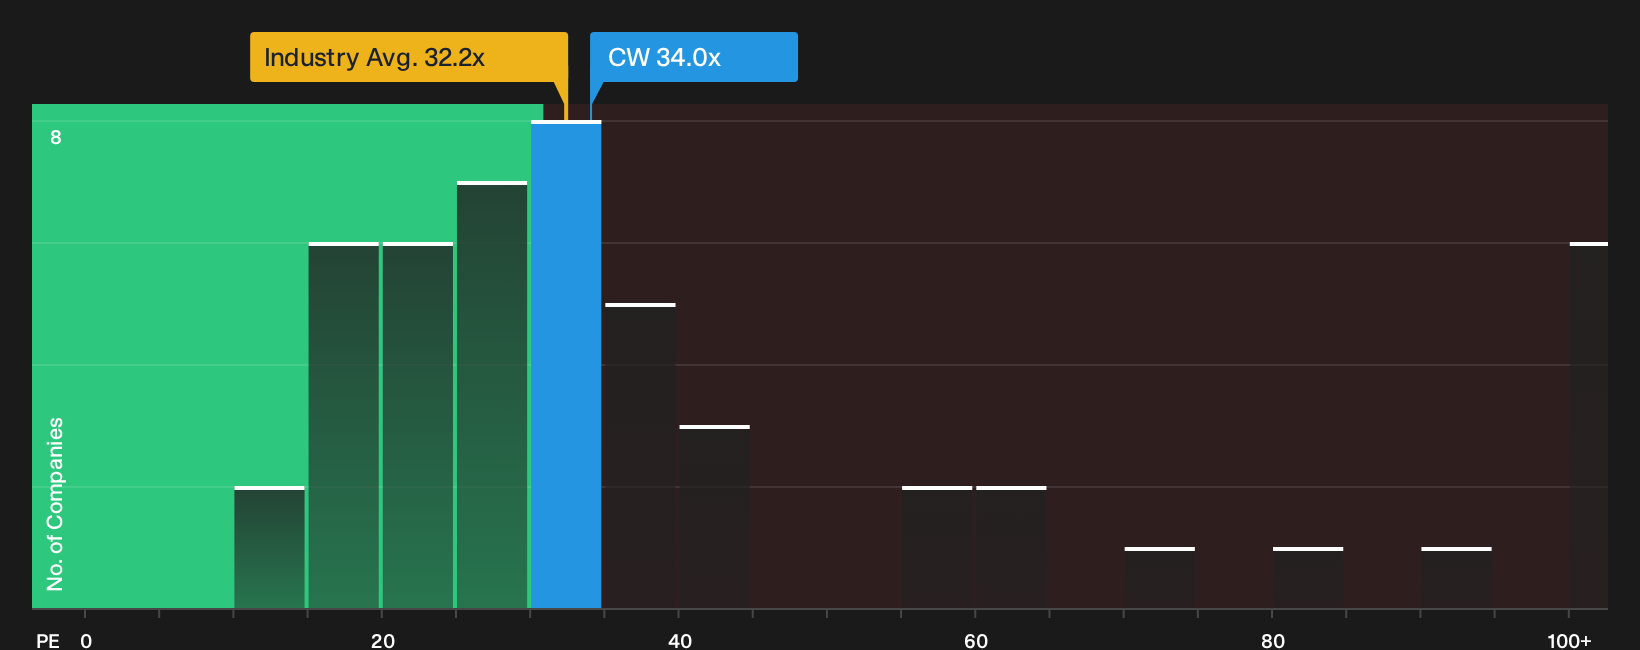
The story changes once you leave the analyst target behind and look at Curtiss-Wright’s current P/E. The stock trades on roughly 34x earnings, compared with a fair ratio estimate of 24x and a peer average of 30.2x, which suggests valuation risk if sentiment cools.
That premium multiple also sits above the wider US Aerospace & Defense industry at 32.2x. As a result, you are not only paying more than Curtiss-Wright’s own fair ratio estimate, you are also paying more than the broader sector. The question is simple: are you comfortable underwriting that extra 10 turns of P/E if growth or nuclear enthusiasm slows?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Curtiss-Wright’s value story. If you want to move quickly and form your own take, start by weighing the 2 key rewards
Looking for more Curtiss-Wright investment ideas?
If Curtiss-Wright has sharpened your focus on pricing power and execution risk, do not stop here. Broader idea hunting now can sharpen every decision you make.
- Target resilient compounders by reviewing a 35 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Prioritise capital strength through a list of solid balance sheet and fundamentals (23 results) that surfaces companies with robust finances backing their future plans.
- Spot underfollowed opportunities using a 19 high quality undiscovered gems that highlights strong fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com