
How Earnings Beat At Impinj (PI) Has Changed Its Investment Story
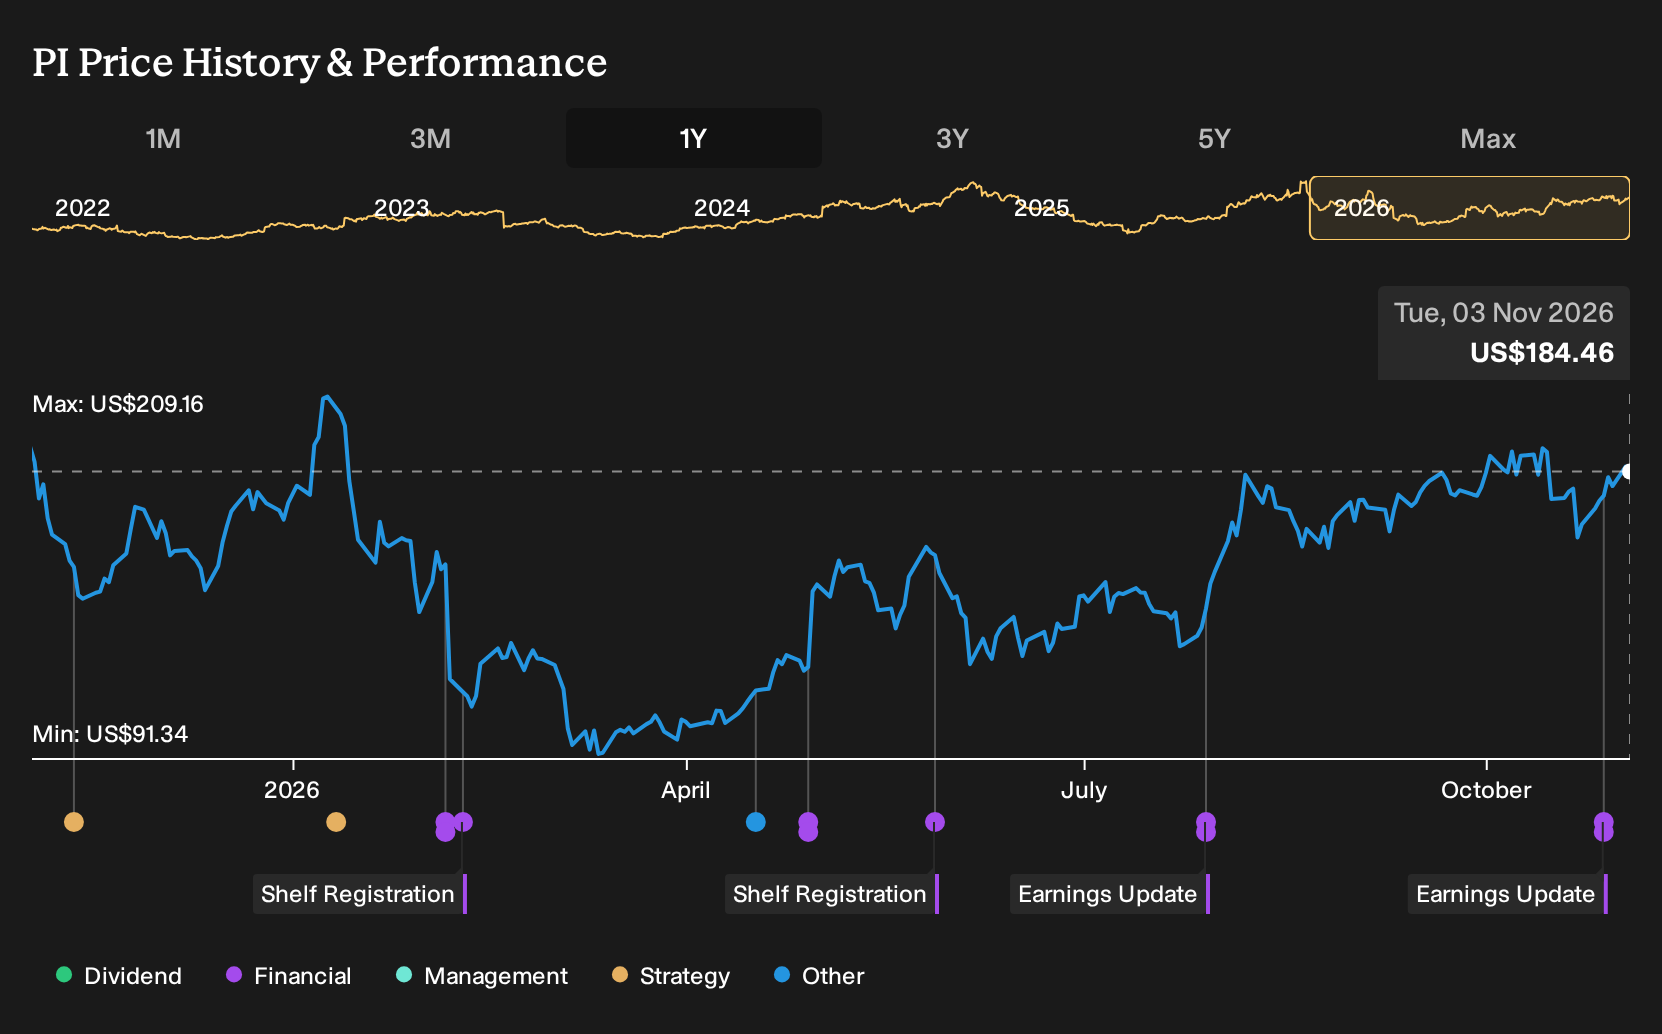
- Impinj reported Q3 2026 sales of US$112.08 million and net income of US$4.68 million, with basic and diluted EPS of US$0.15. The company issued Q4 guidance calling for US$104 million to US$107 million of revenue and GAAP net income of US$1.2 million to US$2.7 million.
- The quarter showed Impinj balancing stronger demand for RFID endpoint ICs with early signs of margin improvement. However, nine month results still reflected a net loss, which keeps execution on capacity investments and cost discipline central to the story.
- The focus now turns to how Impinj's return to quarterly profitability could reshape the existing investment narrative around growth and execution.
Scan beyond Impinj and line up other potential RFID and hardware beneficiaries by reviewing our hand picked list of 53 AI infrastructure stocks for your watchlist.
Impinj Investment Narrative Recap
To own Impinj, you need to believe the company can turn strong RFID endpoint IC demand into durable profitability while keeping execution tight. Q3 2026 moves that thesis forward, with US$112.08 million of sales and a US$4.68 million profit showing the model can generate earnings at current scale. The key near term catalyst remains margin progress as M800 mix grows and software starts to matter more.
The biggest operational risk still sits in demand visibility and gross margin volatility, especially given past missteps with a large logistics customer and sensitivity to pricing and input costs. Nine month figures, with a net loss of US$8.36 million, underline that one profitable quarter does not remove that concern. The new Q4 guide looks incremental rather than thesis changing.
The most relevant update for that thesis is Impinj's Q4 2026 outlook. Management is calling for US$104 million to US$107 million of revenue and GAAP net income of US$1.2 million to US$2.7 million. If delivered, this would mark back to back profitable quarters. For an investor, that is the cleanest near term test of whether recent margin and mix gains can be sustained.
Ahead of that print, the setup is straightforward. The business has shown it can earn money at current volume, but the full year still reflects a loss, so consistency now matters more than one strong period. Analyst ratings are mixed, which keeps the spotlight squarely on Impinj's execution against this guidance and its ability to hold profitability while funding capacity and R&D.
Impinj's current analyst narrative points to revenues of US$650.1 million and earnings of US$107.2 million by 2029. That pathway assumes revenue grows at 18.8% a year and earnings rise by about US$116.7 million from today’s loss of US$9.5 million.
Discover how Impinj's fair value indicates an 8% potential upside to its current price that could close sooner than many investors expect.
Exploring Other Perspectives
One bullish twist on Impinj hinges on how far item level food and logistics deployments can go. The most optimistic analysts were pencilling in about US$714.3 million of revenue and US$135.0 million of earnings by 2029 before this Q3 report, far above consensus. That gap shows how widely views can differ. Use this earnings beat and fresh guidance as a prompt to compare those optimistic forecasts with your own expectations and to explore several possible paths for the story from here.
Explore 2 other Impinj fair value estimates, including one that suggests up to 12% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Impinj research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Impinj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Impinj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Impinj?
If this Impinj update has sharpened your view on the stock, you can apply that same perspective to a wider opportunity set. The Simply Wall St Screener lets you quickly filter for companies that fit your risk tolerance, income needs, and quality preferences so you can build a watchlist that matches your own playbook.
- For investors who want potential upside while still considering quality, start by scanning our 19 high quality undiscovered gems that combine strong fundamentals with under-the-radar profiles.
- If capital preservation and steadier performance matter most to you, narrow your focus to the 30 resilient stocks with low risk scores that score well on balance sheet strength and volatility checks.
- Income focused readers can concentrate on cash payouts by reviewing the 4 dividend fortresses that pair higher yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com