
What American Eagle Outfitters Holders Got Right
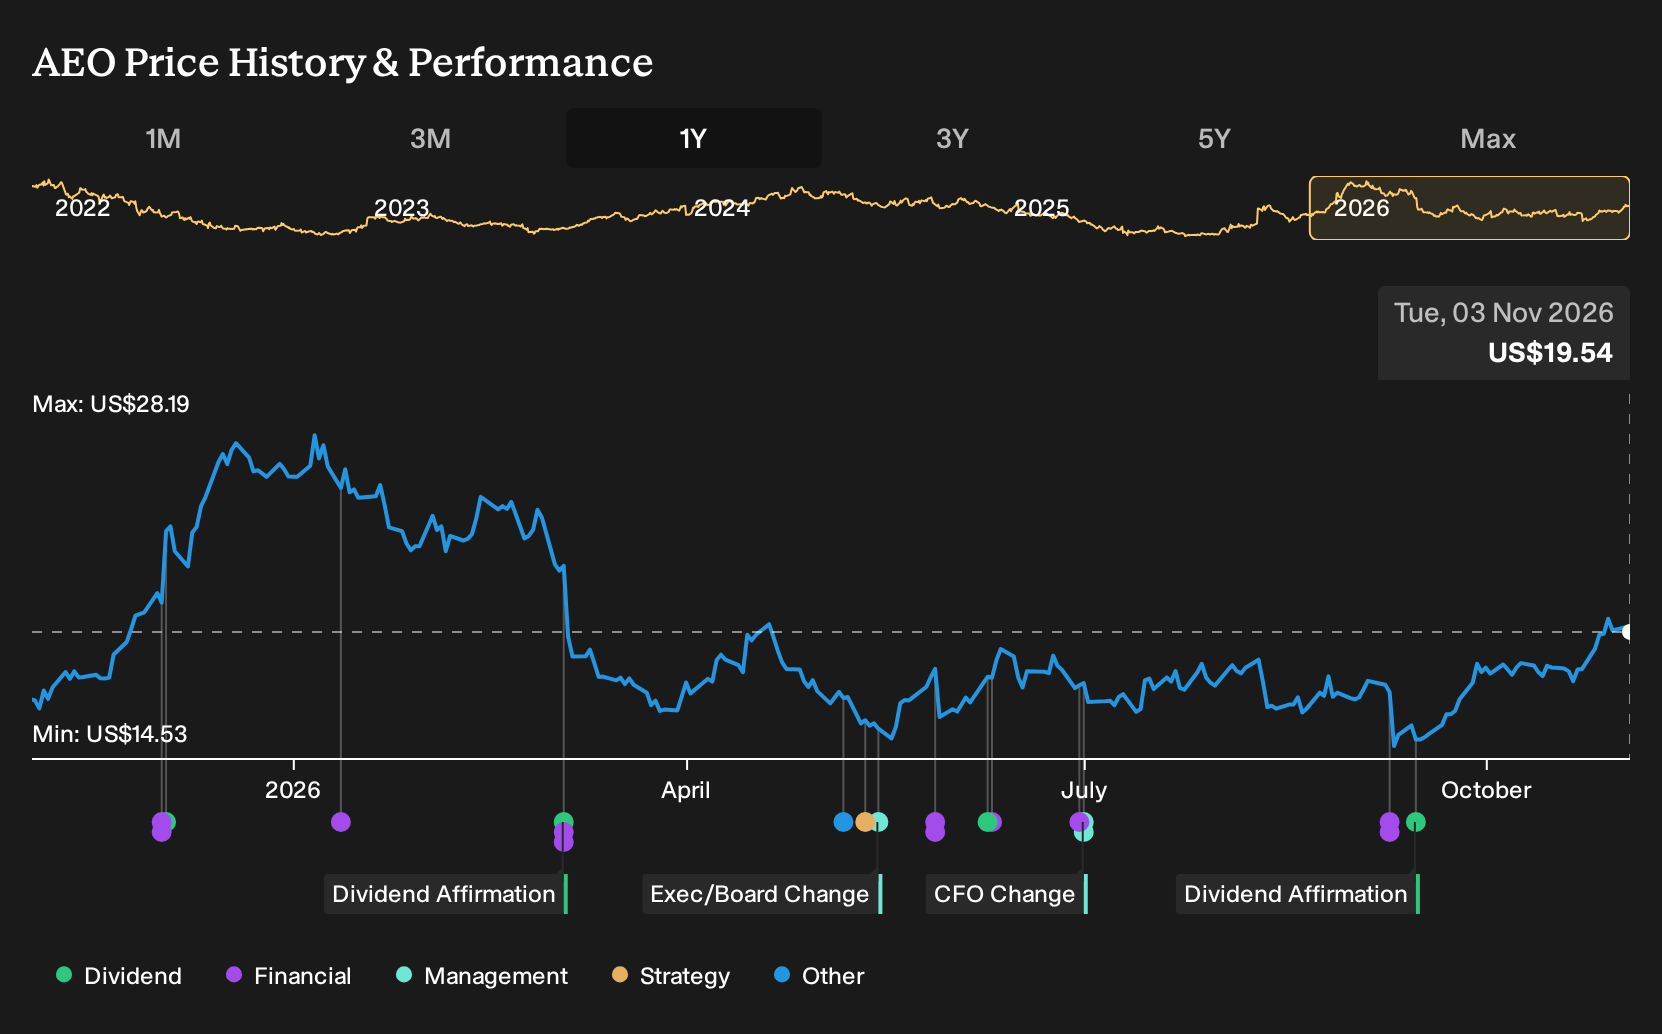
If you were watching American Eagle Outfitters this year, the flashiest headline was not a marketing partnership but the board signing off on a US$200m accelerated share repurchase program backed by record fiscal 2025 revenue of US$5.5b. Holding American Eagle Outfitters over the past year would have returned 23.9%, including dividends. If you were deciding on 3 November 2025, what did you need to believe about digital growth and Aerie’s momentum for that outcome to feel reasonable?
If the move has made American Eagle Outfitters harder to judge, start where the gap is still open and scan 35 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On American Eagle Outfitters
The shares cost US$16.53 at the start of the period, and anyone looking at American Eagle Outfitters then was really choosing between two very different stories.
The bullish view pointed to a Fair Value of US$19. This was a rough guide to what that camp thought the stock was worth if its thesis played out, built on digital integration and sustainable apparel drawing in more loyal shoppers.
The bearish narrative anchored on a Fair Value of US$9 and focused on the concern that heavier digital competition and shrinking mall traffic would keep pressure on long term sales and profitability.
What The Results Changed For The American Eagle Outfitters Debate
Aerie’s performance did a lot of the talking for American Eagle Outfitters. Record Q1 and Q2 2026 revenue, Aerie passing US$2b of trailing sales and stronger Q2 2027 profit with net margin rising from 6.0% to 9.7% all leaned toward the optimistic digital and intimates story. Softer American Eagle brand comps and tariff noise kept the cautious case alive, so the evidence cut both ways.
The key assumption was that digital-heavy, Aerie-led growth could outweigh pressure on the legacy label. When judging another retailer, track segment-level comps, profit margin and which brand is really carrying the group, not just the headline total.
What American Eagle Outfitters’ Price Now Asks You To Believe
Today American Eagle Outfitters trades at US$19.54, after a 23.9% gain over the past year. The selected Narrative’s Fair Value sits below the current price and frames that gap around how brand mix, tariff refunds, inventory and marketing spend shape earnings power.
For today’s level to feel justified, you would need confidence that Aerie and OFFLINE keep scaling, and that the American Eagle women’s reset, inventory clean-up and marketing shift land without eroding margins.
"Management is repositioning American Eagle women’s denim and bottoms. However, the early 2026 experience of underperforming women’s bottoms and seasonal categories that required elevated markdowns suggests the reset could take longer and require more discounting than expected, which would weigh on merchandise margin and net income."
One Narrative disagrees with today's price. → See where this Narrative says American Eagle Outfitters should trade
Looking Past American Eagle Outfitters
Once you understand what drives American Eagle Outfitters, it is natural to wonder what powers the wider online retail world.
Behind many digital storefronts sits a different kind of retailer, one that sells technology and infrastructure instead of jeans or intimates.
This business runs broad e-commerce platforms, cloud services and AI tools that help merchants reach buyers and manage data heavy operations.
It also holds stakes in payments, logistics and chip manufacturing, alongside a web of AI investments tied to digital commerce.
If you care about where online shopping, data processing and automation intersect, that toolkit is an intriguing next place to look.
That argument has a Narrative and a number behind it. → See the company one Narrative values 141% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com